By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
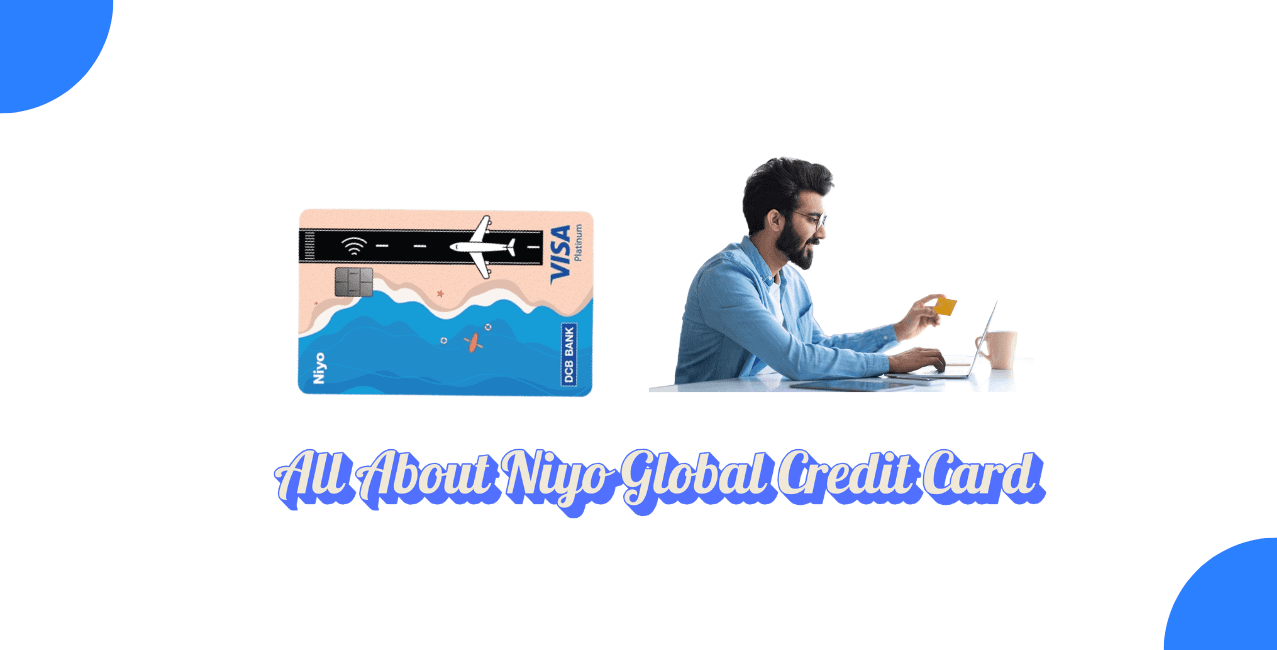
The Niyo Global Credit Card is a secured credit card backed by a Fixed Deposit with SBM Bank India, offering zero forex markup on international spends. You need a minimum FD of ₹5,000 to get started, and your credit limit is up to 90% of that deposit amount.
Key Takeaways
Anyone travelling abroad often, whether for work, studies, or leisure, knows how quickly forex markup charges add up on a regular credit card. The Niyo Global Credit Card, issued in partnership with SBM Bank India, is built specifically to cut that cost down to nothing. This guide is for anyone considering this card, covering how it actually works, the credit limit structure, eligibility, and how it compares to Niyo's debit card offering. It also covers what happens if you decide to close the card later.
The Niyo Global Credit Card is a secured credit card issued against a Fixed Deposit, so you typically do not need an existing credit history or income proof, subject to the issuer’s eligibility and verification requirements.
According to Niyo's own official page on how this card works, you start by creating a Fixed Deposit with SBM Bank, and that FD acts as security in case you miss paying your credit card dues. Since the card is secured this way, it's accessible even to people building their credit history for the first time. The card carries zero forex markup, making it particularly useful for anyone who regularly spends money outside India.
You open a Fixed Deposit with SBM Bank, and the bank issues a credit card against that deposit, with your credit limit calculated as a percentage of the FD.
Here's the process, based on Niyo's official explanation:
This structure means your money isn't sitting idle while backing the card, it's actively earning interest throughout.
Your credit limit is up to 90% of your Fixed Deposit amount, subject to applicable minimum, maximum and bank-set limits.
This means a larger FD directly translates into a higher spending limit. Since the FD interest rate goes up to 7% annually, your money continues growing even while it's backing your available credit. Unlike unsecured credit cards, where your limit depends on income proof and credit history, this structure gives you direct control over your own limit simply by adjusting your deposit amount.
Since this is a secured credit card, you typically don't need income proof or an existing credit history to apply, making it accessible to a wider range of applicants.
This makes the card particularly suited for:
Since the card is secured against an FD, an existing credit history or income proof is typically not required, subject to the issuer’s eligibility and verification requirements.
The Niyo Global Credit Card is a secured credit product backed by an FD, while the Niyo Global Card most people know is actually a debit card linked to a savings account.
Both cards share the zero forex markup benefit and the SBM Bank partnership, but they serve different purposes: one helps build credit, while the other uses your own funds for international spending without forex markup.
Closing the card also closes the Fixed Deposit linked to it. After outstanding dues and any applicable premature-withdrawal charges are deducted, the remaining FD amount and applicable interest are settled to your source account.
According to the official Most Important Terms and Conditions document, termination becomes effective only once SBM Bank receives full payment of any outstanding amount on the card. Once that's cleared, you receive the balance of your FD along with the interest earned for the period it was held. For any closure related queries, you can reach the bank through its toll-free number, 1800 1033 817, or by writing to global@goniyo.com.
Take Ananya, a graduate student preparing to study in Germany. She opens a Fixed Deposit of ₹50,000 with SBM Bank through Niyo, and her credit limit gets set at ₹45,000, up to 90% of her deposit. During her semester abroad, she uses the card for eligible international payments and everyday spending without a forex markup. Her FD continues earning interest in the background, and she avoids the credit history requirement that would have otherwise stood in her way as a first-time applicant.
The Niyo Global Credit Card offers a route into credit for eligible applicants without an existing credit score, backed by a Fixed Deposit that continues to earn interest while securing the credit limit. With zero forex markup across 180+ countries, it's built specifically for people who spend internationally and want to avoid the usual card charges. Before applying, decide how large an FD you're comfortable locking in, since that number directly determines your spending limit.
If you're someone who spends internationally often but hasn't built a strong credit history yet, the Niyo Global Credit Card offers a practical way in, without sacrificing the zero forex markup benefit that matters most for travellers. Since your credit limit is directly tied to your Fixed Deposit, choosing the right deposit amount upfront makes all the difference in how useful the card becomes for your actual spending needs.
A secured credit card issued by SBM Bank India, backed by a Fixed Deposit, offering zero forex markup on international spends.
₹5,000, as confirmed on Niyo's official page.
It's up to 90% of your Fixed Deposit amount.
Yes, up to 7% annually, as long as your card payments stay on time.
No, since it's secured against an FD, income proof or existing credit history typically isn't required.
No, it offers zero forex markup across 180+ countries.
The FD gets closed too, with outstanding dues deducted and the remaining balance, plus interest, settled with you.
No, the credit card is FD-backed, while the debit card links to a savings account.
SBM Bank India, in partnership with Niyo.
Call the toll-free number 1800 1033 817, or email global@goniyo.com.