Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Anishka Bhadly is a content writer with a finance and business background. She has completed her bachelor's degree with a specialisation in finance and is currently pursuing an MBA in the finance field too. The knowledge she has gained from her studies and experience working with EdTech companies helped her combine theoretical knowledge with practical industry insight. Her expertise lies in creating well-researched, informative, and reader-friendly content in various banking, personal finance, loans, insurance, and investment-related topics.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
There is no minimum CIBIL score applicable for a debt consolidation loan. Lenders will have their own set Handling different loans with different interest rates, EMIs and due dates might be confusing. A debt consolidation loan will allow you to consolidate eligible outstanding amounts into one repayment. Choosing the incorrect loan can actually cost you more.
Key Takeaways:
Before opting for debt consolidation, it’s always a good idea to compare the terms and conditions provided by various banks and NBFCs. This allows you to see what the best loan is for your repayment ability.
Considering these factors can help you choose a loan that suits your financial needs and offers repayment terms you can comfortably manage.
Depending on the amounts owed, interest rates and ability to repay, there are a variety of options available to people in India looking to consolidate their debt. Two popular options include personal loans and balance transfer credit cards.
Taking out a personal loan can help you clear your debts. Most personal loans are unsecured, so you will have nothing to pledge. Personal loans can also provide a lower rate of interest compared to high-interest credit cards or short-term loans, depending on your credit status and lender.
If you have a number of credit cards with outstanding balances, you can consider moving eligible amounts onto a credit card with a lower introductory interest rate. Some banks offer credit card balance transfer facilities, subject to their eligibility criteria and applicable terms.
Look at the interest rates, fees and repayment options of both options to ensure you can reduce the amount you are paying to borrow and make repayments easier.
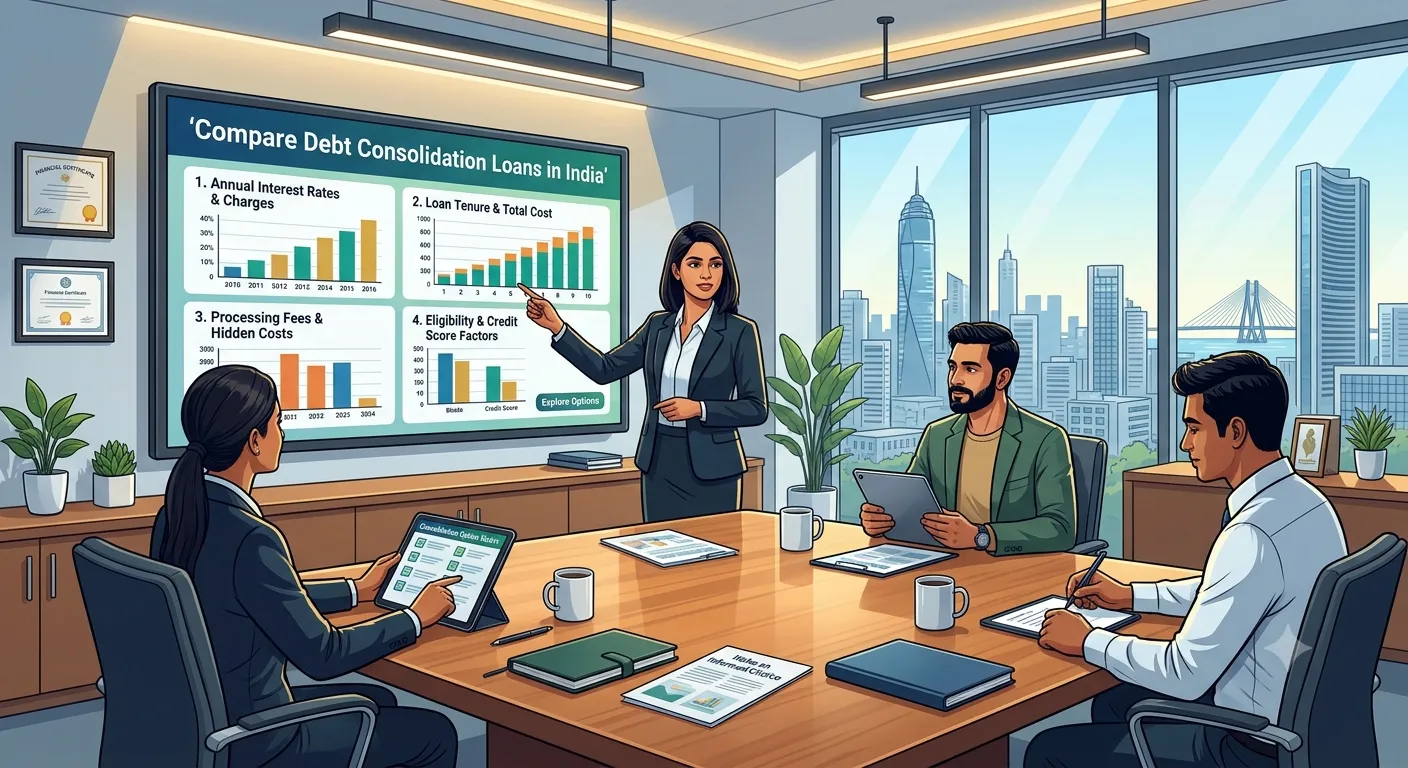
Several banks in India provide personal loans that you can use to consolidate your debts. The table below shows a comparison of interest rates and processing fees:
Compare the lenders based on the interest rate, processing fee and overall amount that you will need to repay. Here, LoansJagat can help you out by providing guidance and comparing various options available for consolidation. Our professional team will lay out the best options available for you as per your requirements.
Note: The above information is general in nature. Actual rates, amounts borrowed, term and fees will depend on the lending institution's lending criteria and your loan eligibility. For the most current terms and conditions, please contact your relevant lending institution.
Debt consolidation has an impact on your CIBIL score, but it is both positive and negative depending on how you handle your new loan and repayments.
Applying for a new loan may affect your credit score because the lender makes a hard inquiry on your credit report. However, the impact depends on your existing credit history and overall credit profile.
Paying off existing debts and ensuring your EMIs are paid on time will improve your repayment history; however, you won’t improve your score by closing multiple loan accounts.
Your credit card dues may decrease, so your credit utilisation rate is less. You can create a healthy credit profile by consistently repaying and handling your credit responsibly.
Debt consolidation does not necessarily improve your CIBIL score immediately. You need to make sure that you pay your EMIs on time and also avoid taking unnecessary loans. This will help you build a good credit profile and manage your credit wisely.
A debt consolidation loan can make repaying multiple debts easier. You should only apply if it is affordable.
A debt consolidation loan can help you repay your debts. However, you should ensure that you compare the cost of borrowing and repayment to ensure you do not increase your current debt.
A debt consolidation loan can help you to easily pay off your debts by consolidating your outstanding debts into one loan. This can help to make your finances manageable, keep your monthly payments on track and improve your financial wellbeing.
Overall debt consolidation can help to put your finances in order. Prior to taking out a loan, check the interest rates, fees and terms of repayment to ensure that it will fit within your budget and won’t cost you any more money.
Debt consolidation can give you a clearer way to pay back your debts. Before applying for one of these loans, compare lenders and understand how much you will actually be borrowing. Think about your income and current debts to ensure that you are getting the loan, which will make your financial situation easier to manage. You should avoid getting into further debt and ensure that you’re not putting yourself under any unnecessary pressure.
Yes, based on the terms and conditions and loan amount that the lenders provide, you can repay multiple personal loans and credit card dues using a personal loan.
No, debt consolidation does not automatically lower the principal amount owed. Instead, it replaces multiple debts with a new loan, which may have a different interest rate.
Yes, applying for a new loan may cause a small drop in your score, as there will be a hard inquiry. However, timely repayment can help.
of criteria based on your income, credit history and current financial liabilities.
This will depend on what you are looking to consolidate and repay. Personal loans can be used to consolidate a variety of eligible debts, whereas balance transfers are usually associated with credit card dues.
Yes, however, lenders will want to know your current income, any outstanding liabilities and repayment history to determine if you can manage an additional loan.
Usually banks and NBFCs ask for your PAN card, proof of identity, proof of address, salary slips/income proof, bank statements and loan details.
No, this will depend on the interest rate, loan amount and repayment period. The longer the repayment period, the lower your monthly repayments may be; however, your overall interest costs will be higher.
Apply for debt consolidation loans if you have a lot of high-interest loans, have trouble managing your EMIs and need to streamline your payments. Also ensure that the terms for this loan are affordable.
Yes, many NBFCs offer personal loans which you can use for consolidating your debts. However, ensure that you compare their interest rates, processing charges, eligibility and repayment terms.
Start your journey today
Apply Now*T&C apply