Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Anishka Bhadly is a content writer with a finance and business background. She has completed her bachelor's degree with a specialisation in finance and is currently pursuing an MBA in the finance field too. The knowledge she has gained from her studies and experience working with EdTech companies helped her combine theoretical knowledge with practical industry insight. Her expertise lies in creating well-researched, informative, and reader-friendly content in various banking, personal finance, loans, insurance, and investment-related topics.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
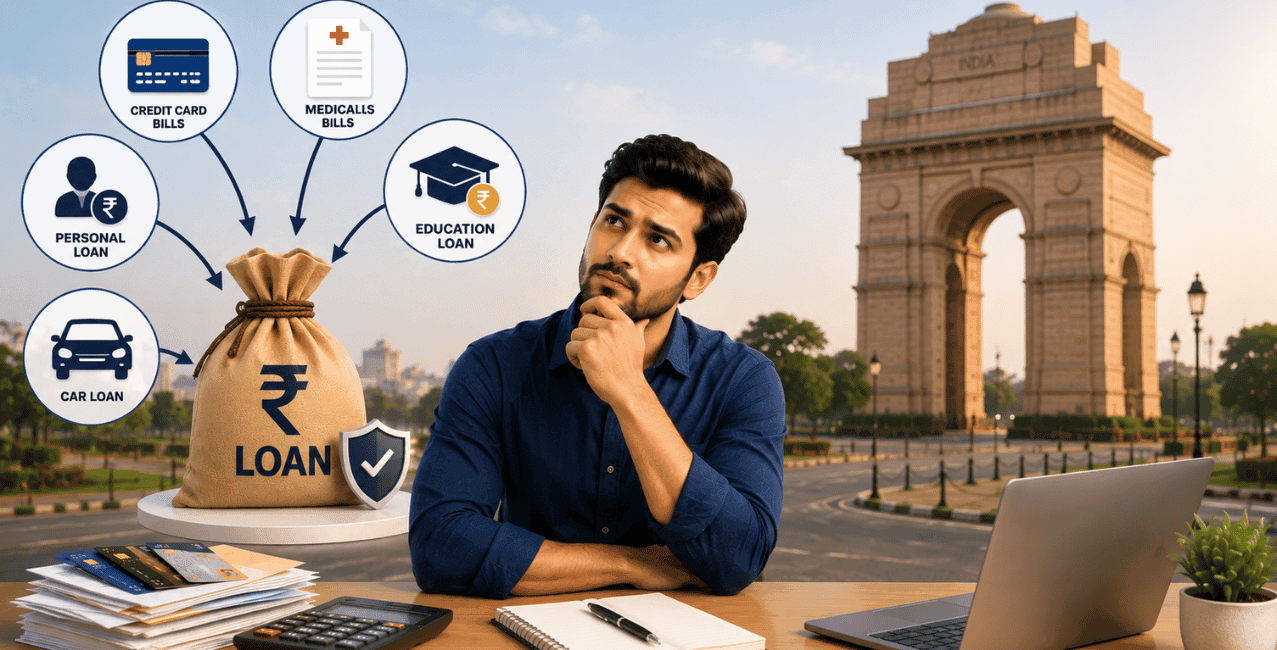
When you have multiple loans in place with various EMIs, interest rates and due dates this can get confusing. A loan consolidation can be helpful in reducing the complexity of paying off multiple debts. By consolidating your debts into one loan you will pay one EMI to pay off your debt. This can help manage your finances each month and may save you money on borrowing. Depending on the interest rate and fees of the new loan, you will understand how a loan consolidation works to help decide if this is the right option for you.
Key Takeaways:
Loan consolidation allows you to consolidate all your outstanding loans into one, with the approved loan amount going toward clearing your outstanding loans and credit card dues. It helps you to pay just one EMI.
Here is how loan consolidation works:
For instance, if you were currently paying a total EMI of ₹20,000, you might reduce your EMI to ₹15,000 with a consolidation loan.
Overall, you should also compare the total cost of paying it back and ensure that you are saving overall. A lower EMI doesn’t necessarily mean you’ll be saving.
Consider loan consolidation when you have several repayments to manage and a new loan offers an affordable EMI, lower overall borrowing costs, or both. For personal loan consolidation, compare the remaining payments on your existing loans with the total repayments and applicable charges on the proposed loan. A longer repayment term can reduce your monthly EMI while increasing the interest you pay overall. If your priority is immediate budget relief, calculate that extra cost before accepting the offer and avoid taking on fresh debt after clearing the old balances.
Managing multiple loans and credit card payments can be stressful for your monthly budget. Taking out a debt consolidation loan can help you make your repayments more manageable. You may want to consider taking out a debt consolidation loan if:
Consolidating debt can help if you have large amounts of salary going to EMIs and credit card repayments. You can lower your total monthly repayments by taking out a good loan to consolidate your debt.
Debt consolidation can help streamline your finances, but it might not be suitable for everyone, so you want to think about how much you can afford to pay back.
Personal loan consolidation means taking out one new loan to repay several existing personal loans, leaving you with one EMI and one repayment schedule. A personal loan used for debt consolidation may also cover eligible credit card balances, depending on the lender’s terms. Start by checking the closure amount for each debt and whether the new loan will cover the combined balance. Approval depends on the lender’s assessment of your income, credit profile and repayment capacity; combining debts does not automatically qualify you for a lower interest rate.
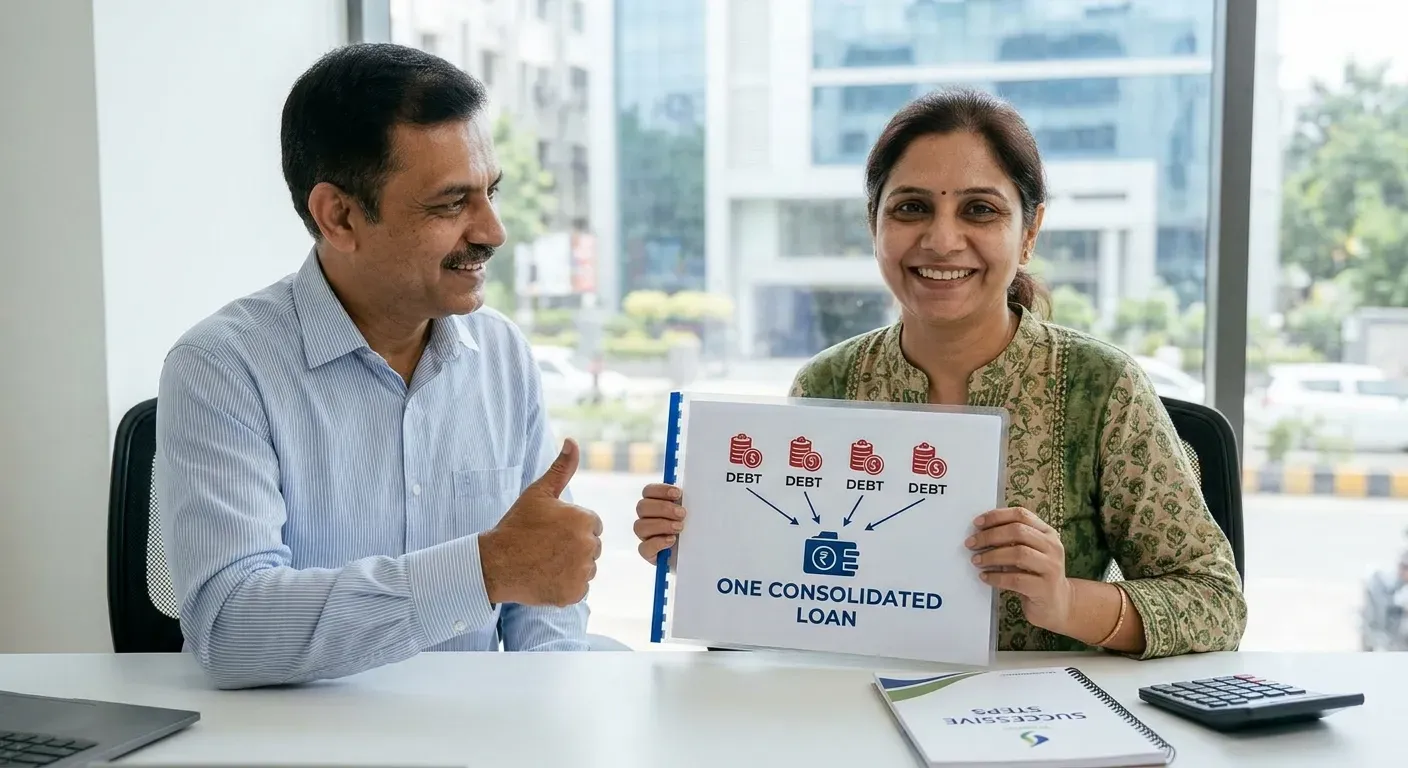
There are various ways to consolidate debt. Depending on how much debt you have, your ability to repay, and your eligibility, you can look at the following options below.
This is an unsecured loan which can be used to pay off several debts you owe. You will know the repayment tenure and applicable interest rate before accepting the loan. This can help you estimate your monthly EMIs and plan your budget accordingly.
Advantages:
Best for: People wanting to consolidate multiple high-interest loans and credit card payments.
This allows you to transfer your current debt onto another credit card. Some providers will offer a low rate of interest for a period of time.
Advantages:
Best for: People who are able to pay back the balance transferred within the promotional period.
If you own a property, you can take out a loan secured against your property. This can be used to pay off existing debts.
Advantages:
Best for: Those with large amounts of debt who are aware of the risks involved with taking out a secured loan.
Each option will come with its own costs and risks. You should compare the interest rates, fees, payment plans and security required to find the best way to consolidate your debt.
Debt consolidation can make paying off multiple debts easier and potentially has some additional financial benefits.
Overall debt consolidation can give you a simpler way to pay off your debt. However, it depends on the interest rate, loan term, fees and how disciplined you are.
Loan consolidation can help you manage your debt by merging multiple outstanding amounts into one loan. Below, we have outlined the difference between managing your debt with and without loan consolidation using LoansJagat:
If you can consolidate several loans together, it can make repaying them easier, as you will only have one payment to make each month. Depending on the terms and fees of the loan, you could save money on your monthly payments.
Applying through LoansJagat can make it much easier to look at your debt consolidation options. Here are some features:
You can apply once and receive loan offers from over 50 banks and NBFCs.
You can choose to take out a loan up to ₹50 lakh if eligible to consolidate your personal loans, credit card dues, and other eligible debts.
Choose between 2-7 years to pay off your debt.
If eligible, you can choose from loans with low interest rates from 9.99% p.a. Make sure to compare how much you’ll have to pay back in total.
You can consolidate up to 10 eligible personal loans, short-term loans, and credit card dues.
You can quickly see if you are eligible within a couple of minutes. If you decide to go ahead with your application, they may request further documentation and information to verify your application before approving and paying out your loan.
LoansJagat allows you to easily compare your debt consolidation options. You can compare your interest rate, fees, and repayment terms to find a loan that fits your budget.
Choose a consolidation loan by comparing the total amount you will pay from today, not just the advertised rate or EMI. Request closure quotes for your existing loans, then check the proposed loan’s repayment schedule, processing fee, applicable taxes and any other charges. Include any applicable foreclosure costs on the old loans, and count each cost only once if it is financed through the new loan. Confirm that the amount available after deductions will cover the debts you intend to clear, and select a repayment term your monthly budget can support.
The best consolidation loan for you will depend on your current debt situation and how much you can afford to repay. Find the right loan to help you consolidate your debts.
Getting the right debt consolidation loan can help you get on top of your debts. Take your time to get to know your options.
Debt consolidation is convenient as it gives a single loan that can be used to clear multiple debts. However, the EMI might be low but it does not necessarily mean that the total cost will be less. When looking at loans, consider the interest rate, service charge, repayment period and foreclosure charges. At LoansJagat, you can look at the various loan options available from different lenders. Ensure that you choose an option that is within your monthly budget and that the overall cost of repayment will be manageable.
Loan consolidation can have an impact on your CIBIL score depending on how well you manage your new loan. Applying for a new loan can lead to a hard inquiry, and timely repayment of your EMIs can help maintain a healthy credit profile.
Yes, while loan consolidation can be considered part of debt consolidation, in that they both involve consolidating multiple debts into one payment. The term 'debt consolidation' is a more general term and can include various types of loans and credit card payments.
You apply for a new loan; once it has been approved, you use that money to pay off any qualifying debts you have. Once this has been done, you will repay the new lender in one EMI.
Typically, personal loans, balance transfer credit cards and home equity loans are used. It depends on the debts you have outstanding and your financial situation.
You may save on what you have to pay each month; however, the interest could be higher due to the longer term of the new loan.
You may have a hard inquiry when you apply for the new loan. This could impact your credit score. Your credit score will also be impacted depending on how you pay back your loans. This will depend on how the information is shared with the lenders.
Yes, you can utilise an authorised personal loan to pay off your eligible credit card debts. However, make sure that you look at the interest rates, charges, and repayment periods.
Personal loans and balance transfer credit cards usually do not require you to provide collateral. However, you will need to provide collateral for a home equity loan.
LoansJagat offers debt consolidation loan options of up to ₹50 lakh, subject to the lender's eligibility criteria and approval.
Look at the interest rates, processing fee, repayment period, and foreclosure charges. Make sure that you think about how much you will be paying back overall.
Start your journey today
Apply Now*T&C apply