By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
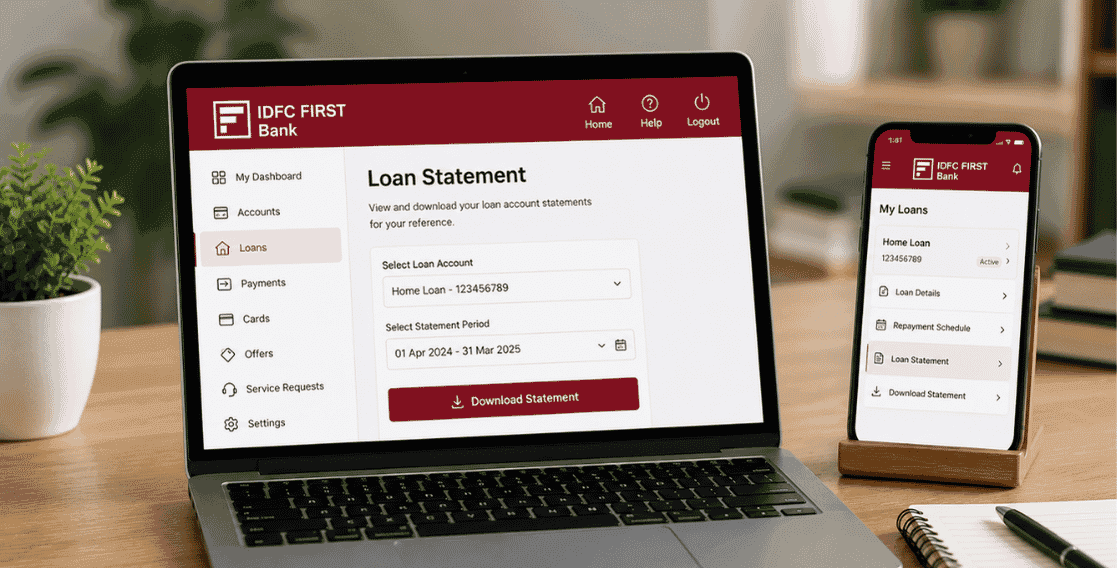
The IDFC FIRST Bank loan statement is one of the essential statements that help you know everything about your loan account, like repayment details, EMI details, interest rate, and amount left to pay. You get the details of the loan account with the help of the loan statement. Though you have all the details related to repayment in the loan statement, the loan account statement just gives you a brief view of your account. Understanding the loan statement and the method to check it will assist you in analysing the repayment and also help in taking decisions on whether to prepay the loan or not.
Key Takeaways
The IDFC FIRST Bank Loan Statement is an official document which provides detailed information regarding the loan account and repayments of the borrowers. It is very helpful for borrowers to manage their loan accounts and keep themselves updated with the latest status.
An IDFC FIRST Bank Loan Statement provides essential details about your loan account and repayment status.
Loan closure or prepayment information
Details related to prepayment, foreclosure, or loan closure
These details are very important because reviewing them helps borrowers to monitor their payments and deal with loan obligations efficiently.
Read Also: What is the IDFC First Bank Minimum Balance?
The procedure to get the loan statement for your account through the IDFC FIRST Bank Net Banking portal is as follows:
Loan tenure and interest rate
*T&C Apply
Following these steps, you can easily access and download your loan statement.
One such tool which helps borrowers understand the terms and amount of the loan, repayment period, EMI, interest and balance is the IDFC FIRST Bank Loan Statement. Regularly reviewing such statements will help in making the necessary plans for paying back the loan.
You should consider looking at your loan statement on a regular basis, especially following any big repayments. This can help you spot any errors or unusual charges on time.
Customers can request a physical Statement of Account through the bank. Applicable charges may apply depending on the loan type.
The loan statement can be used as a financial document to examine any interest payments or tax rebates applicable to you, depending on the kind of loan you have taken.
You should contact the bank through its official customer support channel. It is better that you have all the information on hand related to the payments you have made.
Yes, as it could help show your ongoing liabilities and give lenders an idea regarding your loan liabilities.
Depending on the loan and statement type, applicable fees or other charges may be reflected in the loan account. This will give you an idea regarding the charges applicable on your loan account.
A loan statement mainly documents the account activities and repayments during a given period. On the other hand, a foreclosure statement mainly notes the amount needed to close your loan account before its maturity date.
Yes, it could be used as proof of your loan repayment, but for formal purposes, you would require a particular repayment certificate or any other document from the concerned party.
Firstly, it is to be checked whether or not the payment made was successful from your bank account or your payment mode. If the payment has been made but it still appears to be missing, contact the bank regarding the details of the transaction.
Yes, the borrowers can obtain loan account statements from banks even after complete repayment of the loan.