By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
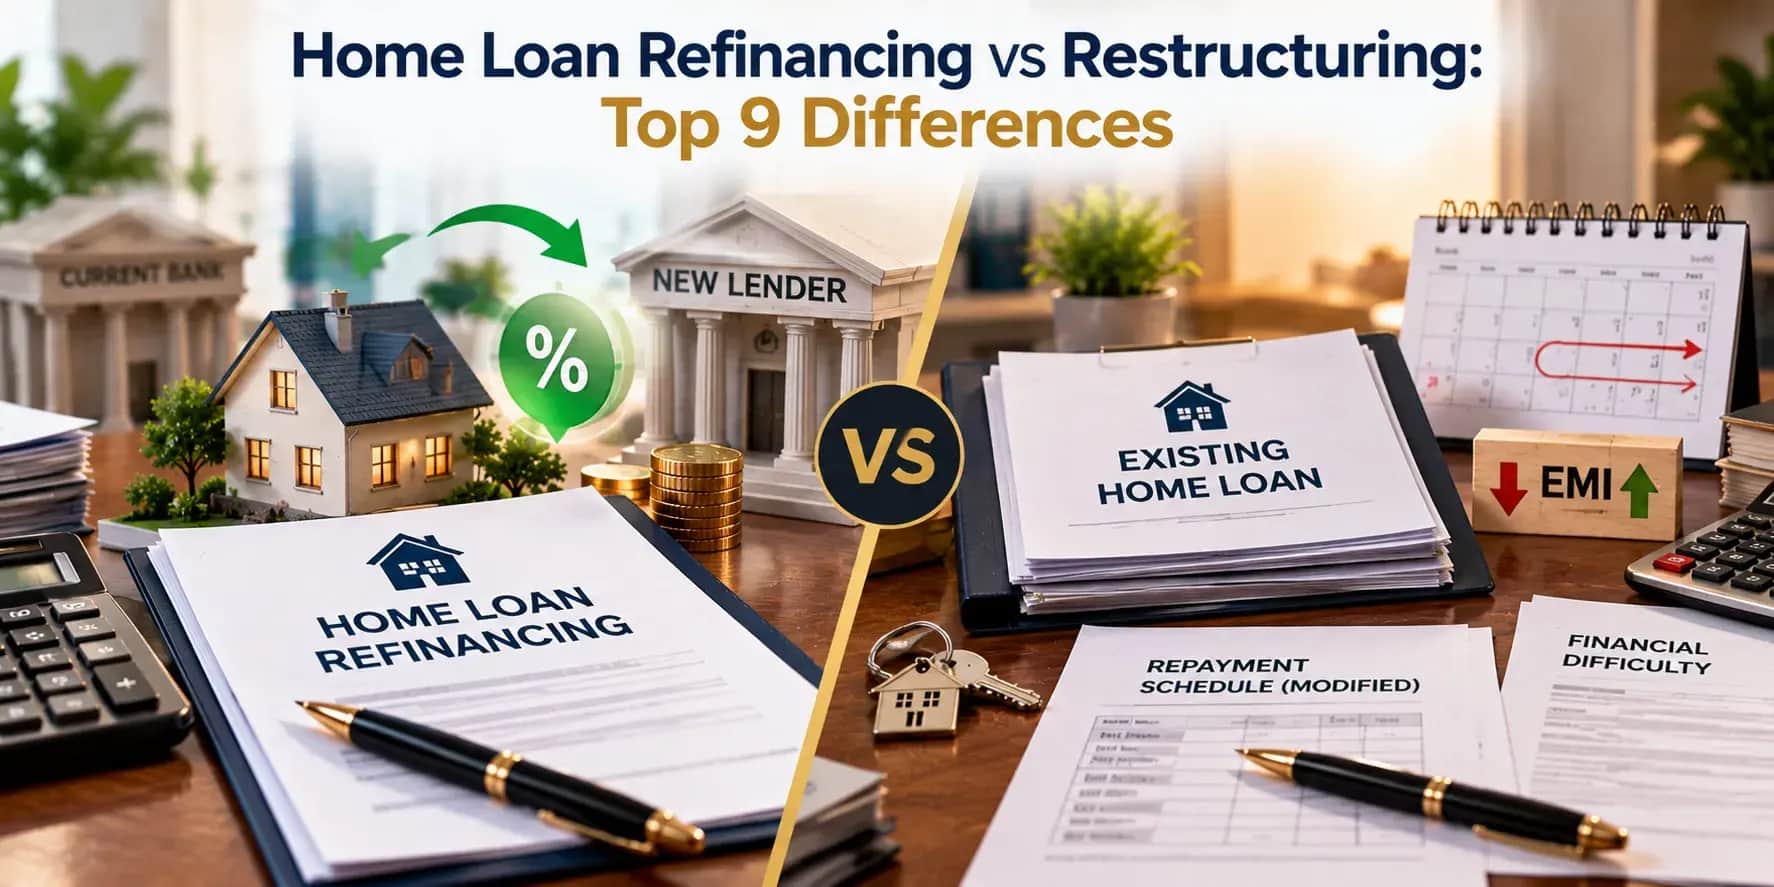
Home loan refinancing and home loan restructuring are two distinct processes to change a pre-existing home loan. The former process involves substituting the old home loan with a new one, with different interest rates, tenure, or repayment terms. The latter process involves changing the conditions of the pre-existing home loan to facilitate its repayment, especially in cases of difficulty.
As you can see from above, the major difference between these two processes is that refinancing involves a new home loan, whereas restructuring involves an existing one. In order to be able to compare both options in terms of interest rate, EMIs, loan tenure, expenses, eligibility, and the effects on your credit profile, it is important to understand the top 9 differences between home loan refinancing and restructuring.
Refinancing a home loan means taking a new home loan and replacing the old home loan with it. The new loan may have different interest rates, repayment periods, and other terms.
People generally think of refinancing when they are able to secure lower interest rates or reduced monthly payments, or if the terms of the loan better meet their needs. It is also possible for the homeowner to transfer the balance of their home loan from one lender to another through refinancing.
This can happen in cases where the existing home loan carries a higher interest rate, and other lenders offer a lower interest rate.
Home loan restructuring refers to altering the terms of an existing home loan in order to facilitate repayment. Refinancing is not involved in home loan restructuring since the process does not usually result in the replacement of an existing home loan.
This process might be recommended if the borrower is facing financial problems and is struggling to pay off his or her existing repayment plan. This might include extending the term of the loan, among other changes, depending on the borrower's and the lender's situation.
The process and availability of restructuring depend on the borrower and the lender.
The distinction between the two primarily lies in whether the borrower replaces the existing loan or modifies its existing terms. Axis Bank similarly describes refinancing as obtaining a new loan with different terms and restructuring as modifying the terms of the existing loan.
The first key difference is that of how the loan is dealt with in both cases.
In refinancing, a new loan replaces the previous home loan that is in existence. This could be through changing the interest rate and repayment period.
Restructuring deals with the modification of the terms of the current loan; the existing lender is retained in the process.
The motive for opting for either of the two options could be different as well.
For example, refinancing could be opted for if the borrower is interested in getting favorable loan conditions. It could be a situation where the borrower looks at refinancing due to having been offered a better interest rate by another lending institution.
On the other hand, restructuring could arise out of problems in meeting repayments on the loan.
Refinancing involves the existing home loan being paid off by the funds received from the new loan. The debtor then begins paying off the new loan in accordance with its terms.
Restructuring involves retaining the existing home loan while modifying certain terms depending on the borrower’s situation.
A refinancing application is subject to the lender’s eligibility and underwriting criteria, which the borrower must meet for the new loan to be approved. Restructuring does not typically lead to a new loan. In restructuring, an adjustment is made to the existing loan.
In cases where the refinancing takes place, there may be a change in the lender. The borrower may also consider the various options related to refinancing offered by the current lender.
In restructuring, there is an interaction between the lender who is holding the home loan and the borrower. The borrower approaches the lender with information regarding the financial problems and seeks new terms of repayment.
Interest rate is yet another significant aspect of the difference.
In case of refinancing, the borrower might try to obtain an interest rate that is more favourable than before. Whether or not there will be any advantage would depend on the new interest rate, amount of loan outstanding, duration of loan tenure, and other associated costs.
*T&C Apply
As regards the interest rate reduction, there is no certainty of the same in case of restructuring. Other aspects of the repayment schedule might be changed instead.
Both can influence the loan duration, although for different reasons.
In the case of loan refinancing, the loan duration can be either increased or decreased, based on how the borrower wants to pay off the debt.
However, in the case of loan restructuring, the lender may modify the loan terms to address the borrower’s financial circumstances. This may include extending the loan tenure, depending on the restructuring arrangement.
The effect of the process on the credit profile of the individual would vary depending upon the situation.
In case of refinancing, there would be a process of applying for a fresh loan, which could result in a credit inquiry. A fresh loan would become part of the credit history of the individual, depending upon repayment behavior after that.
Restructuring of debt could have an adverse impact on the credit profile of the individual if it has been done due to financial problems faced by the individual. The impact of loan restructuring or refinancing on a borrower’s credit score can vary depending on the circumstances and how the loan is reported to credit bureaus. Restructuring may affect credit history where it involves changes such as overdue payments or settlement, while timely repayments on a refinanced loan may contribute to maintaining or improving the borrower’s credit profile over time. Therefore, neither restructuring nor refinancing should be described as automatically reducing or improving the credit score.
The procedures for the refinancing and restructuring processes are also different from each other.
In the case of refinancing, the borrower compares the lenders, evaluates the interest rates and other fees, meets the qualifications of the new lender, provides the necessary paperwork and follows the transfer process of the loan.
In the case of the restructuring process, the borrower needs to contact the current lender and tell him/her about the problem he/she is facing.
When comparing the two, the following parameters can be considered:
Lower EMI does not always translate into a lower cost of borrowing. The tenure of the loan being extended will result in a lower EMI but higher interest payable over the tenure of the loan.
Home loan refinancing and home loan restructuring meet the different needs of borrowers. While home loan refinancing involves replacing the existing loan with a new one, home loan restructuring entails altering the existing conditions of the loan to make it easier for the borrower to repay it. There are several factors that the borrower must consider before deciding.
The refinancing might be applicable for a residential property that fulfills the criteria of the lender. The property may need to meet certain criteria related to legality, valuation, documentation, location, and other factors, depending on the lender’s requirements and the specific refinance product.
Yes, if the refinance application is approved by the lender, which may be the existing lender or a different lender, depending on the refinancing arrangement. Every time the loan is refinanced, its impact needs to be weighed in terms of costs versus benefits.
The lender might consider the valuation of the property prior to giving a green light to the refinance.
Lenders may provide a loan product that allows one to use property-secured loans for financial purposes beyond the intended purpose. The requirement for documentation and use of money is subject to the lender's product terms.
Borrowers will be asked for identity and address proof, income proof, statement of current loans, property documents, and repayment history. There could be additional documentation required depending on the employment status of the borrower and the lender's analysis.
A new lender might require a property valuation when assessing creditworthiness and collateral security. It all depends on the procedure of the lender and the property details.
When the existing loan has been repaid in full, the original lender is expected to release all the pertinent property documents and issue the appropriate documents for closure. The borrower is supposed to ensure that all necessary documents and security formalities have been sorted out.
Refinancing will not lead to the automatic transfer of ownership of the property. Property ownership is another separate legal process.
Yes, a borrower can contact the current lender regarding the changed loan terms or other available loan options. It will depend on the policy of the lender and the terms of the deal.
The new lender can carry out legal and technical checks on the property before extending the loan.