By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vaishnavi kale
Vaishnavi is a Financial Content Writer at LoansJagat. She holds a B.Sc. and an M.Sc. She has experience in writing SEO-focused content across finance, digital marketing, education, and Ayurveda. Before joining LoansJagat, she worked with digital marketing agencies serving fintech clients and quick-commerce brands like Zepto and blinkit. At LoansJagat, Vaishnavi writes on banking, loans, personal finance, and insurance. Her work involves researching financial topics, understanding user search intent, and creating content that is clear and accurate. She has experience in SEO content writing, keyword research, content optimisation, and AEO. She enjoys simplifying complex topics into practical information that readers can easily understand and use. She believes that well-researched and reliable content plays an important role in helping people make informed financial decisions.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
Home loan amounts don't cover the total cost of the property, and borrowers also need to pay for other expenses like interiors and furniture. Sometimes emergencies may arise. In this situation, they need extra money. To spend on these things, one can take a personal loan. It is legally possible to get a personal loan and a home loan simultaneously in India. Borrowers can apply for both loans, but the final approval comes from the lender. Let's understand it in detail.
Key takeaways
One can definitely take a personal loan and a home loan together. In India, a person can get multiple loans at a time; there is no restriction on it. That's why getting a personal loan and a home loan together is entirely permissible. But you need to understand that you can only apply for the loan; whether you will get it or not is totally dependent on the lender's assessment.
Sometimes the borrower needs more money after getting the home loan amount . That's why people need more money.
For down payment
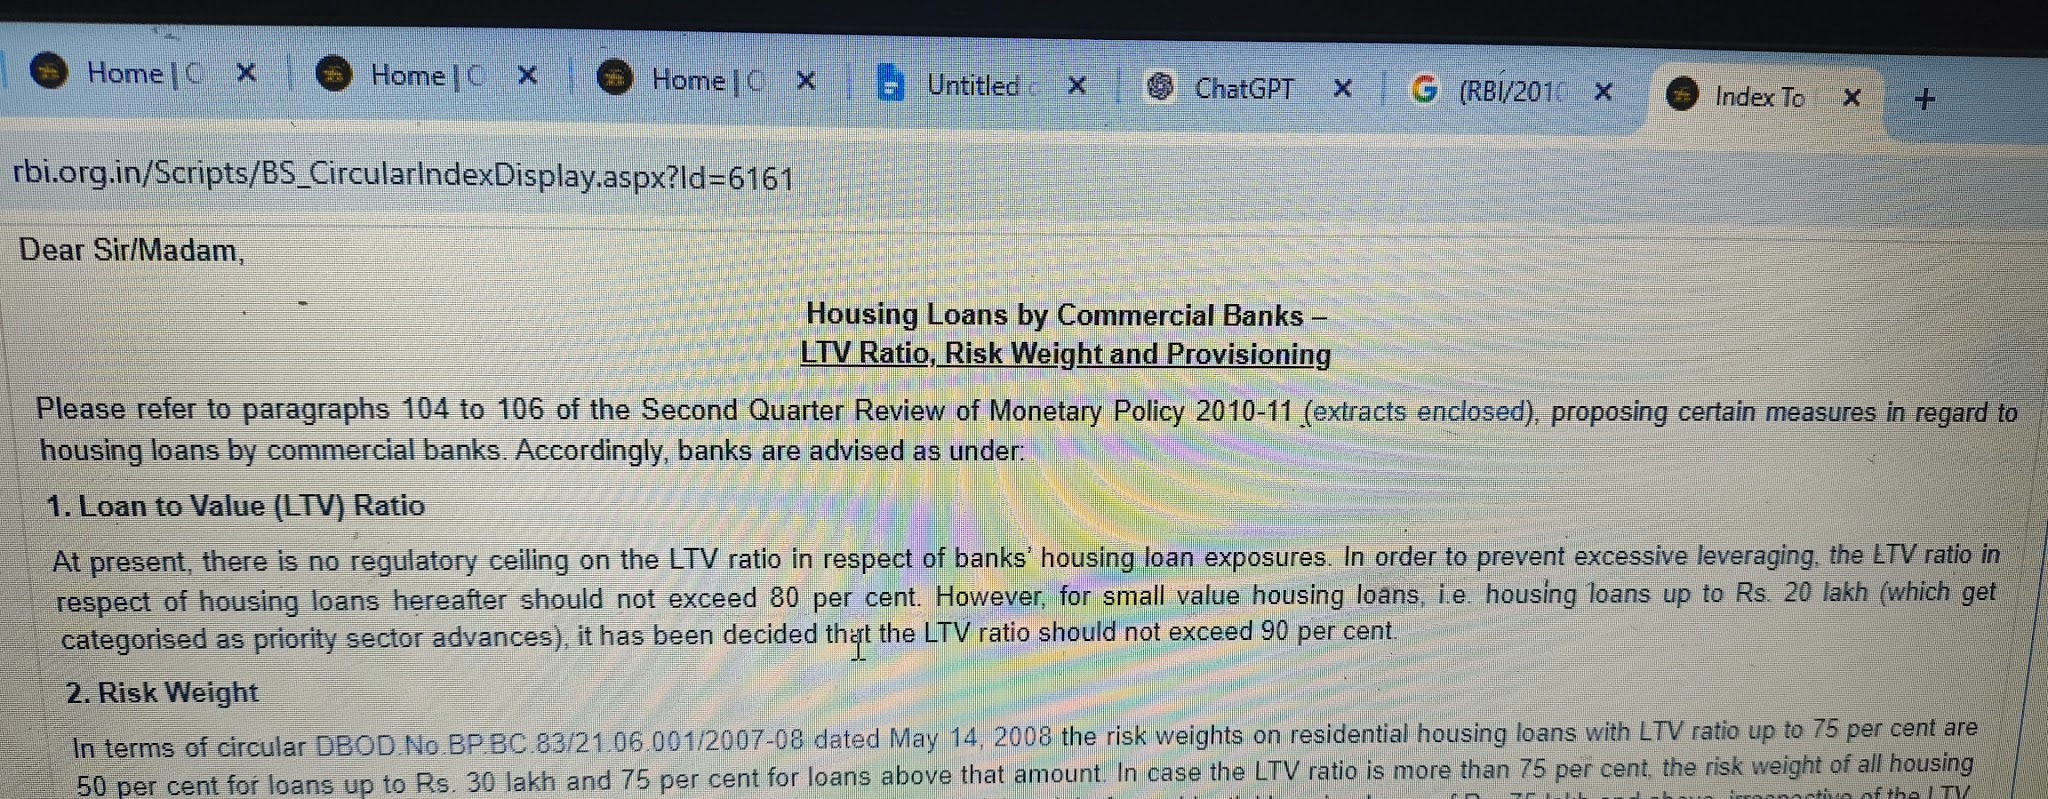
Banks do not provide a 100% amount of home value. Banks provide this money with RBI-linked LTV (Loan-to-Value) norms. According to the RBI circular, the LTV ratio for housing loans should not exceed 80%. For housing loans up to ₹20 lakh, the LTV ratio should not exceed 90%.
Handling cost
The home loan amount doesn't cover stamp duty, registration charges, or interior costs; you have to pay for them. These additional expenses may need to be arranged separately, subject to the lender’s terms and the borrower’s financial situation.
Home design
Just construction is not enough; we need a comfortable house to live in. For facilities like furniture, appliances, and minor repairs, money is important. A personal loan can cover this expense.
As mentioned before, getting a personal and home loan at the same time is possible, but the approval depends on the lender. Lenders evaluate whether the borrower can pay both EMIs on time or not.
FOIR (Fixed obligation to income ratio)
FOIR is an important factor. It is calculated as total loans and EMIs plus other fixed obligations divided by the net monthly income of the borrower. Lenders prefer the 40% to 55% range.
Credit score
A good credit score improves chances of loan approval and a better interest rate. But the final decision depends on the lender. A weak credit score doesn't directly mean your loan application is rejected, but it can affect the loan amount and interest rate.
Income stability
Lenders also check the borrower's income and employment details. Lenders prefer individuals with stable income and employment.
If you already have a home loan, then getting a personal loan or vice versa does not directly affect your previous loan. But it affects your credit profile. When you get a new loan, an EMI is added, which increases the FOIR. If you apply for both loans around the same time, Lenders check both EMIs when checking your repayment capacity.
If you want extra money for other expenses, a personal loan is not the only option. Banks facilitate Borrowers to get a top-up on home loans so they do not have to apply for other loans.
Both the loans are useful and the choice depends on the borrower.
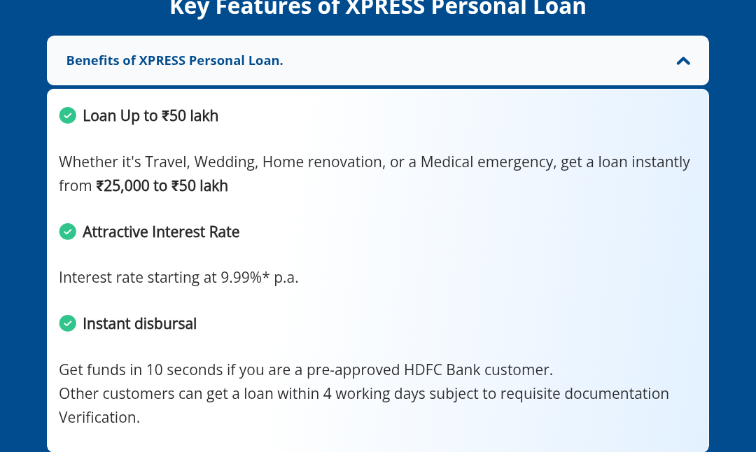
It is possible to get a personal loan and a home loan together. The need for both loans arises because the home loan alone does not cover the cost of the property. For stamp duty, furniture, and interior, people need more money; that is when they think about a personal loan. When borrowers get two loans at a time, it may become difficult to manage. To their benefit, the bank offers a home loan top-up; this fund covers other expenses. The choice of loan depends on the borrower, and the approval depends on the lender. Before applying for both loans, check credit history, FOIR, and avoid applying for both loans simultaneously.
You can apply for a home loan if you have an existing personal loan, but the approval depends on the lender's assessment. Lenders evaluate the credit history, income stability, and the existing EMI burden. If you have a positive credit history and high income to manage both the EMIs, the lender can consider the loan.
There is no legal limit on how many loans you can hold at once. In India, Borrowers can apply for multiple loans at a time, or they can have multiple loans at a time. But the approval depends on the lender's assessment.
There is no universally accepted FOIR for every lender. Normally, lenders adjust their FOIR based on various factors like income, credit score, and stability of income. Also, for banks and NBFCs, this limit can be different.
Getting a personal loan after a home loan doesn't directly affect the existing loan. But it can affect your financial situation. Personal loans may increase the EMI burden, Debt-to-Income (DTI) ratio, and future borrowing limits. So that people can go for a home loan top-up if they already have a home loan.
It is subject to the lender’s policies and eligibility criteria. Mortgage lenders may also consider the additional loan obligation when assessing your home-loan application.
It is not fixed but sometimes. Lenders check FOIR, credit profile, and the property and legal verification. Then decide whether to approve your loan or not.
This is a personal choice, and it depends on the borrower.
There is no fixed good CIBIL score that will guarantee loan approval. But you need to have a high CIBIL score to comfortably service two loans at the same time.
Sometimes Personal loans may have higher interest rates than some secured loans, while their shorter tenure can result in higher EMIs. In this situation you can consider paying this loan first but the decision depends on the interest rate and the amount of loan.
It may not affect your house but this can affect your overall financial health. Default may affect your credit profile, and banks may classify this loan as an NPA.