By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
A financial crunch can be unpredictable in life; it can occur at any time in people’s lives. In such situations, people mainly opt for a personal loan facilitated by several banks or fintech companies like LoansJagat by connecting them with the right lender. On the other hand, they choose top-up loan services from banks. Moreover, both of the loan types have their own features, eligibility, terms, and conditions, which vary from one lender to another.
Key takeaways:
A top-up loan refers to the process where the lender extends the principal amount of the borrower's existing active loan due to a financial crunch. For example, a home loan top-up or a personal loan top-up.
In India, multiple lenders provide this facility to people through a proper process and eligibility criteria. These criteria vary from one bank to another. In short, there is no standardised rule for people to get the top-up loan facility.
Here are the features of the top-up loan:
Hence, these are the features of the top-up loan provided by multiple lenders in India.
The eligibility for a top-up loan is different from one bank to another. Every bank follows its own requirements to provide the top-up loan facility.
Hence, these are the eligibility criteria provided by several banks to borrowers for different top-up loans.
A personal loan is provided to the borrower for multiple reasons, including debt consolidation, emergency funds, etc.
Multiple banks provide personal loans to the people with proper eligibility criteria. Moreover, there is no standard eligibility for all; it varies from one bank to another. There are multiple features provided by the personal loan, which may benefit the borrowers.
Hence, these are the major features of the personal loans provided by the different banks.
Every bank provides different eligibility criteria for a person to take personal loans. One needs to meet those criteria to get a personal loan.
Here are the eligibility criteria provided by lenders for personal loans:
*T&C Apply
Salaried applicants: A minimum monthly income of ₹30,000 and at least 2 years of total work experience are required.
Self-employed applicants: At least 2 years in the current business and 3 years or more of total work experience are required.
Hence, these are the eligibility criteria provided by the lender for the personal loan.
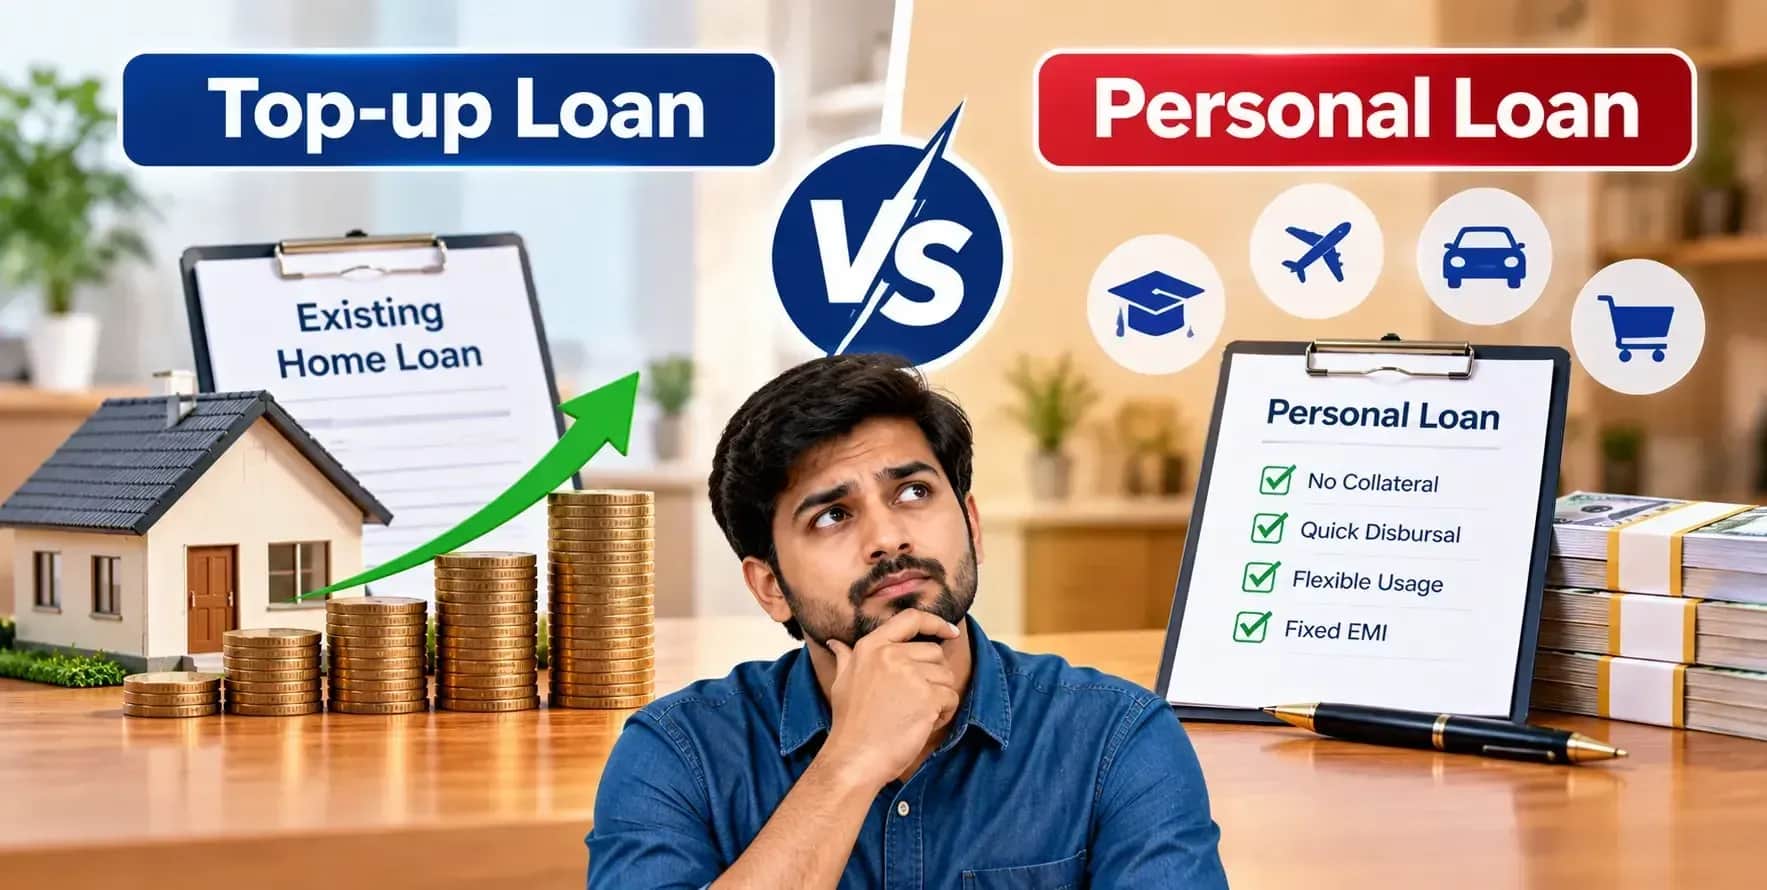
The top-up loan and personal loan provide the major difference when it comes to their functionality and nature.
Here are the differences between top-up loans and personal loans:
Hence, these are the differences between a top-up loan and a personal loan.
Choosing between a top-up loan and a personal loan depends mainly on your financial needs and your existing relationship with the lender.
If you already have a loan with a lender and have been making your payments on time, a top-up loan can be a convenient option. It may involve less paperwork and could also come with a lower interest rate, depending on the lender and the type of loan.
A fresh personal loan, however, gives you more freedom to compare different lenders and choose the terms that work for you. It is also a separate loan, so its repayment schedule does not depend on your existing loan.
In simple terms, a top-up loan can be useful when you want to borrow more from your current lender, while a personal loan can be considered when you want to explore offers from different lenders for your financial needs.
A top-up loan helps borrowers during a financial crisis by extending the principal amount of the existing loan. This can be done on your home loan, personal loan, etc. Whereas a personal loan is provided to the borrower when they need funds for debt consolidation, emergencies, etc., each of these methods has several differences in terms of requirements, eligibility, etc. Moreover, these vary from one lender to another.
Top-up loans and personal loans can reduce the financial burden on the borrower, according to their functions and features.
A top-up loan is a process where the principal amount of the existing loan is increased due to financial hardship.
A personal loan is provided by banks to the borrower for multiple reasons, like debt consolidation, emergency funds, multiple bill payments, etc.
No, the eligibility for top-up loans and personal loans is different from each other and can vary from lender to lender.
The process for top-up loans may be simpler than a personal loan because the lender may know you because of the existing loan you have. Whereas a personal loan is a completely fresh loan and needs hard verification for it.
This is completely dependent on the lender’s own terms and policies. For example, HDFC provides zero documentation for top-up loans, whereas ICICI Bank provides simpler documentation for top-up loans.
No, the eligibility criteria for personal loans are not the same for all the banks in India; in fact, they vary from one bank to another.
Yes, there is no limitation provided by the RBI for taking multiple personal loans.
The major advantage of a top-up loan is that it lowers financial stress by increasing the principal amount of the existing loan. Whereas the major con is that the person will be in debt for a longer period of time.
Several banks in India, like HDFC, provide housing top-up loans for borrowers.