
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
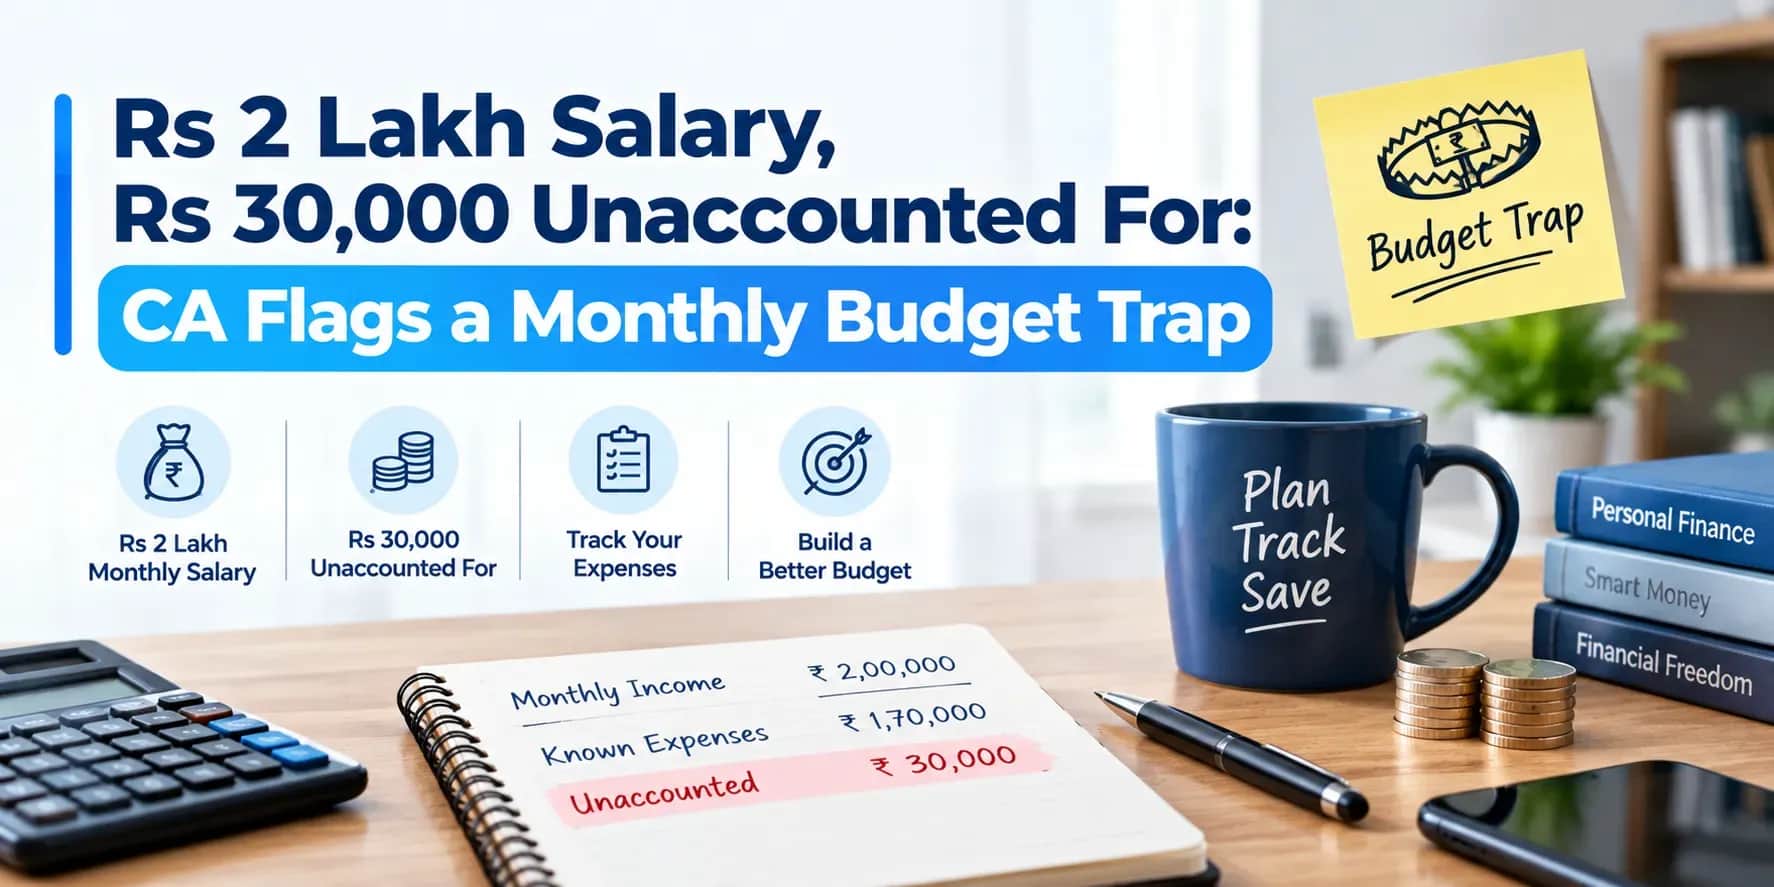
CA Nitin Kaushik flagged ₹30,000 unaccounted for in a ₹2 lakh monthly budget. He advised checking salary deductions and comparing spending records with actual payments.
Key Highlights
CA Nitin Kaushik’s budgeting example, shared on X and reported on 14 October 2026, leaves part of a monthly salary unexplained. His advice addresses a familiar budgeting problem: expenses that appear manageable individually can leave an earner unable to account for the full income.
For salaried households in India, bills due before the next payday leave little room for errors in the budget. Savings plans also become harder to maintain when the amount left each month is based on an incomplete spending record. However, a gap between salary and listed allocations does not establish that money has been wasted. Deductions and balances retained in accounts belong in the calculation too.
Money reserved for unpaid bills remains part of the bank balance until those payments go through. Treating the whole amount as available for purchases risks leaving those bills unfunded. Insurance premiums and debt payments belong in the expense record too, as the National Institute of Securities Markets explains in its guidance on managing income and expenses. These payments must be deducted from income to work out how much remains.
Household bills continue during a temporary break in income, when emergency savings may be needed to pay them. The institute distinguishes this money from investments set aside for future goals. Recording the purpose of each amount helps prevent funds reserved for later from being spent now.
The ₹2 lakh figure needs to be identified first: is it the salary before deductions or the amount received? Kaushik points out that tax and payroll deductions may account for the difference when the budget starts with gross income. His post on salary budgeting puts that question before any judgement about spending.
His next step compares planned expenditure with actual payments. The Securities and Exchange Board of India (SEBI)’s budgeting guidance supports this practical approach: gather bank statements, investment records and bills, then establish salary deductions and monthly expenses. A budget prepared from memory can be checked against those records.
The reported breakdown includes investments alongside spending and repayments. Its total therefore represents allocated money, rather than household consumption alone.
The “other expenditure” category needs further detail. Kaushik advises separating annual bills from unexpected expenses. An insurance renewal has a due date, allowing money to be reserved ahead of payment. An urgent repair may have to be paid from emergency savings.
The reading of the figures is that the unexplained balance should not be treated as capacity for another EMI. The listed expenses and investments already account for ₹1.7 lakh. Until the remaining amount is reconciled, a new repayment would be based on an assumed surplus.
There is also a difference between reducing an instalment and reducing borrowing costs. For the same principal and interest rate, extending repayment generally lowers the monthly EMI while increasing total interest. Both amounts can be compared using a personal loan EMI calculator, although the repayment agreed with the lender depends on its actual terms.
The record needs to show where income went and how much remains in the accounts. Cutting shopping expenses would leave a payroll deduction unexplained. Equally, earning more would not reveal a payment omitted from the record. Spending decisions need that distinction first.
It is the difference between the stated salary and the listed monthly allocations. It requires reconciliation before being classified as spending.
Take-home pay is the starting point for money available after payroll deductions. Using gross pay without accounting for deductions overstates the available amount.
This question appears in a public discussion about monthly saving. There is no percentage established by Kaushik’s example for every household. Essential payments, debt commitments and emergency reserves affect what remains available.
A separate public question asks how to divide that income. The starting point is actual take-home pay and recorded commitments. The National Institute of Securities Markets recommends establishing an emergency fund before investing towards medium- and long-term goals.
No. It may already be reserved for an approaching payment. Assigning that balance to its intended purpose prevents it from being counted again as available spending money.












