
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
Personal loan rates in October 2026 may look similar across banks, yet the amount charged to process the loan is not always the same. 22 lenders are compared, including their starting rates and fees
For this October 2026 review, the published loan rates and charges of 22 Indian banks and finance companies were checked on 10 October. A matching advertised rate does not guarantee a matching fee at disbursal.
A longer loan tenure brings down the monthly EMI, but you end up paying interest for additional months. There is also a processing charge at the start. The rate approved in the bank’s sanction letter may differ from the advertised rate. The repayment schedule will show the full amount payable until the final instalment. Use these figures when comparing loan offers.
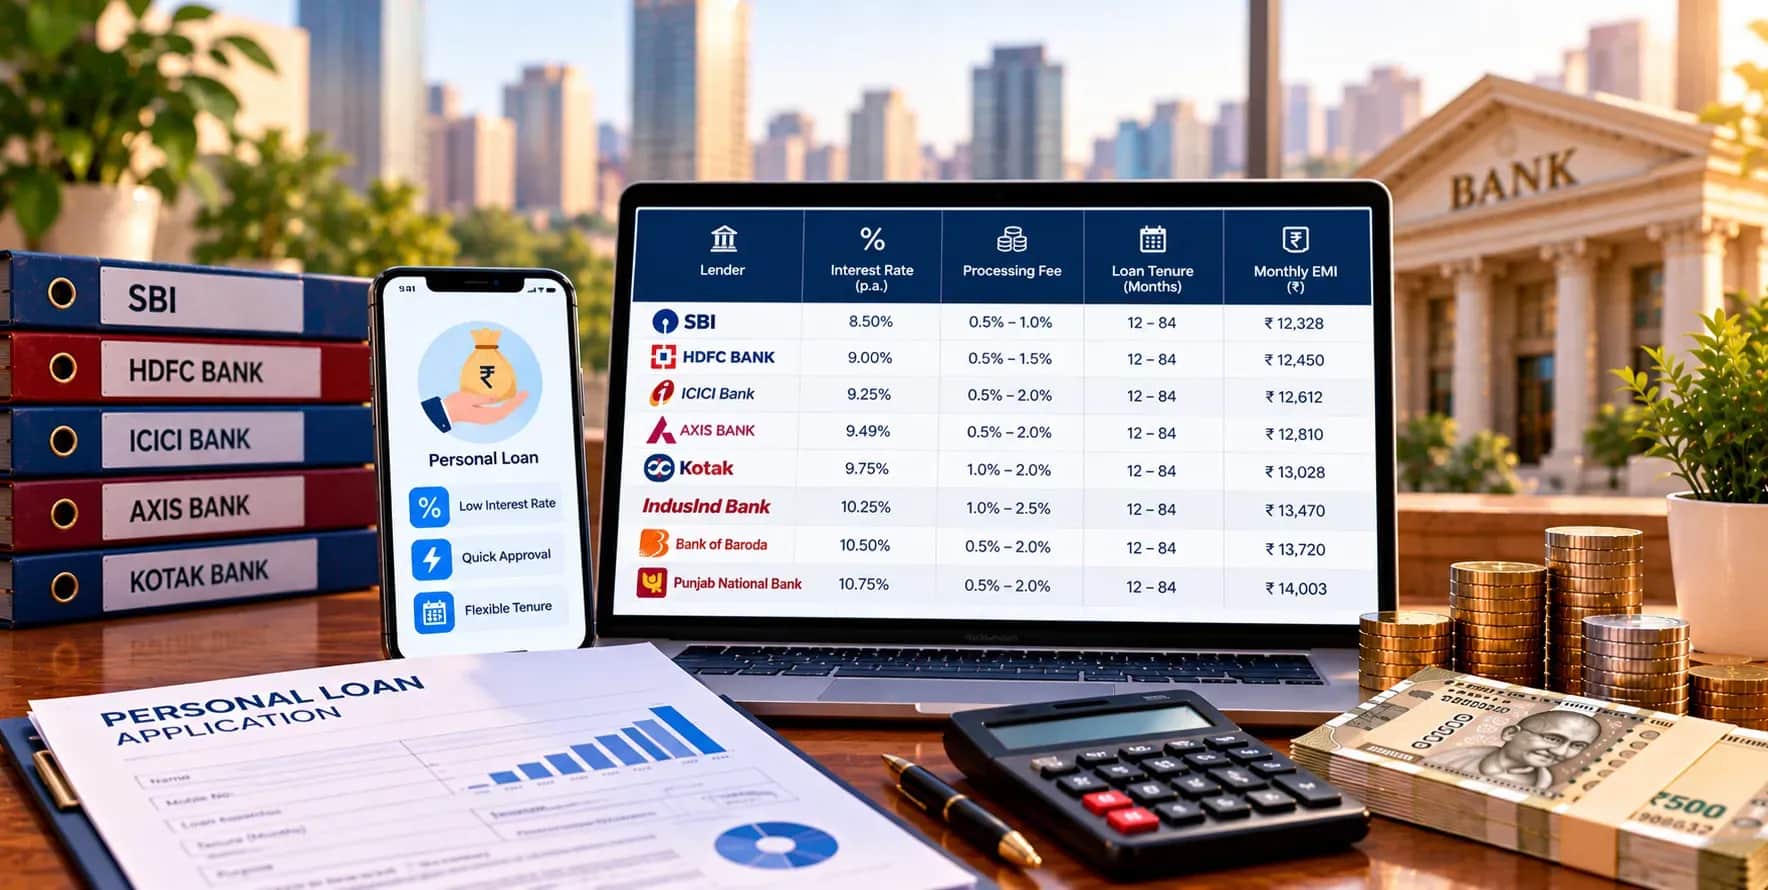
Here are the starting personal loan rates alongside the fees listed by each lender.
All interest rates listed are annual and depend on eligibility. The † symbol identifies entries from the comparison dated 7 October 2026. Figures for the other lenders come from their linked published schedules.
Processing fees above exclude applicable taxes unless stated otherwise. These are scheme-specific starting rates, rather than offers available to every applicant. Documentation charges and other contractual costs can apply separately.
HDFC Bank, ICICI Bank and Axis Bank all advertise 9.99% as a starting rate. If ₹5 lakh is borrowed for 60 months at that rate, the EMI comes to approximately ₹10,621. That figure excludes processing fees. The same inputs can be entered into an EMI calculator.
The difference appears in the upfront charges. HDFC Bank has a published processing fee limit of ₹6,500. Now take a lender charging 2% on the same ₹5 lakh loan. Its fee would be ₹10,000, which is ₹3,500 higher. Once 18% GST is added to both charges, the difference reaches ₹4,130.
These figures use the lenders’ published fee limits. Your final offer may carry a different charge. Central tax guidance exempts loan interest but treats service charges as taxable; the government tax schedule lists 18% for financial services.
Federal Bank advises applicants to “review the KFS for a detailed breakup of applicable fees and charges before availing the loan”.
The Key Facts Statement contains the charges applicable to the borrower’s loan offer. It allows the applicant to check the actual fees rather than relying on the amounts published in a general rate schedule.
ICICI Bank says its charges vary with the loan terms, borrower profile and prevailing policy. For anyone comparing these 22 lenders, the approved terms are therefore more useful than the lowest rate shown in an advertisement. EMI figures must also be calculated using the same loan amount and repayment period.
Canara Bank’s regular processing fee is 0.5% of the loan amount. The charge cannot be below ₹1,000 or exceed ₹5,000. Between 1 October and 31 December 2026, eligible borrowers receive a 50% waiver on this fee.
The October comparison shows that a 9.99% headline rate can accompany different upfront charges. Across these 22 lenders, the approved EMI, processing fee and total repayment together provide the basis for comparing actual offers.
At 9.99% over 60 months, the illustrative EMI is approximately ₹10,621. Processing charges are excluded.
No. HDFC Bank’s published salaried personal loan range extends from 9.99% to 24%; the approved rate depends on assessment.
HDFC Bank publishes a ceiling of ₹6,500 plus GST. Any concession needs confirmation in the bank’s final offer.
There is no shared threshold across all 3 banks and their schemes. Credit score alone does not establish eligibility for the advertised starting rate.
The published 50% processing fee waiver ends on 31 December 2026, subject to the scheme’s conditions.












