By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
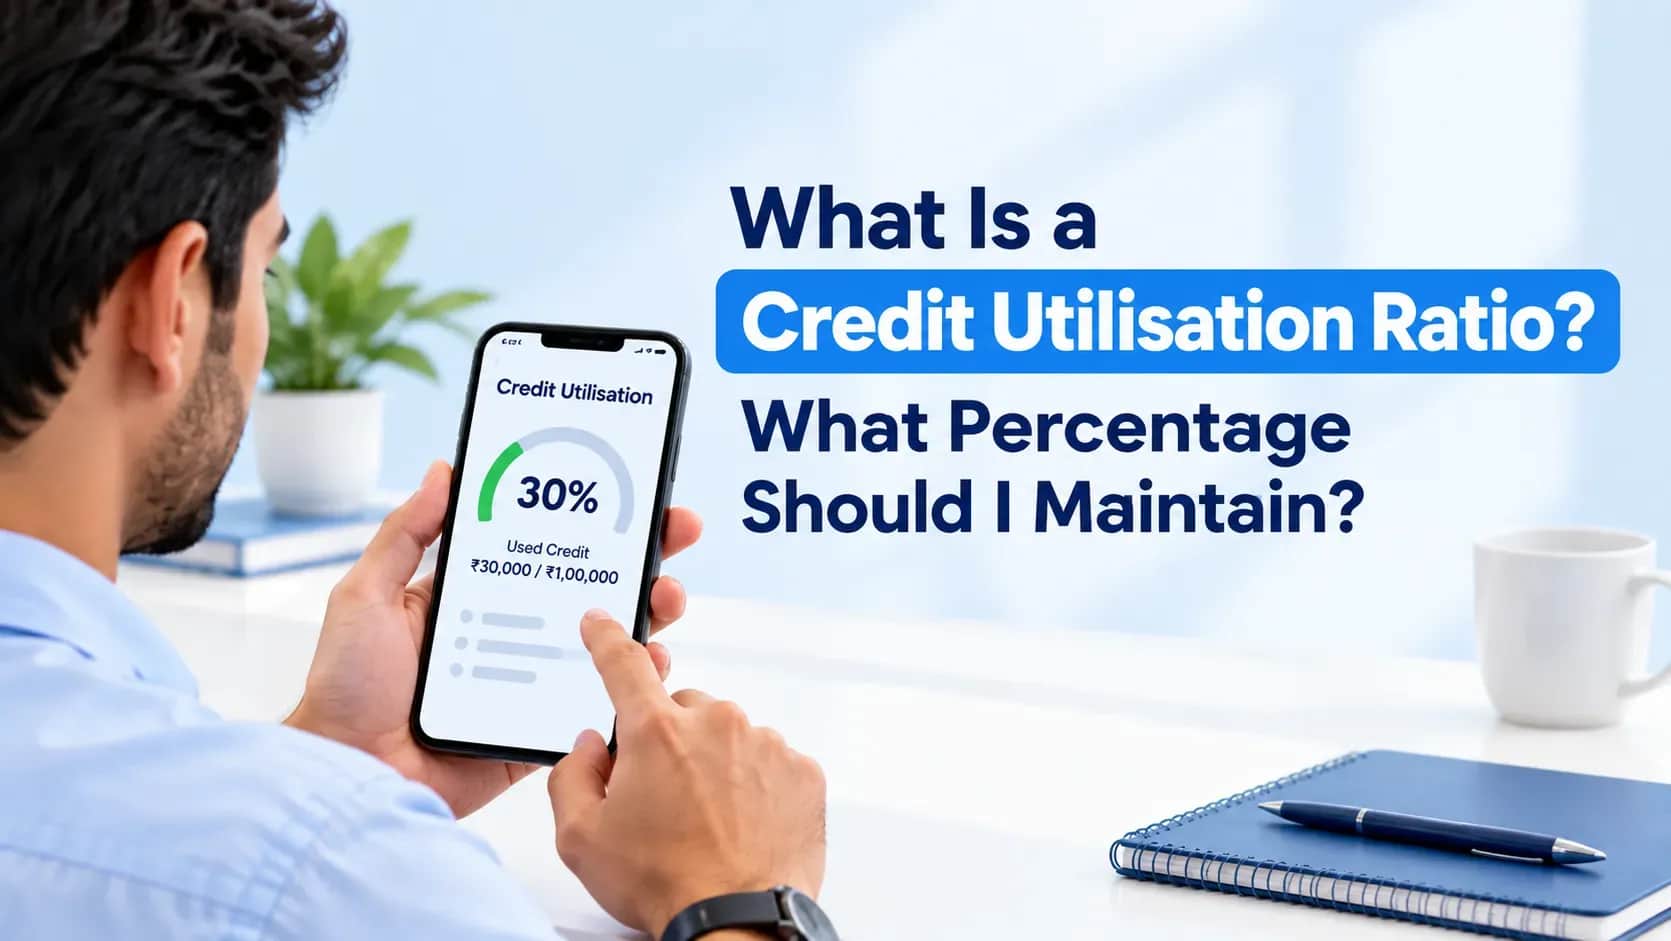
It is believed that the ideal Credit Utilisation Ratio (CUR) is 30% or less. That’s the percentage of your credit limit that’s being used. A less definitive but safer version would be: A lower CUR means you are using a smaller share of the available credit, and a consistently high credit utilisation means you are using a larger share of the available credit. Knowing your CUR will help you to control the use of your credit card and thus maintain good credit behavior. This blog explains how to calculate CUR, what percentage you have to keep, what mistakes might increase it, and how to keep it healthy.
Key Takeaways
The credit utilisation ratio indicates how well you utilise your credit limits. This is represented in terms of a percentage of your total credit limit. This is mostly applicable to credit cards.
The Credit Utilisation Ratio (CUR) tells you what percentage of your total available credit you are using. Your total credit used divided by your total credit limit . Multiply that amount by 100 . This is done by taking your total credit used and dividing it by your total credit limit . A lower utilisation ratio is generally preferred, as consistently high usage may indicate greater dependence on credit.
Formula:
CUR = (Total Credit Used ÷ Total Credit Limit) × 100
Example:
Suppose your credit card has a limit of ₹1,00,000 and you have used ₹40,000. Your credit utilisation ratio would be:
CUR = (₹40,000 ÷ ₹1,00,000) × 100 = 40%
Therefore, your credit utilisation ratio is 40%.
Real Life Example
A recent example of this was seen in a Mint article dated September 2026, which took the example of a credit card with a limit of ₹3,00,000 and usage of ₹50,000. In this example, the credit utilisation rate comes to about 16.7%, meaning the card user has not utilised much of the available credit limit.
Calculation
CUR = (₹50,000 / ₹3,00,000) * 100 = 16.7%
Thus, if an individual has a credit limit of ₹3,00,000 and spends ₹50,000, the CUR will be 16.7%. It's a perfect example showing that the same level of spending can be represented by different credit utilisation ratios depending on the total credit limit
Credit utilisation ratio is an important part of your credit profile. Using a large portion of your available credit, may lower your credit score.
Common Mistakes That Increase Your Credit Utilisation Ratio?
Several common credit card habits can increase your Credit Utilisation Ratio (CUR), including:
*T&C Apply
Avoiding these mistakes can help keep your CUR manageable and support a healthy credit profile.
Maintaining a reasonable Credit Utilisation Ratio can support responsible credit management. According to TransUnion CIBIL, keeping credit card utilisation around 30% or lower is generally recommended.
Some tips to maintain a low CUR include:
A CUR around 30% is generally considered healthy and may indicate responsible credit management. Maintaining the utilisation ratio at manageable levels, by paying off the bills in full and by spending money on necessities, will help you control your CUR. It is vital that you keep track of your credit report and limit yourself with respect to credit limits.
Credit utilisation varies any time there is a change in the balance or the total available credit. Your reported credit utilisation ratio depends on the balance that your creditor reports to credit bureaus.
Yes, an early payment will lower the balance amount that is shown as outstanding, especially if the balance is expected to be significantly high during the current billing period.
Credit utilisation is mainly applicable to revolving credit and not instalment credit. Personal loans fall under instalment credit and therefore have different considerations within the credit report.
An increased limit can lower your utilisation rate if your spending remains unchanged, while its overall effect on your credit score may vary.
It depends on how the supplemental card is tied to the main card and whether or not transactions on the supplemental card are included in the main card's balance.
Credit utilisation can be considered both at the individual credit card level and as a whole credit utilisation ratio.
A credit card with a zero balance also counts in the total credit limit that you have access to, although the utilisation rate is zero at that point.
This would depend on the way the credit card company has reported the conversion of the transaction and the remaining balance on the card.
High CUR may affect credit scores, depending on the credit scoring factors used. The possible effect will be influenced by the reporting period and information in your credit report.
It is not necessary since responsible credit card use may assist in building a good credit history. It is essential to manage spending and repay debts on time.