Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
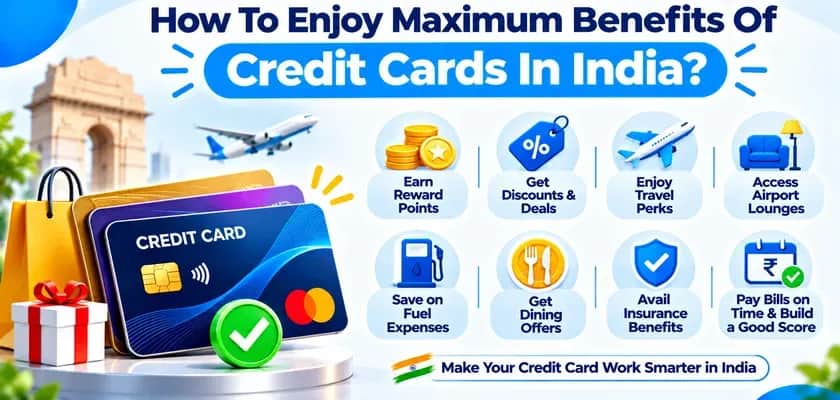
Shopping, emergency bills, and purchasing your dream stuff can sometimes become financially heavy. This is why many people in India use credit cards to fulfil their wishes without worrying much about their finances. But have you ever wondered whether a credit card is limited to making payments? Absolutely not. This is because a credit card may also offer you multiple credit card reward points, cashback, etc. The real challenge is how to use your credit card smartly to enjoy its maximum benefits.
Knowing credit card benefits is not enough until a cardholder aligns those benefits to their spending patterns and uses them correctly. This can be a huge game changer for the cardholder. This is because it can bring the maximum benefits from credit cards for them.
It is very important to understand which variant of credit card suits you in terms of your daily spending. This may directly benefit you by getting reward points, cashback offers, etc.
Find out what the reward rates are, what spending limits your card entitles you to for getting rewards, when you can redeem them before they expire, and where. This can act as a benefit for you.
In order to avoid being charged interest, you should pay the bill in full and on time. It will also help you build a healthy credit history.
Check the terms and conditions first to see whether cashback, discounts, and other promotions are available.
Make sure that the perks of the card are worth its annual charges and other fees. This is because your benefits must justify the fees you will be paying for the credit card as per the issuer’s terms.
Hence, these are some tips a cardholder can consider to utilise their credit card benefits to the maximum. This can be in terms of building their credit score, financial management through rewards and cashback, etc.
Although people might need more funds for travel, vacations, or other big purchases, they can also consider taking personal loans. LoansJagat helps users explore personal loan options from multiple lending partners, making it easier to compare available offers based on their needs and eligibility.
Several credit cards in India offer multiple benefits to people in terms of credit card rewards, cashback, discounts, etc. Knowing these benefits as per their acquired credit card can help a cardholder maximise credit card benefits. Let us consider the benefits offered by the credit cards in India:
Several credit cards may offer the facility of earning reward points for the cardholder as per their eligibility and spending pattern, according to the issuer’s terms and conditions. These reward points can further be redeemed for lounge access, other offers, etc.
For example, the Axis Bank Reward Credit Card. This can offer the eligible cardholder 2 EDGE REWARDS points on every ₹125 spent, and much more.
Certain credit cards offer travel benefits to eligible people, like complimentary lounge access, bonus air miles, travel insurance, etc. Some may provide discounts on hotel stays, car rentals, flight bookings, etc. Such credit cards could lead to easier management of financial expenses for the cardholder.
For example, the IndiGo Axis Bank Credit Card offers travel benefits, including lounge access. These benefits are subject to eligibility and card terms.
The credit card makes online and offline shopping more convenient for the card owner. Additionally, some cards can make transactions safer for the card owner due to built-in security features like two-step verification and fraud protection. Certain cards also allow for splitting the price of a purchase into instalments, which can make big-ticket purchases more affordable.
Card owners should review the fine print on any instalment plans, as there can be additional fees and/or interest rates that apply.
For example, Amazon Pay ICICI Bank Credit Card is a popular lifetime-free card offering unlimited cashback on Amazon purchases for Prime and non-Prime members, alongside partner merchant discounts.
The responsible use of credit cards can improve credit scores. Making payments on time and keeping a low credit utilisation ratio are some of the ways that credit card holders can improve their credit scores.
Credit scores are important to lenders and can help a borrower qualify for better interest rates and additional credit lines, subject to eligibility criteria. Maintaining responsible credit behaviour can assist credit card holders in improving their scores over time.
For example, if you utilise ₹4,000 from the credit card and repay the full amount to the issuer on the payment due date. This could positively affect your credit report and may help you manage or build your credit score.
Many credit cards offer cashback or reward programmes which enable cardholders to earn cashback or reward points when making eligible purchases. Banks may also team up with selected retailers and service providers to offer discounts for dining, shopping and travel bookings. These benefits may help cardholders save on eligible expenses. They can also redeem cashback or reward points, subject to the card's terms and conditions. The benefits of such cards depend on the card's features and spending patterns as well as the applicable redemption terms and conditions.
For example, the CASHBACK SBI Card offers 5% cashback on eligible online transactions and 1% on eligible offline transactions. It is subject to a maximum cashback of ₹2,000 in each category per statement cycle and an overall limit of ₹4,000.
These benefits help cardholders take the maximum advantage of the credit card as per their spending, whether it is travelling, dining, shopping, etc.
Credit cards can be advantageous in terms of offering reward points, cashback, travel privileges, shopping discounts, building a good credit history, etc. To maximise benefits, cardholders should choose a card that matches their spending habits. They should understand the reward and redemption terms. Paying dues in full and on time is also important. Cardholders should compare the benefits with the applicable fees and charges. Responsible usage will enable them to maximise the benefits in good ways.
Multiple credit cards may offer credit card reward points, cashback, discounts, etc., to the cardholder as per the issuer’s terms. It can also help the cardholder build their credit history if they regularly pay their credit card bills on time.
The major drawback of using credit cards is that they can cause a financial burden if not managed properly. Moreover, the reward points or other benefits vary according to the issuer’s terms and spending limits, which one needs to follow to redeem them.
The travel benefits depend on the card type and the issuer’s policies. Hence, there are no standardised travel benefits for all credit cards; they vary from one card to another.
A cardholder can manage their credit score by regularly paying credit card bills on or before the payment due date. This behaviour can help improve their credit score over time.
Yes, reward point eligibility may vary by credit card, depending on the issuer’s terms and conditions, eligible spending categories, transaction types, and applicable spending limits.
Yes, you can have multiple credit cards, each allocated for a particular need such as shopping, travel, and dining, subject to the issuers’ eligibility criteria. However, manage multiple cards responsibly so that you don’t forget to pay any amount due, which may cost you extra fees.
Credit cards can provide numerous benefits to travellers such as complimentary airport lounge access, air miles, discounts on flight and hotel bookings, and travel insurance. Moreover, these benefits depend on the credit card and are subject to the terms and conditions of the issuer.
Eligibility for credit card benefits may be subject to the terms of the card issuer. In addition, missing payments may result in late payment fees, interest charges, and a reduction in credit scores.
Using your full credit limit does not necessarily make you eligible for additional benefits. Rewards and offers depend on your card’s spending limits, terms and conditions. Moreover, high credit utilisation may negatively affect your credit score.
Not using reward points can lead to their expiry or becoming unavailable for redemption. This depends on the issuer's terms and conditions, which cardholders should check when using their credit cards.
Start your journey today
Apply Now*T&C apply