Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
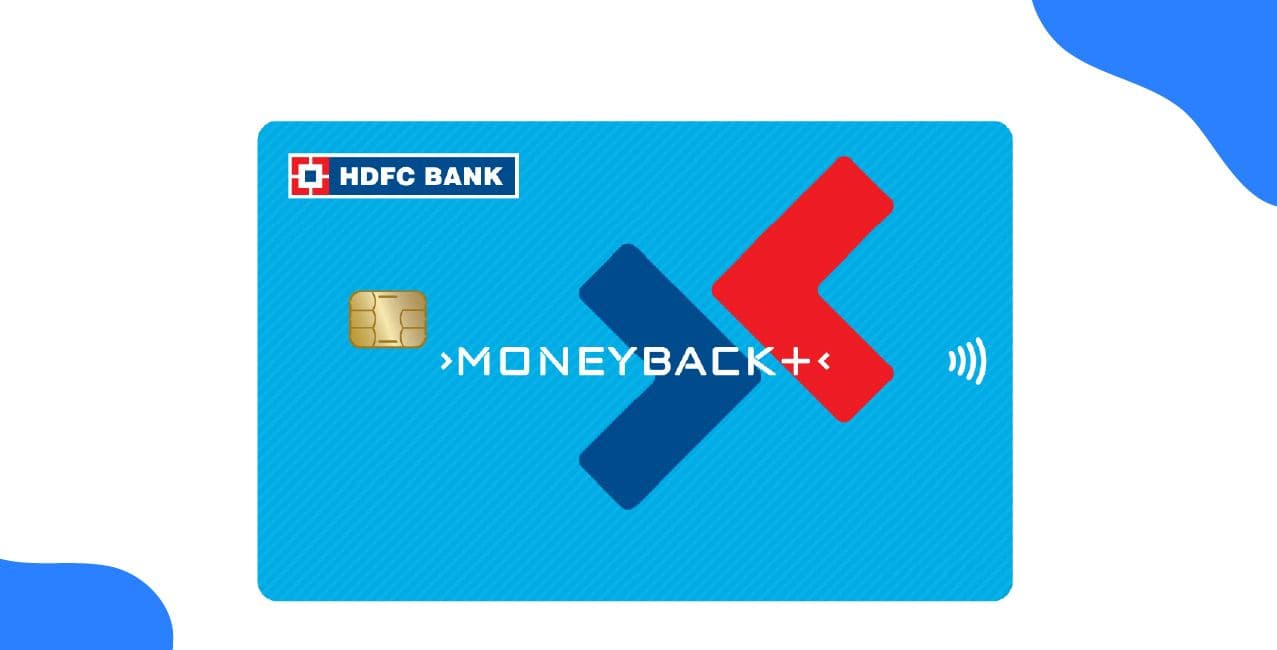
The SBI Cashback Credit Card gives 5% cashback on online purchases and 1% on offline purchases, credited automatically within 2 days of your next statement.
Key Takeaways
Anyone shopping online regularly eventually wonders how this specific SBI card actually pays out cashback, and whether the math genuinely works in their favour. This guide covers exactly how the card functions, its current fee structure, the revised cashback caps, and who should realistically consider applying.
The SBI Cashback Credit Card is a cashback-focused credit card built specifically for online shoppers, offering accelerated returns without tying you to a specific brand or platform.
Per SBI Card's own official page, the card sits within SBI Card's dedicated Cashback Cards category, alongside its other reward-focused products. What genuinely sets it apart is the absence of merchant restrictions, unlike co-branded cards that only pay accelerated rewards at 1 retailer or platform, this card pays 5% back across most online purchases, whether that's groceries, travel, food delivery, or apparel. That said, it isn't every category, railways, insurance, education, wallet loads, gaming, tolls, and government payments are all excluded and earn nothing, even when the transaction happens online.
Beyond the headline cashback rate, the card includes a fuel surcharge waiver, balance transfer facility, and free add-on cards for family members.
Here's what the card actually includes:
The card carries a joining and annual fee of ₹999 plus applicable taxes, which gets fully waived once your annual spending crosses ₹2,00,000.
Since the renewal fee waiver threshold is a genuinely achievable ₹2,00,000 a year, roughly ₹16,700 a month, regular users of this card can realistically keep it fee-free from the second year onward.
A revision kicked in from April 1, 2026, and now online and offline cashback get capped separately, ₹2,000 each per statement cycle, no more single combined ceiling.
Here's how it actually plays out:
Here's the catch though, hitting that online cap alone means spending roughly ₹40,000 a month online, which is genuinely a lot.
Alongside the April 2026 cap revision, the card maintains a specific list of spend categories that don't qualify for cashback at all.
Here's what's excluded from earning cashback, regardless of whether the purchase happens online or offline, per SBI Card's own official revision notice:
Since these exclusions apply consistently, checking whether your regular spending falls into any of these categories before applying helps set realistic expectations about your actual cashback earnings.
This card genuinely suits frequent online shoppers who want straightforward cashback without tracking bonus categories or redeeming reward points.
Consider this card if:
This card suits you less if your spending leans heavily toward the excluded categories, fuel, rent, or insurance, since none of that spending earns any cashback at all.
Apply entirely online through SBI Card's own website, or head to your nearest SBI branch if you'd rather do it offline.
Here's how the online route works:
Once approved, the card is typically dispatched, and delivery can take up to 21 working days from the date you submit your application, though actual delivery timelines vary by location. You'll receive SMS updates once your card is dispatched, including expected delivery details.
Stacking this card up against similar cashback options genuinely helps you see whether it actually fits how you spend better than the alternatives.
Since the SBI Cashback Card pays its 5% rate on most online merchants, subject to exclusions, rather than a select few partners, it genuinely works well for shoppers who don't want to keep track of which platform actually qualifies for the higher rate.
The SBI Cashback Credit Card really comes down to a simple idea, spend online, get 5% back, spend offline, get 1%, and the cashback lands in your account automatically. Since the April 2026 revision introduced separate ₹2,000 caps for online and offline spending each cycle, it's worth comparing your realistic monthly spending against those limits rather than assuming you'll hit the full ₹48,000 a year. For anyone who shops online a lot and doesn't stick to 1 platform, this card genuinely delivers consistent cashback without much fuss.
5% cashback on what you spend online, 1% on offline spends, credited straight to your account within 2 days of your next statement.
₹2,000 per statement cycle for online, another ₹2,000 for offline, that's been the rule since April 1, 2026.
Up to ₹48,000, but only if you're consistently maxing out both caps every single cycle.
₹999 plus taxes, and that same amount applies each year again as the renewal fee.
Yes, spend ₹2,00,000 or more in the year before renewal, and the fee disappears entirely.
Fuel, rent, wallet loads, insurance premiums, utility bill payments, education fees, jewellery, government payments, railways, tolls, digital gaming platforms and merchants, and EMI conversions and quasi-cash transactions, none of it counts.
Yes, 1% waiver, capped at ₹100 per cycle, on fuel purchases between ₹500 and ₹3,000.
Online through SBI Card's website, or just walk into your nearest SBI branch if you'd rather go that route.
Usually 7 to 10 business days.
Yes, spouse, parents, children, or siblings over 18, and they get the same cashback benefits you do.
Start your journey today
Apply Now*T&C apply