Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Several lenders may offer personal loans for debt consolidation to eligible people. But when it comes to eligibility, there are multiple factors a lender may analyse before offering a debt consolidation loan. Among these is the salary of the borrower. Lenders assess a borrower's salary alongside existing financial obligations and other eligibility factors to determine repayment capacity. A borrower's monthly income helps lenders assess their repayment capacity and financial stability.
Key Takeaways
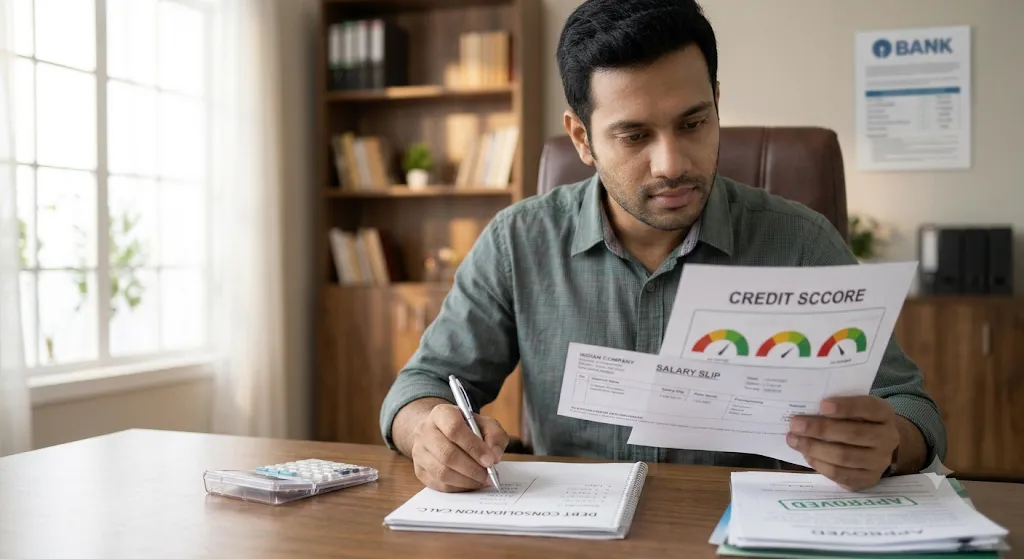
Borrower’s monthly income is one of the important factors lenders may assess before offering the debt consolidation loan. The monthly income helps the lender to assess your debt-to-income ratio and helps to build the trust for your repayment capacity. They may consider certain factors before calculating your debt consolidation loan amount based on your salary. The following factors a lender may consider before offering a debt consolidation loan are:
Your monthly salary and other eligibility factors may determine the borrower's borrowing capacity. It also helps lenders assess the borrower's repayment capacity alongside existing debts.
Your current repayments on any other existing loans and financial commitments may impact how much you can borrow.
Your credit score and repayment history may affect your eligibility to get the loan. The margin for credit score and other important factors may vary from one lender to another.
The selected loan tenure may affect the EMI amount and overall borrowing eligibility.
Borrowers must consider the important terms and conditions offered by the lender for the debt consolidation loan. This may give them clarity on aligning their financial capacity and credit profile for debt consolidation.
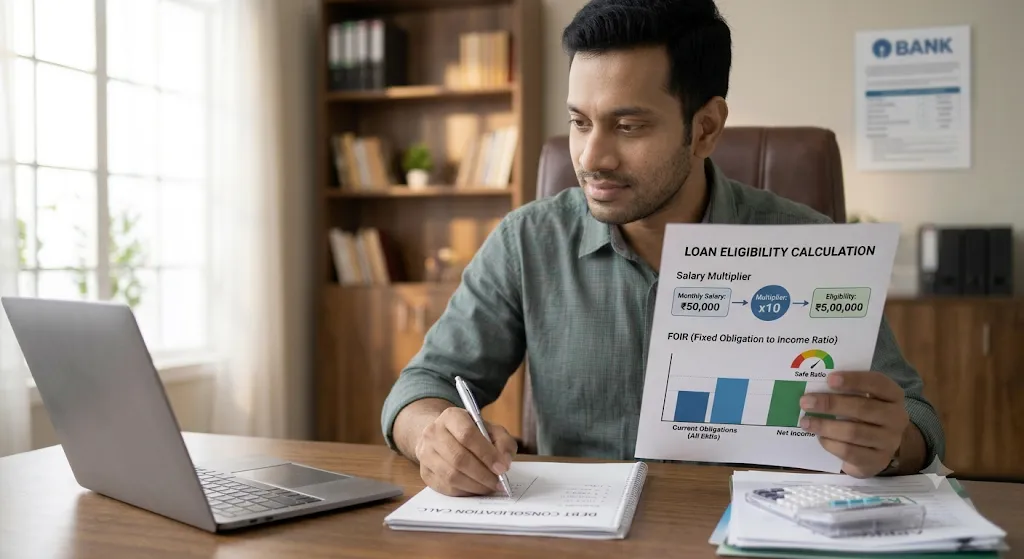
When taking out a debt consolidation loan, your lender will look at your ability to repay and other important factors. This will help them decide how much they can offer you based on your income. These factors includes:
Lenders may assess your outstanding loan balances, monthly EMI obligations, repayment history, and number of existing loans to determine your eligibility. Lenders may consider the proposed loan amount offered to the borrowers to help to cover the existing debts or not.
Lenders may consider your monthly income, credit history, etc., to determine how much you can borrow. Each lender may have different requirements for this based on their terms and policies.
Borrowers must consider the existing debts before choosing the debt consolidation option. This may help them to understand how much funds they need to get from the lender.
Multiple lenders in India may require several income-related documents to assess eligibility for a debt consolidation loan amount, which may vary. The following documents may be required for the debt consolidation loan:
Depending on the lender you choose, you may need different documents to qualify for the right amount of debt consolidation loan. Therefore, enquiring beforehnade can help you to keep the documents ready on time.
Borrowers must consider certain mistakes to avoid when considering the debt consolidation loan amount. This might include points like ignoring your existing EMIs, applying for a higher loan amount beyond your repayment capacity, and overlooking your credit history. These factors can influence the debt consolidation loan aspects directly.
Borrowers must read all the terms and conditions before they apply for the debt consolidation. They must keep all the required documents ready that the lender may require to assess your income, identity, and employment. The loan amount should align with the borrower's financial capacity and repayment ability. This may help the borrower to avoid debt to some extent and perform better loan management.
The debt consolidation loan amount is decided by the lender after assessing multiple factors of the borrower, such as salary. The lender may consider and calculate the borrower’s salary through the debt-to-income ratio, assess their existing debts, etc., to determine the repayment capacity. This is further used to estimate the debt consolidation loan amount for a particular borrower.
Multiple lenders may require different documents to analyse the salary or income for the debt consolidation loan amount. The borrower must enquire beforehand about these terms and conditions to keep documents ready. Considering different lenders and their requirements can be complex; therefore, LoansJagat can offer a one-stop solution for people. It compares and analyses the borrower’s profile across 50 RBI-regulated banks and registered NBFCs.
Salary may help the lenders to determine the repayment capacity of the borrower against existing debts for the debt consolidation loan.
Multiple lenders may consider the borrower's salary an important factor when assessing eligibility for a debt consolidation loan.
Borrowers may get a debt consolidation loan with a low salary, but the lender may assess various factors before offering it. This may include the borrower's repayment capacity, credit history, debts, etc.
The borrower can add a co-applicant for debt consolidation based on the lender’s acceptance, terms and assessment.
Different lenders may offer different debt consolidation loan amounts to borrowers based on their eligibility and the lender’s assessment.
DTI stands for debt-to-income ratio. It is the analytical tool used by the lender to analyse the borrower’s repayment capacity against their existing debts based on monthly income.
Borrowers must not ask for a higher loan amount than they can afford to pay back. This may result in larger EMIs and further put pressure on your finances.
Multiple lenders may consider the borrower’s salary slip to determine the debt consolidation loan amount. This may depend on their terms and policies.
The borrower can apply for a debt consolidation loan with a salary of ₹70,000, depending on the lender’s eligibility and terms.
Self-employed individuals may also apply for a debt consolidation loan. However, eligibility criteria may vary across lenders. Borrowers should review the loan terms and conditions before applying.
Start your journey today
Apply Now*T&C apply