By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Anishka Bhadly
Anishka Bhadly is a content writer with a finance and business background. She has completed her bachelor's degree with a specialisation in finance and is currently pursuing an MBA in the finance field too. The knowledge she has gained from her studies and experience working with EdTech companies helped her combine theoretical knowledge with practical industry insight. Her expertise lies in creating well-researched, informative, and reader-friendly content in various banking, personal finance, loans, insurance, and investment-related topics.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
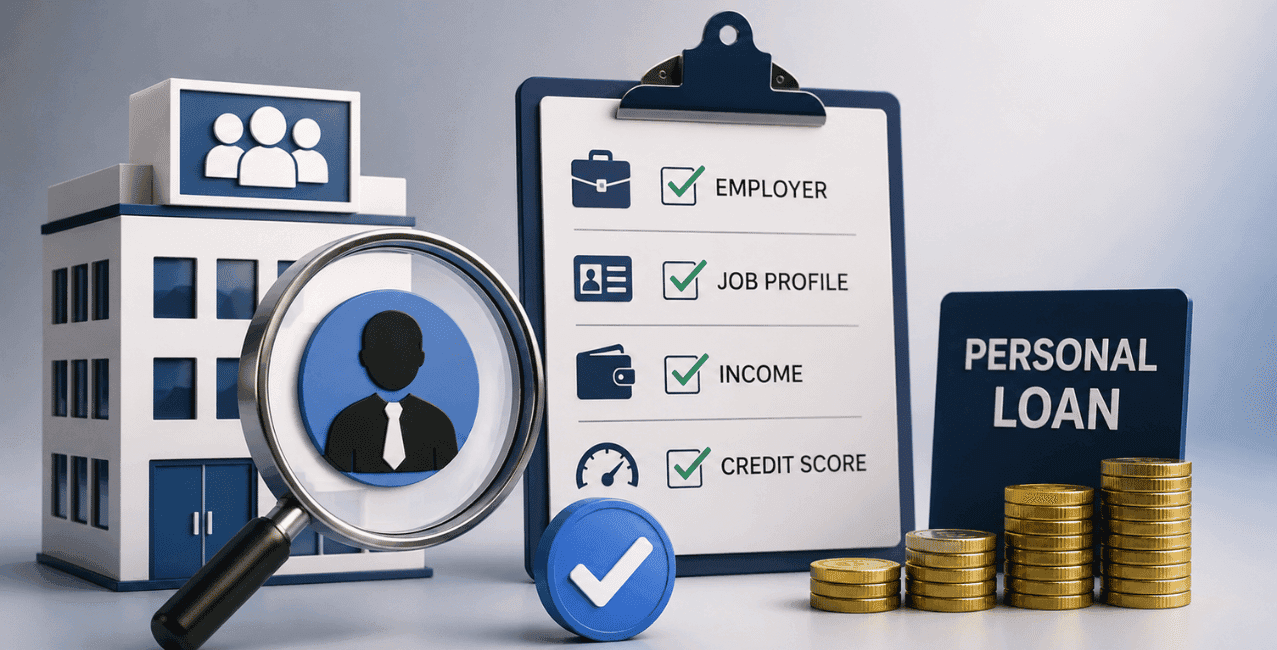
Your own employer category plays a significant role in qualifying for a personal loan, as a lender will look at the stability and reliability of your occupation. Thus, individuals working in government undertakings, public-sector undertakings, MNCs, and reputed private limited companies have better chances of loan approval as their salary is seen as reliable and stable. Moreover, depending upon the category of your employer, some lenders offer varying loan amounts, rates of interest, or terms and conditions.
However, your employer category is just one of the factors taken into account by the lender. Several other criteria, including your credit score, monthly income, total outstanding EMIs, years of experience, repayment history, age, and overall financial status, are evaluated to decide your loan eligibility.
Your job profile may have an impact on getting a personal loan. Lenders focus on your job location, stability, monthly income, and employer’s brand value. If you work for a reputed company or government organisation, or PSU, you may have an advantage over others. But your employer is not the only deciding factor. The credit score, existing EMIs, repayment history, and other factors also contribute to a loan request.
Your profession could play a significant role in determining the lending decision for your personal loan application. Since personal loans are an unsecured form of credit, lenders examine your employment history and salary status to decide the terms and conditions of your loan, including the amount, interest rate, repayment schedule, etc.
Factors That Could Influence Your Personal Loan Application
Your profession is usually not a deciding factor in personal loan eligibility. However, most lenders do give preference to applicants with stable jobs, higher income, good credit scores, a good repayment record, and a lower liabilities-to-income ratio.
Your employer's reputation can play a vital role in approving your personal loan application. Lenders believe that if you work in a reputed organisation, your income is stable, and you have a lower chance of defaulting on the repayment of the personal loan. Your lender will categorise your company in a particular segment depending on the size, sector, and financial credibility of the organisation. When applying for personal loans in India, your eligibility can improve if you work in an organisation that has a good image in the market. Nevertheless, this does not indicate that if you work in a small organisation, you cannot get a personal loan. It also depends on your income, creditworthiness, years of experience, and repayment history.
Lenders qualify applicants for different employment types based on income stability, job security, and the likelihood of them being able to repay the loan. That’s why the type of employment plays a part in the amount, interest rate, documentation needed, and personal loan approval odds in general.
Regardless of the type of employment, having a decent credit score, stable income, low levels of debt, and a good repayment history can help increase your odds of being approved for a personal loan.
Improving personal loan eligibility is mostly dependent on the ability of an individual to repay the borrowed amount to the lender. Maintaining a good credit score, low debt, stable income, and a suitable tenure can increase the possibility of approval and even improve terms and conditions of the loan.
Keeping the credit score above 750 is a good way to increase eligibility. Paying off EMIs and credit card dues on time helps maintain a good score.
It is important to maintain a low debt-to-income ratio. It is calculated by dividing monthly debt payments by income. Having an extremely low debt-to-income ratio shows the lender that the borrower has more income than expenses and thus can easily repay the loan amount.
Selecting a longer tenure lowers the monthly payments, thus making it easier to repay the loan amount.
Having a stable job and consistent income shows lenders that the borrower can repay the money.
Personal loan eligibility criteria are not solely dependent on the salary and the company one works for. Maintaining good credit scores and lowering the debt-to-income ratio, along with secured and stable jobs and longer tenures, can also improve eligibility. Moreover, following these things can also help in negotiating better offers while availing of the loan.
Your category of employment affects personal loan approval chances, but it is unlikely to be the primary criterion. Having a well-paid, stable job, an excellent credit history, and low debt can improve your options even with a low-tier position. Compare different lenders’ requirements instead of focusing on how your company category may impact the outcome. A competent lender can help you secure a personal loan regardless of your line of work.
Eligibility may depend on the type of employer, stability of the company, profile of the organization, etc. However, it is only one of the deciding factors. It is better to consult with a lender regarding the application.
Lenders are usually more inclined to provide a personal loan to government employees, people with PSU jobs, private limited employees, and people who work in private companies with a stable work environment.
Applicants working in small-scale organisations or medium-sized companies may also be eligible for a personal loan. However, lenders may require additional verification of income and stability of work in contrast to people working in private limited or public limited companies.
While a good salary is necessary, multiple factors determine if someone is eligible for a personal loan. Credit score, current or past EMIs, age, stability of work, repayment history, and other factors are considered as well.
A credit score of 750 and above is considered good and increases the scope of loan approval.
Contract employees may find it difficult to get a personal loan due to their work nature. It is best to apply in the name of your company if you are working on a contract basis.
Yes, it does. If you switch jobs often, it might have a negative impact on your application due to unstable income. It is suggested to maintain a steady stream of income.
Self-employed people can apply for a personal loan, but extra documentation may be required to prove a regular income, such as ITR, bank statements, and other financial records.
The ways to increase personal loan eligibility are as follows: Having a decent credit score, not having existing debts, having a stable job, and applying for a manageable amount of money based on your income.
Yes, an applicant’s employer category can affect the personal loan applicant’s interest rate. However, your credit score and repayment capacity also matter.











