By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
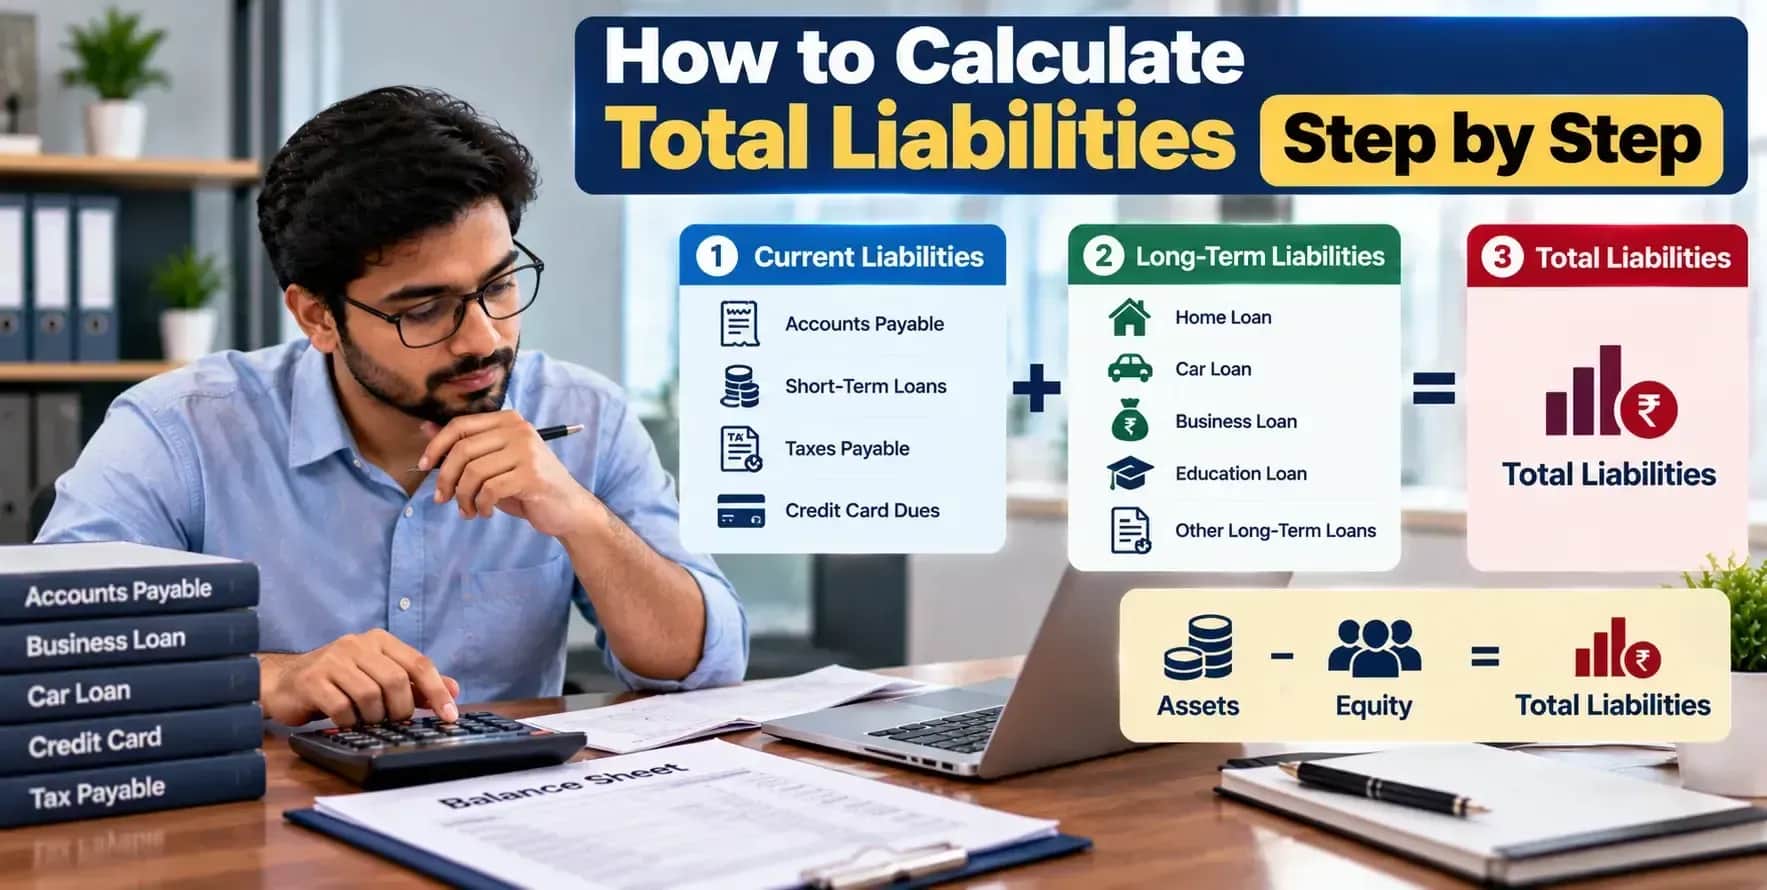
The computation of total liabilities can be made possible by summing up the current and non-current liabilities of the company. Generally, current liabilities are obligations that need to be paid within one year or the normal operating cycle of the business organisation. On the other hand, non-current liabilities refer to those liabilities that will be paid in the long run. Calculating total liabilities is very useful to know the financial obligations of the firm and to measure its financial status. The computation of total liabilities can be made through the use of balance sheet data and can be verified through the accounting equation as Total Liabilities = Total Assets - Total Equity.
Key Takeaways
Total liabilities represent an entity’s present obligations arising from past events, including debts and other liabilities. Such debts include debts like accounts payable, salaries payable, taxes payable, loans, leases, accrued costs, and other liabilities.
Liabilities are generally classified into two main categories:
By combining the two classifications stated above, total liabilities can be determined.
The basic equation is:
Total Liabilities = Current Liabilities + Long-Term Liabilities
As an example, consider the case where a business has:
Therefore,
Total Liabilities = ₹4,00,000 + ₹6,00,000 = ₹10,00,000
The total liabilities of the business will be ₹10,00,000.
There is another way to calculate total liabilities through the accounting equation,
Assets = Liabilities + Owner’s Equity
Or
Total Liabilities = Total Assets - Total Owner's Equity
An entity classifies a liability as current when:
Calculating total liabilities requires that you figure out all the financial responsibilities of the business and combine them based on the period in which they will be paid back. Here is how you do it:
The first step is getting the most recent balance sheet for the business. The reporting date is very important since liabilities change from one accounting period to another due to loans, payments, expenses, purchases, and other activities.
Identify the liabilities that meet the criteria for classification as current under Ind AS 1. Classification should be based on factors such as the entity’s normal operating cycle, the purpose for which the liability is held, and the timing and rights relating to settlement. Examples may include trade payables, accrued expenses, tax liabilities, short-term borrowings, and current portions of longer-term obligations, where they meet the applicable classification criteria.
The following thing to do is to identify all the long-term liabilities from the long-term liabilities section. Examples may include long-term borrowings, lease liabilities, notes payable, and deferred tax liabilities, subject to applicable classification requirements.
Once both types of liability have been classified, the next step is to add the total current liabilities and total long-term liabilities.
Total Liabilities = Total Current Liabilities + Total Long-Term Liabilities
Once you have totaled the liabilities, it is important to double-check the number through the accounting formula below:
Total Liabilities = Total Assets − Total Equity
Suppose ABC Manufacturing Ltd. prepares its balance sheet as of 31 March. Its liabilities are listed as follows:
*T&C Apply
The company also has the following long-term liabilities:
The following formula can be used to calculate the total liabilities from both categories:
Thus, the total liabilities of ABC Manufacturing Ltd. would be ₹15,25,000 as on 31 March.
The calculation can be verified using the accounting equation. Since the total assets and total equity of the company are ₹25,00,000 and ₹9,75,000, respectively, the total liabilities will be ₹15,25,000.
Total liabilities mean the financial obligations of the company and include current and long-term liabilities. The calculation of total liabilities may be done through the addition of the two or the difference between total assets and total equity. It is necessary for companies to review their balance sheets in order to identify their liabilities.
Total liabilities are those financial obligations of the entity which are held by the creditors or other entities against the business. Total liabilities can also be used in analysing the extent of the debt position of the firm.
Liabilities in themselves need not always imply a cash transaction, but settling these liabilities does impact cash flow. For instance, paying off of the loan decreases cash flow whereas purchase on credit increases liabilities without any cash transaction.
Yes, a company can have liabilities even without taking a loan from anyone. Various unpaid accounts, salary payable, taxes, leases, etc., are a few examples of such liabilities.
All liabilities are recorded as monetary amounts but there could be some liabilities that need to be recorded for provision of goods or services rather than cash payment. This is going to depend on the nature of the liability.
As compared to total assets of the company, liabilities lower the amount of residual interest for the owners. It means that an increase in liabilities, in the absence of increase in assets and other components of equity, may lower the amount of net assets.
Yes, liabilities can rise when an expense is incurred or goods and services are received on account. It means that a liability for payment of an electric bill may arise despite non-receipt of any cash.
The repayment of debts will normally result in a reduction in the amount of liability as well as cash or bank account of an organisation. The reduction in the amount of liability represents the amount of liability which has been paid.
Liabilities are obligations of an organisation based on transactions or events which occurred in the past whereas provisions are liabilities which have uncertainties as regards their timing or amounts.
The liability will be removed from the books when there is payment of the liability, cancellation, or expiry of the liability among other cases of derecognition of the liability according to the accounting standards applicable for the same.
Expense refers to the cost incurred in earning income within the accounting period while liability is an obligation that exists as at a certain reporting date. The expense may result in the liability since the expense amount is not paid.