By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
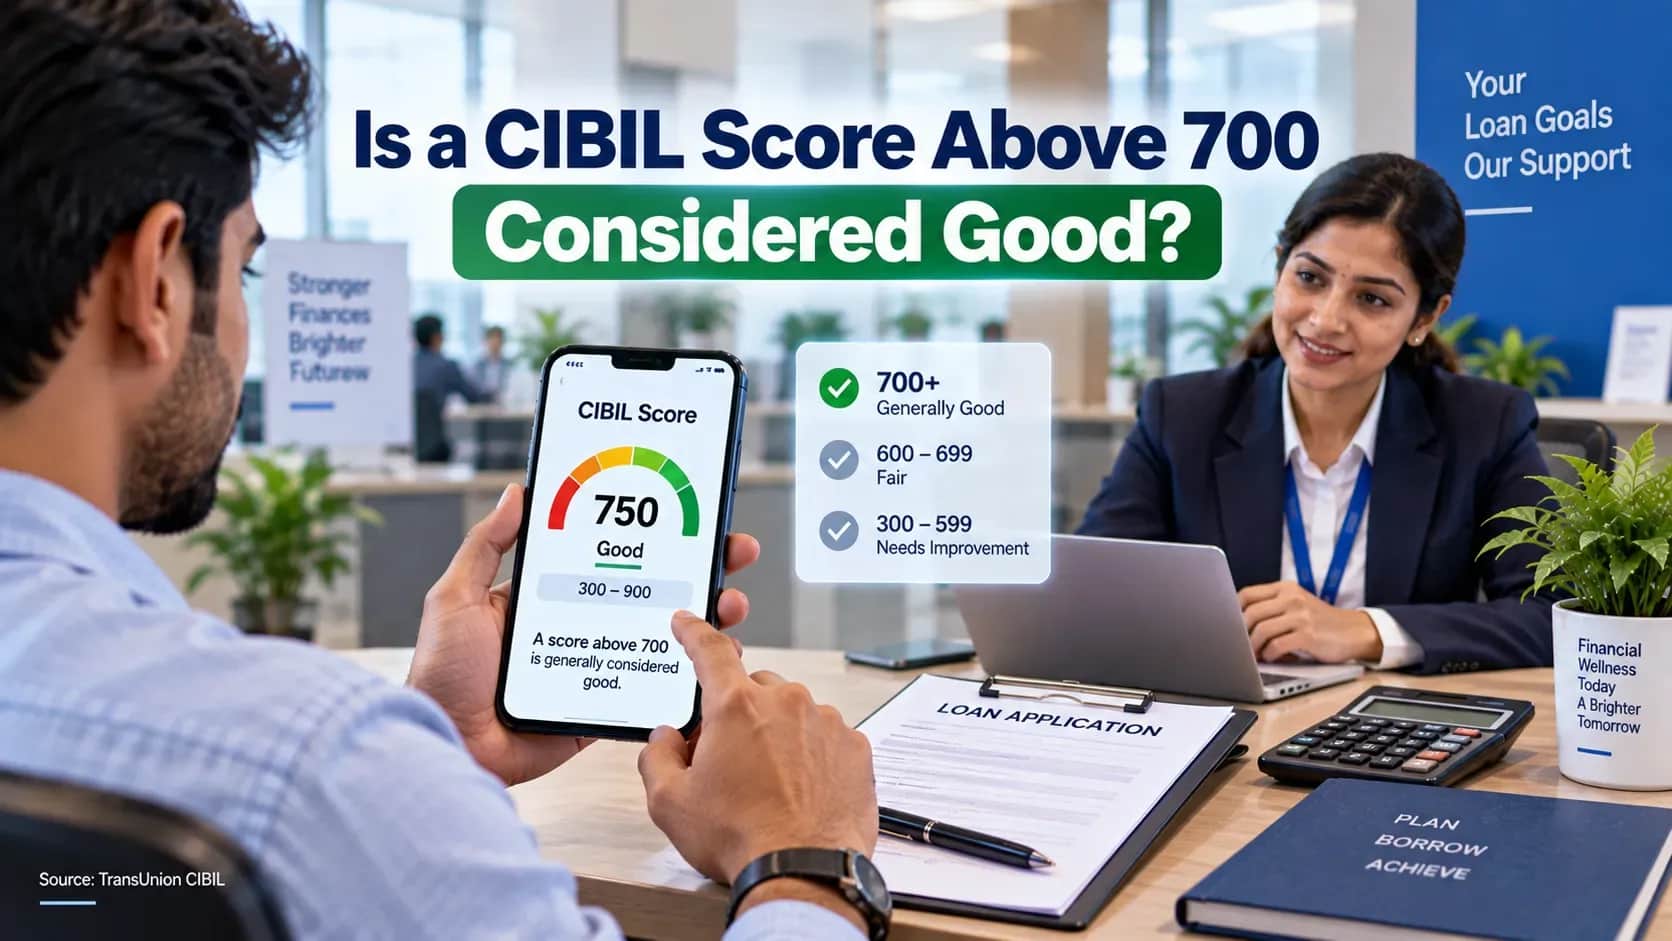
Indeed, having a CIBIL score of more than 700 is good because it shows responsible credit usage. It could mean that you have been doing well in managing your loans and paying off your credit card bills, and it will make it easier for you to qualify for credit. Nevertheless, 705 and 790 scores do not provide you with the same opportunities since lenders evaluate their scores differently. Learning the meaning of your CIBIL score will help you realise where you stand in terms of your credit profile and how to better it.
A CIBIL score is an indicator that consists of three digits representing your credit history. It is based on the information in your CIBIL credit information report, which includes information about loans, credit card history, and repayment behavior, among others.
The score is between 300 and 900. The closer the score is to 900, the higher the credit history and the higher the probability of having your loan request favorably considered. But your CIBIL score alone cannot ensure that you get the loan, as there are many other considerations that lenders need to take into account.
A CIBIL score greater than 700 can be said to be a good score, as it indicates that you have been behaving responsibly when using your credit.
But then again, every high CIBIL score cannot mean the same thing. Take, for instance, a case where one has a CIBIL score of 705 as well as a CIBIL score of 790. Both scores are greater than 700 but could still be perceived differently by lenders.
Many applicants would find a score greater than 750 to be better, especially when applying for a housing loan.
This table summarises the interpretation that varies based on your CIBIL score range:
These ranges are indicative rather than universal lender rules. Different lenders can have different credit policies and eligibility requirements. CIBIL itself states that a score above 700 is generally considered good.
It is not that a CIBIL score of 700 is bad for a home loan, although it may not be the best score to have.
In the case of a home loan, a score of 750 or above would be better. While a person with a 700 score can qualify for the loan, the lender may examine their application in detail, and other factors will assume great importance.
These include:
Thus, having a CIBIL score of 700 and wanting to apply for a home loan, you should try to improve your score.
There are various benefits to having a CIBIL score greater than 700.
A good credit score can give a favorable first impression of your credit. Thereafter, the lender will take into account your income, liabilities, and other criteria for making the final decision. As per CIBIL, the higher your credit score, the better your chances of getting your application approved.
Having a good credit profile can enable borrowers to avail of more favorable terms of lending. However, it must be noted that the interest rates are not decided only by the CIBIL score. The lender can even consider your income, employment profile, loan amount, tenure, and repayment capacity.
People with a good credit history have an easier credit assessment process since their borrowing pattern shows good financial management practices.
Having a good credit profile is a good negotiating tool that allows you to shop around and negotiate better terms, even though the final offer will be up to the lender.
People with a good credit profile find it easy to access various forms of credit in the future, including personal credit, home credit, and credit card facilities.
Some of the most critical aspects of the credit report that impact the CIBIL score include:
In case your CIBIL score is somewhere around 700, then there are ways through which you can improve it.
It is usually a slow process to improve your CIBIL score. Repayment behaviour is better than finding a quick way to increase CIBIL score.
Not at all. Checking your own CIBIL score will not lower your CIBIL score.
If you are checking your own CIBIL report, then this will be categorized as a soft inquiry, and it will not affect you in the same way as a hard inquiry made by a lender. In this manner, checking your CIBIL report from time to time could be a reasonable approach.
Yes. Although both scores show a relatively healthy credit history, 750 puts the borrower in a much better situation compared to a 700 rating, especially for large borrowings like a home loan.
Although 700 is not something to panic about, thinking that your loan application will definitely be denied just because of it, it can be considered a decent start to building a good credit history.
In turn, having 750 does not mean getting approved or the interest rates on it; lenders evaluate applications by their own eligibility criteria, regardless of CIBIL score.
CIBIL scores above 700 are considered to be good. This is an indication that you manage your credit properly. A higher score of 750 or more might give you more borrowing advantages. You can work on getting such high scores by making timely payments, using your credit carefully, not applying for many credits, and checking your credit report often.
It will take some time for the details to be updated on your credit report. The time period can differ according to the time at which the lenders share the information with the credit bureau.
If the closure of your loan account is successful, then this may have a positive effect on your credit report. However, the outcome is not always guaranteed.
Not necessarily. Your salary does not influence your credit score. Even a person who earns a relatively small income and makes timely repayments will get better scores compared to a highly paid person.
The repayment performance on a joint loan can affect the credit performance of all those who are equally responsible for the repayment of the loan. Hence, delay or failure in the repayment process may affect more than one borrower’s credit record.
While rejection of a loan application by a lender may not directly harm your CIBIL score, multiple rejections may result in numerous credit inquiries that may impact your credit record.
Settlement of the loan may be considered differently compared to the repayment of a loan based on the terms and conditions decided earlier.
Just changing the bank where you keep your money will have no effect on your CIBIL score. This score is mainly linked to your credit cards and your repayment behavior instead of your savings account with the bank.
Not necessarily, but when you close an old credit card, it could alter your available credit limit as well as your credit history.
In general, employers do not review your CIBIL score during their employment procedures. However, there could be specific instances where your employer may perform a financial background check due to relevant policies and regulations.
Yes, the credit scores by various credit bureaus could differ since the credit bureaus receive different data and use different methods for rating. Hence, having one score greater than 700 does not guarantee that all credit bureaus have the same score for you.
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article










