Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Are you planning to apply for a personal loan but unsure whether your CIBIL score is high enough? There is no single minimum score set for every lender, as each bank or NBFC decides its own cut-off. According to TransUnion CIBIL, the closer your score is to 900, the better your chances of approval. A score above 750 is generally seen as good and may help you get better offers.
Key Takeaways
No single minimum score applies to every lender. Each bank or NBFC sets its own eligibility rules, including the credit score, age, income and existing EMIs it will accept. So the score one lender approves may not work with another.
Lenders don’t share one common cut-off, so the score you need depends on where you apply. A higher score usually improves your chances. TransUnion CIBIL notes on its blog on CIBIL score versus report that 79% of loans are sanctioned to people with a score above 750. A score in that range may also help you get better interest rates.
TransUnion CIBIL itself treats 750 as the benchmark. Its guide states that any score greater than 750 is a good CIBIL Score. According to TransUnion CIBIL, 79% of loans are sanctioned to consumers with a CIBIL score greater than 750. This figure is not specific to personal loans.
The CIBIL score helps lenders assess your creditworthiness based on your credit history and repayment behaviour. It ranges from 300 to 900. According to TransUnion CIBIL, a score closer to 900 may improve your chances of getting a loan or credit card. Even so, approval also depends on your income, existing debts and each lender’s own rules.
Your score can affect whether you’re approved, the interest rate you’re offered and other parts of the lender’s loan decision. The table below shows how, based on CIBIL:
So your score matters a great deal, but the final decision always rests with the bank or NBFC.
Getting a personal loan with a low CIBIL score is possible, but it is usually harder. Lenders may offer you fewer options, a higher interest rate or a smaller loan amount.
Lenders also read your full CIBIL report, not just the 3-digit number. According to CIBIL, lenders may look at your CIBIL Report for a larger view of your credit footprint. This may include checking for the days past due on outstanding payments, red flags on loan accounts or the number of enquiries made on your account.
If you have never borrowed, you may have no score at all. CIBIL Score is available for individuals who have had an active loan or credit card within the last 36 months, as reported to CIBIL. Without one, your report may show “NH” or “NA”.
That is not a bad sign in itself. CIBIL says such scores are not viewed negatively by lenders. However, some lenders' credit policies prevent them from providing loans to applicants with scores of 'NA' or 'NH'.
If your score is low, these options may help:
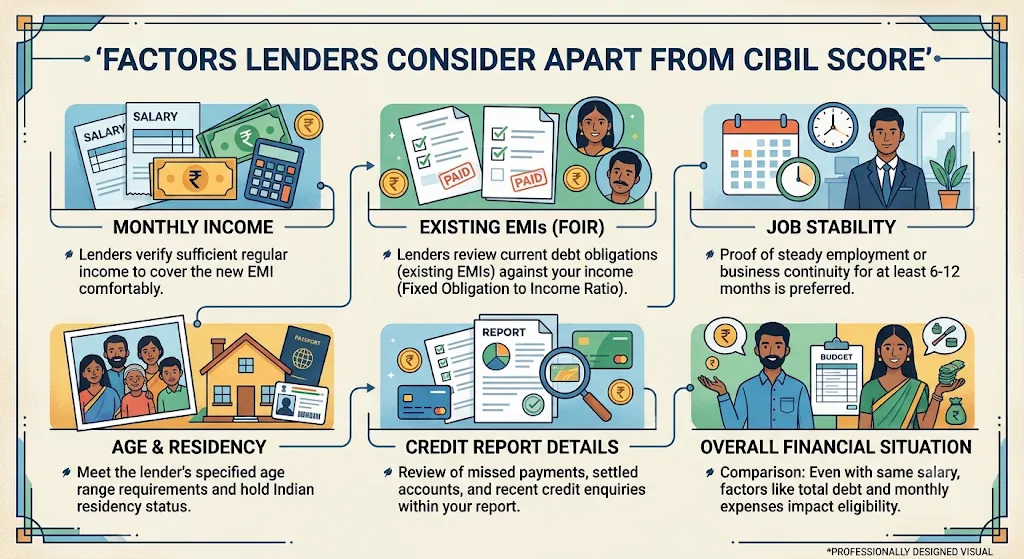
Your score is only one part of the decision. Lenders also check whether your income can comfortably support the new EMI.
Two people with the same salary can get different loan amounts because lenders look at their overall financial situation. Factors like existing debts, credit score, job stability, and monthly expenses can affect loan eligibility.
The main factors are:
Improving your score takes steady habits over a few months. These steps, based on CIBIL’s guidance, make the biggest difference:
Changes can now reach credit bureaus faster than before. Under the RBI’s Credit Information Companies Directions, 2025, lenders report credit data as on the 9th, 16th, 23rd and last day of each month. This applies from 1 July 2026. For the 9th, 16th and 23rd, lenders must send updates within 4 calendar days. For the last day of the month, the full file is due by the 5th of the next month. Bureaus then have up to 3 calendar days to process the data. So a change may take a week or more to show in your CIBIL report, and timing can vary.
Before you apply, you can compare personal loan offers from multiple lenders on LoansJagat and check which ones match your score.
The score you need for a personal loan depends on the lender, since each one sets its own rules. Aiming for 750 or higher can give you a better chance of approval and more choice. Download your CIBIL report a few months before applying, so you have time to dispute any errors. If your score needs work, focus on paying bills on time, keeping card balances low and spacing out loan applications.
No, the RBI does not set a minimum score, and each bank or NBFC decides its own cut-off.
CIBIL considers any score above 750 a good score. Most loans are sanctioned to people in this range.
Some lenders may consider it, usually at a higher rate or for a smaller amount. Many lenders prefer 700 or above.
It means you have no credit history, or not enough to be scored. CIBIL says this is not a bad thing, though some lenders may not lend without a score.
According to CIBIL, checking your own CIBIL Score is easy and does not affect your credit score.
Under RBI rules, each credit bureau must give you one Free Full Credit Report (FFCR) including credit score, once, at any time, during a year (January – December).
No, CIBIL only provides your score and report, and the lender makes the approval decision.
Closing an old card can shorten your credit history and raise your usage ratio on other cards.
It can help, but lenders still review your repayment history. You may still be offered a higher interest rate.
It depends on your credit history. Usually a few months of on-time payments and low card usage start to show results.
Start your journey today
Apply Now*T&C apply