By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
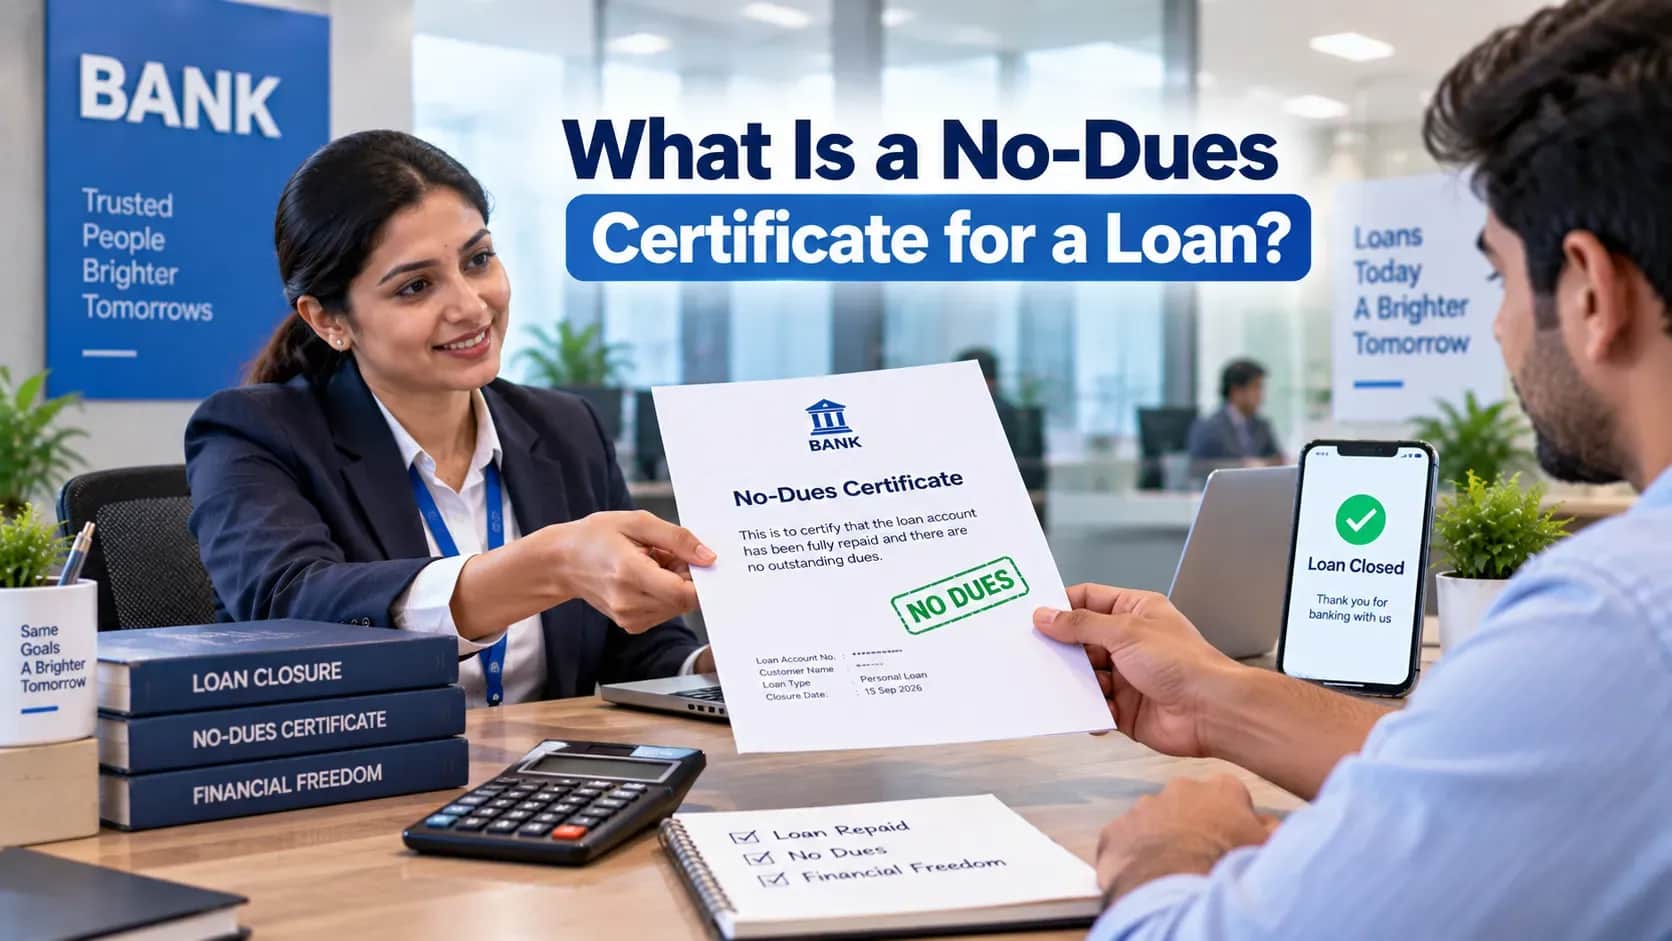
The No-Dues Certificate of the loan is an official document issued to the borrower by a bank or any other financial institution after settling the dues of the borrower and the closure of the loan account. The document serves as proof that there is nothing payable by the borrower towards the loan. Even though a No-Dues Certificate (NDC), No-Objection Certificate (NOC), and Loan Closure Certificate are often used interchangeably in practice by many lenders, these documents may not always be identical. While NDC proves that there are no dues payable towards the loan, NOC generally proves that there is no objection from the lender's side regarding a certain action, like releasing their interests in the asset, and Loan Closure Certificate usually indicates the closure of the loan account. It is, thus, necessary to understand these kinds of documents in order to resolve any dispute relating to loans in the future. By understanding what an NDC means, how to get an NDC, and the reason why you need it, you can properly document your loan closure.
Key Takeaways
No-Dues Certificate for a loan is an official certificate issued by the lending institution when the borrower pays off all dues with respect to the loan account.
The certificate is issued in order to declare the borrower free from any dues or liability towards the lender in regard to the loan account. The No-Dues Certificate contains details like the name of the borrower, the loan account number, the type of loan, and the date of closure of the loan account.
A No-Dues Certificate may also be called a No-Dues Letter, Loan Closure Certificate, or Loan NOC depending on the lender and type of loan.
There is no doubt that an NDC, an NOC, and a Loan Closure Certificate are related in terms of their applications, but there is nothing to say that they could be interchanged with each other. The NDC normally certifies that the said dues are paid. The NOC usually says that the lender does not object to any specific thing. The Loan Closure Certificate normally indicates that the loan account has been closed.
It means that:
Even after the completion of all EMIs, a loan might seem to be over. However, documentary evidence of this might be useful in case of any future dispute or discrepancy. Here are some situations where an NDC may be useful:
Once the loan is repaid, the lender typically reports the account status to the relevant credit information companies. A closed loan is generally not removed from the credit report but is updated as ‘Closed’. This is different from ‘Settled’, which may indicate that the lender accepted less than the full amount due. If the account still appears open or shows an incorrect outstanding balance, the NDC can support a correction request. The NDC itself does not update the CIBIL score or credit report. Borrowers should check their credit report after repayment and use the NDC and other documents to dispute any incorrect information.
At times, any discrepancy in reporting can lead to misunderstandings regarding the status of payment of the loan. Possession of the NDC would help in providing proof of clearance of the dues from the bank's side.
The documentation of loans that have been successfully closed may prove to be helpful for future financing. It serves as proof that the obligations undertaken through previous financing have been fulfilled and that the earlier loan account was closed.
After the loan is fully paid, having documentation of the settlement serves as assurance that the financial obligation has been fulfilled. This should be kept rather than simply relying on account statements and other forms of payment proof.
The exact format of an NDC varies from one lender to another. However, a typical No-Dues Certificate for a loan may include:
You should check the loan account number, name, and closure details carefully before storing the certificate.
The process of obtaining a No-Dues Certificate varies according to different lenders. While some lenders will give it to you automatically after the closure of your loan account, there are those that will require you to request it.
Ensure that all EMIs, prepayment, foreclosure amount, interest, and charges due on the loan have been cleared.
One must not take it for granted that once the final payment is made, it means that the loan account has been closed.
If you don’t have the certificate, get in touch with your bank or lending institution through their customer support services, branches, or other available avenues.
Give all necessary details to the lending institution, such as your loan account number and identity details, and ask them to issue the certificate.
*T&C Apply
Cross-check if the certificate has the right details about the loan account and states that no dues are pending.
It is advisable to keep a copy of the NDC both physically and digitally among your other loan-related documentation.
If the bank fails to send you the no-dues certificate even after the closure of the loan account, you should not overlook it.
First of all, find out whether there is anything outstanding with the loan account. After that, you may request the certificate from the bank in writing.
It is also recommended to have supporting documents like:
In case of errors in the loan status in the records of the bank, NDC, along with these supporting documents, would be very helpful for you.
Although these terms may be used interchangeably by some lenders, they can refer to different documents and purposes:
The terminology and exact purpose can differ between lenders and loan types. Borrowers should therefore check what the document specifically confirms rather than relying only on its title.
No. Receiving an NDC or NOC does not necessarily mean that a charge, lien, mortgage, or vehicle hypothecation has been automatically removed. For secured loans, the borrower may need to complete a separate charge-release or asset-related process.
For example, in the case of a vehicle loan, the applicable RTO/Parivahan process may need to be completed to remove the lender's hypothecation from the vehicle records. Similarly, other secured loans may require separate procedures for releasing the lender's charge or security interest.
The No Dues Certificate is an essential certificate since it acts as proof of your total loan repayment and closure. It protects you from future legal hassles and helps correct erroneous entries in your loan account. After you have settled all your dues, make sure that you get the No Dues Certificate and store it with other financial documents.
Yes, a No-Dues Certificate can act as documentary proof of the acknowledgment made by the lender regarding the clearing of specified dues from the borrower’s side. The effectiveness of the No-Dues Certificate in any dispute depends upon the situation.
The NOC can play an important role while selling the asset or transferring it since for secured loans, the process of the lender’s discharge may become necessary prior to the sale of the financed asset.
Most of the lenders offer digital loan servicing options through which the borrower can request a NOC or download it.
The joint borrower should ideally have access to their own copy of the NDC for future financial record-keeping purposes, especially when there is joint liability for that loan or joint ownership of assets.
It would be helpful to provide documentary proof in case the lender needs to know about the closure of an earlier loan. The approval of another loan, however, would be based on factors like income, credit history, and other eligibility criteria.
A request should be made to the lender for issuing the correct certificate since it is not advisable to use a document with mistakes.
The NDC could be kept as one of your records and might prove helpful in determining when the loan period has come to an end. As for its tax implications, that would depend on the use of the loan.
The new lender would probably require some sort of record proving the status of the old loan in case of refinancing. It will be useful for you to have the NDC at hand in this situation.
Yes, it is possible for the lender to provide the documentation upon closure if the amount payable during the foreclosure process has been paid and all necessary formalities have been completed.
It is possible for the borrowers to verify the document through the issuer, who is the lending institution. Do not base the verification only on the document provided through an intermediary, especially where there is doubt regarding the genuineness.












