By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
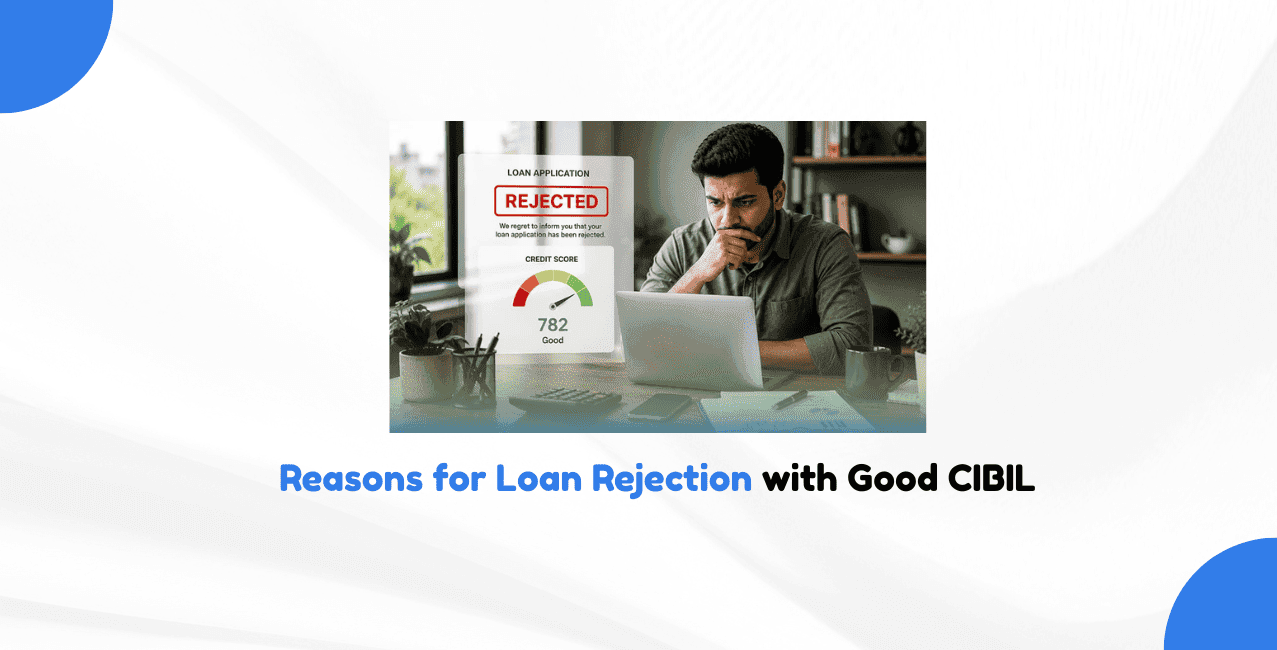
Banks indeed evaluate your credit scores for loan approvals, but it is not the only parameter. Even after having a good or ideal credit score, you can still be rejected by the banks for approving the loan request. The credit score is only one aspect of judgment, but there are other parameters too, like credit history, credit report, your current employment status, income, debt-to-income ratio, banking discipline, etc. A person with a 750+ credit score can be easily rejected by the bank if all the above-mentioned parameters do not match the bank’s expectations. This concept is often confused by people; this is the major reason why LoansJagat creates awareness regarding these things. LoansJagat helps to understand the banking concepts in terms of loans and finance in a simplified way.
Key takeaways:
In India, the financial system follows CIBIL scores for creditworthiness. The CIBIL score ranges between 300 and 900 points. There are several categorisations according to the bank offering loans; in fact, companies like LoansJagat also evaluate your credit score with other parameters before providing financial services like personal loans, business loans, etc., partnering with trusted lenders under the RBI.
These are the categorisations of the credit score in India:
These are the ranges, and according to these, your loan approval requests are accepted or rejected. But this is not the only parameter that banks or fintech companies, like LoansJagat, consider. There are other parameters too.
The parameters for loan approvals other than credit score include credit history, credit report, employment status, income, debt-to-income ratio, banking discipline, age, asset verification, and your credit enquiries.
These are the detailed explanations of loan approval criteria:
*T&C Apply
Hence, these are the parameters that affect loan approvals other than credit score.
Yes, a loan can be rejected for a person even after a credit score of 750 or more. The major reason is that the credit score, or CIBIL score, is just a parameter to filter out people for taking loans, but there is much more to it than this.
Your credit history, your employment status, your monthly income, etc., will be evaluated apart from considering the credit score only. Any form of irregularity or statistics that do not match the expectations of the lender can lead to immediate rejection of the loan.
For example, you have a credit score of 745 and have applied for a personal loan to a bank. But you do not have current job stability, and your income is also not stable. This could lead to loan rejection by the lenders.
There are several ways to come out of this, which are as follows:
Hence, these are some of the ways that can help you stand better in the eyes of lenders, apart from having just a good credit score for loan approvals.
In India, a credit score is not the only parameter for loan approvals or rejections by lenders. Instead, many people, despite having a good credit score, lose their loan approvals due to some irregularities in their other parameters. These parameters include credit history, bank discipline, age, employment status, income, debt-to-income ratio, etc. One needs to meet the lender’s exceptions in all the parameters to build the trust to lend you the loan. LoansJagat always makes people aware of such concepts through their blogs in the banking and finance field.
LoansJagat is a well-known finance aggregator company that provides financial services like personal loans, business loans, and debt consolidation options to people through channelling trusted partner banks, NFBCs, or lenders. It works heavily under the guidelines of the RBI. It provides people with a perfect channel to manage their debts or loan-related queries. It analyses people’s financial standing and matches them with approved RBI-guaranteed lenders for hassle-free financial services.
FAQs:
Yes, one can get a loan even after a bad credit score, but this can be a rare case or only a secured form of loan with very high interest rates and harsh terms and conditions from the lender.
Scores above 750 can be considered good credit scores, which can be one reason for easy loan approvals.
These parameters include credit history, bank discipline, age, employment status, income, debt-to-income ratio, assets for secured loans, credit enquiries, monthly income, etc.
Yes, many times this happens because there are other parameters too, which affect the loan's approval rather than the credit score.
First, analyse all the parameters the lender is considering; analyse your standing according to those parameters and take stable actions accordingly.
Debt-to-income ratios determine the capability of a person to take out another loan with their current income. If the DTI ratio is high, then loan approval is difficult, and if the DTI ratio is low, then loan approval becomes easier.
Yes, employment status matters for loan approvals, as it helps lenders get assurance of stable income, and a person can take out a loan.
No, each bank has different eligibility criteria for loan approvals.
The full form of CIBIL is Credit Information Bureau (India Limited.
India follows a credit score range of 300 to 900.












