Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
A loan settlement may help borrowers address outstanding dues during financial hardship. It can also affect their credit report and score, which may influence future borrowing decisions. Despite this impact, a settled loan does not automatically prevent borrowers from applying for a new loan in India. Approval depends on the lender’s assessment of the applicant’s credit history and eligibility.
A loan settlement may help borrowers address outstanding dues during financial hardship. It can also affect their credit report and score, which may influence future borrowing decisions. Despite this impact, a settled loan does not automatically prevent borrowers from applying for a new loan in India. Approval depends on the lender’s assessment of the applicant’s credit history and eligibility.
Key takeaways:
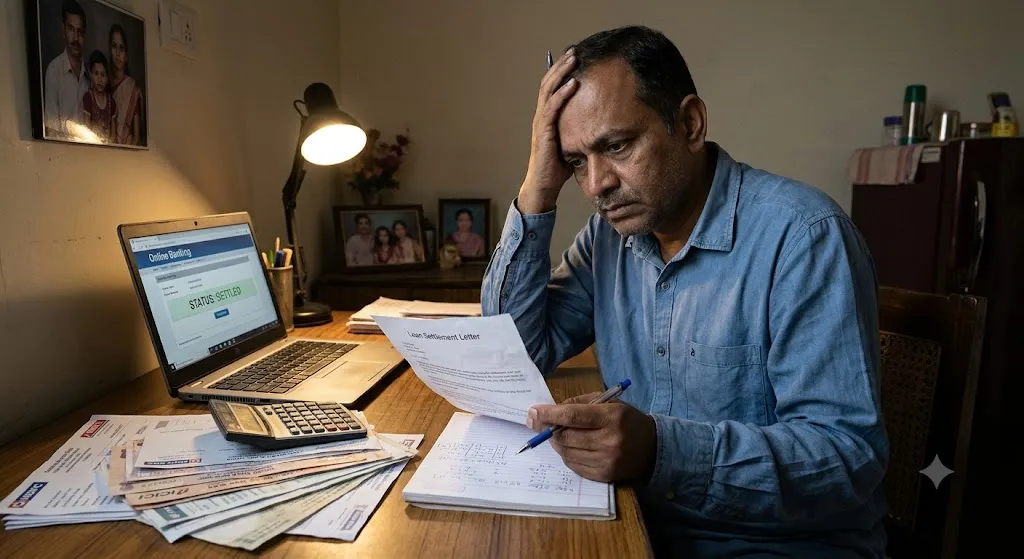
You may be able to get a new loan after settling an existing one, subject to the lender’s approval. A loan settlement is an agreement between the borrower and lender in which the lender accepts a reduced amount towards clearing the outstanding dues. However, the account may be reported as ‘Settled’ on your credit report, which can affect your creditworthiness and future borrowing options.
A settled remark does not automatically prevent you from applying for another loan. However, lenders may review your credit history, repayment behaviour and other eligibility factors before making a lending decision.
Getting a new loan after a loan settlement may require borrowers to take some steps to strengthen their financial profile. One should review their credit history, understand their financial profile, and assess their settlement status. The following steps may help them to prepare for a new loan:
Getting a new loan may require a lender’s approval and assessment. The borrower must review the new loan's terms and conditions to ensure that the repayments are within their financial capacity.
Borrowers should understand the financial and credit-related implications of loan settlement before proceeding. These are the following impacts:
Borrowers must understand the impacts of the loan settlement before proceeding with it. They need to assess the important terms and conditions before agreeing to the loan settlement.
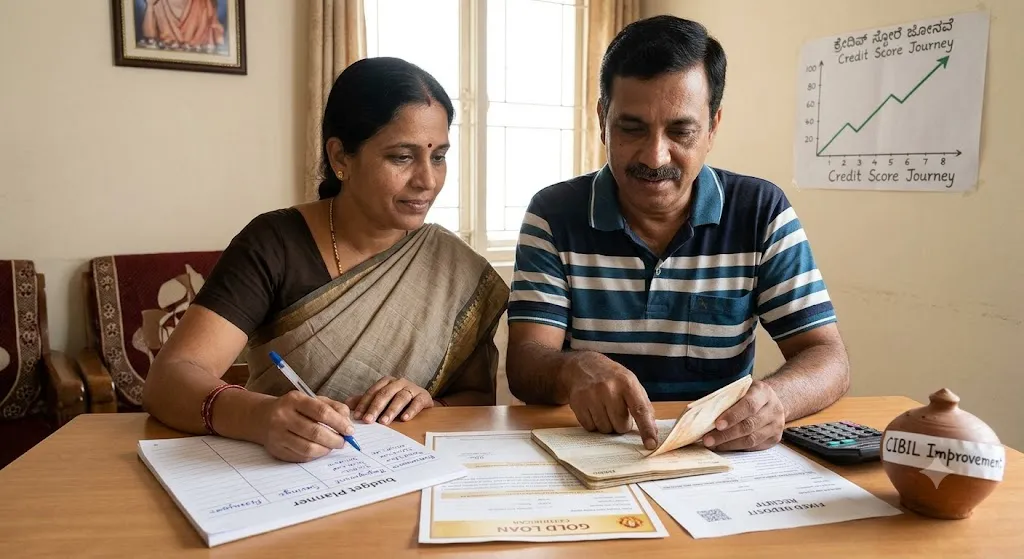
Getting a loan after a loan settlement can be challenging. This is because loan settlement can negatively affect a borrower's credit report and score. However, getting a new loan is not impossible. Borrowers can improve their chances of approval by focusing on the following factors:
Getting a new loan after a loan settlement requires financial planning and patience. But the borrower needs to keep focus on maintaining financial stability before considering another loan. This may help borrowers prepare for future borrowing needs.
After completing a loan settlement, borrowers should remain careful about their financial and documentation responsibilities. The following precautions may help them keep proper records and manage any future queries related to the settled loan:
After completing the agreed settlement payment, obtain a settlement confirmation letter or receipt from the lender as proof of settlement. If the remaining dues are subsequently paid in full, request a No Dues Certificate from the lender.
The borrower needs to know the difference between a closed loan and a settled loan. The credit report may show the closed loan remark when the borrower pays the complete outstanding loan amount to the lender, including interest. A ‘Settled’ remark indicates that the borrower has paid the reduced amount agreed upon with the lender to resolve the outstanding loan.
Review your credit report after settlement to ensure that the loan status has been updated accurately. If you find any incorrect information, contact the lender or credit bureau to raise a dispute and request the necessary corrections.
Applying for unsecured loans or credit cards soon after settlement may be challenging, as lenders may consider your recent settlement history while assessing your creditworthiness. Focus on improving your credit profile before seeking additional credit.
By avoiding these mistakes, you will be able to carefully handle the post-settlement period. Ensure that you keep the relevant documents about your credit history secure. This may help to prevent confusion and help with financial planning.
Loan settlement can have long-term implications for a borrower's financial profile. Understanding its impact and taking the right steps afterwards can help borrowers work towards better financial stability. Before considering another loan, assess your borrowing needs and repayment capacity. If you are exploring personal loans or debt consolidation options, LoansJagat can help you compare available lending options from its network of lending partners. Visit LoansJagat to explore suitable borrowing solutions.
Depending on your lender's policies, you may have options such as loan restructuring, new payment terms, payment holidays, or debt consolidation.
People usually choose to settle a loan when they are experiencing severe financial hardship and cannot afford their upcoming instalments.
Loan settlement may help reduce a borrower's financial burden during financial hardship. The borrower's obligations are determined by the settlement terms and payment of the agreed amount.
Loan settlement may impact your credit score because the credit report will mark the loan account as a settled account, not a closed account.
Borrowers can apply for a new loan after settlement, but approval depends on the lender’s assessment and lending criteria.
Loan settlement is the mutual agreement between the borrower and a lender to reduce repayment of the outstanding loan amount. Whereas loan consolidation refers to combining multiple existing loans or debts into a single loan.
A loan marked as ‘Settled’ may be updated to ‘Closed’ if the borrower pays the remaining amount waived during the settlement, subject to the lender’s approval and terms.
After completing a loan settlement, borrowers should obtain written confirmation of the settlement from the lender. An NOC or NDC may be issued subject to the lender's policies and the status of any remaining dues.
Loan settlement is a recognised arrangement between a borrower and lender in India, subject to applicable laws and the terms agreed upon by both parties.
Loan settlement can affect your credit report for an extended period. Although borrowers can take steps to improve their credit scores, this does not automatically remove the ‘Settled’ remark from their credit reports.
Start your journey today
Apply Now*T&C apply