What Legal Actions Does Personal Loan Defaulters Face In India? Check RBI’s Guidelines
Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Anishka Bhadly is a content writer with a finance and business background. She has completed her bachelor's degree with a specialisation in finance and is currently pursuing an MBA in the finance field too. The knowledge she has gained from her studies and experience working with EdTech companies helped her combine theoretical knowledge with practical industry insight. Her expertise lies in creating well-researched, informative, and reader-friendly content in various banking, personal finance, loans, insurance, and investment-related topics.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
If you miss payment of your personal loan EMI, it can cause a stressful situation. You may be unclear on how your lender can act. A missed payment will not result in any criminal action occurring or you being considered a wilful defaulter immediately. However, if payments are not made, you may end up affecting your credit rating and causing problems with your lender. Understanding RBI guidelines and how loan defaults occur can help you make informed financial decisions. It is also important to know the possible legal implications to avoid further financial difficulties.
Key Takeaways:
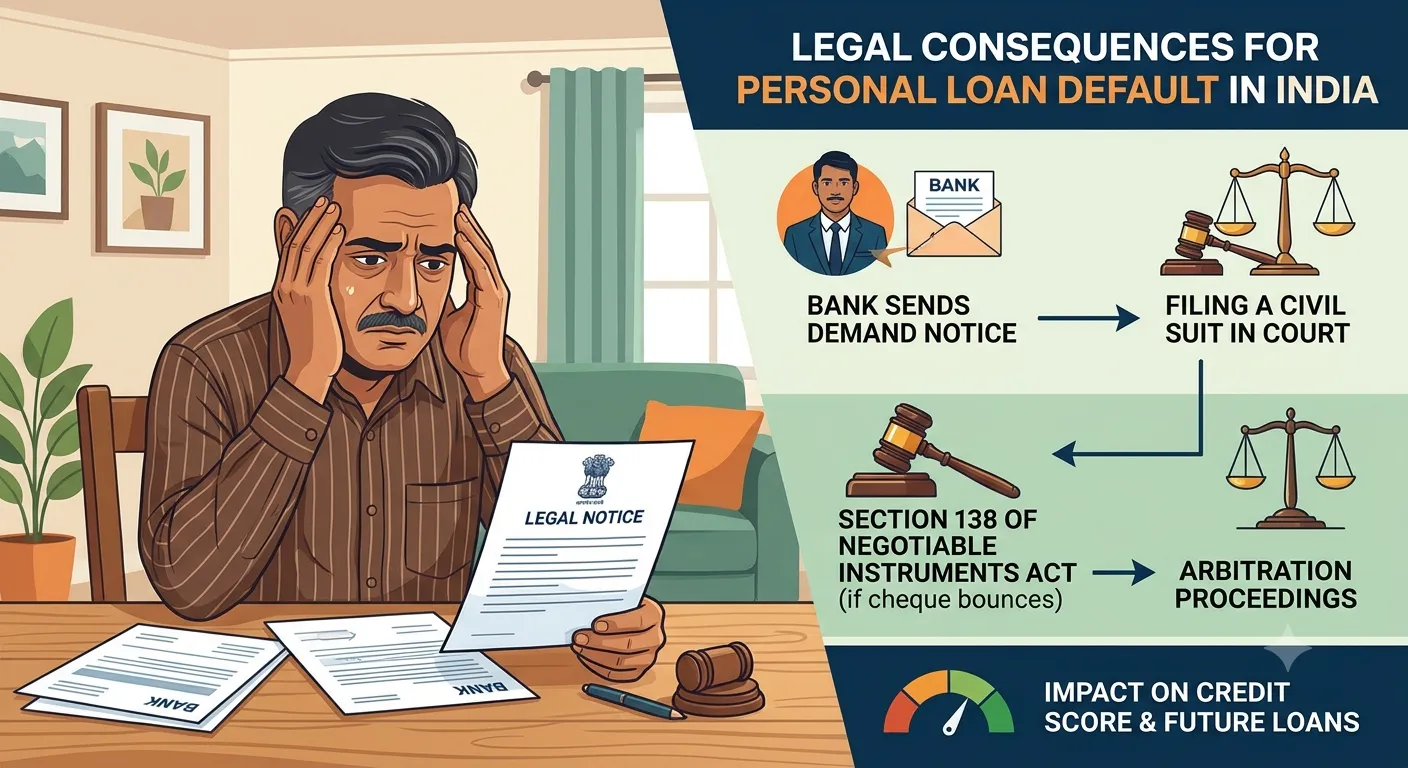
Banks can take various legal as well as financial steps to recover the outstanding dues from borrowers who have been identified as wilful defaulters.
Where facts and law so require, the bank can take criminal action against such borrowers. These actions can be taken even if the borrowers have been removed from the list of wilful defaulters.
The banks can publish the photos of wilful defaulters as per policy (non-discriminatory) approved by the board.
No additional credit facilities can be granted to a wilful defaulter or any entity associated with them, as defined under the RBI Directions. This includes denial of credit facilities for a period of 1 year from the date of removal from the LWD list. Also, there will be no new credit facilities provided to them for a new venture for 5 years from the date of their removal.
Banks must incorporate a covenant in credit agreements requiring borrowers not to appoint individuals whose names appear on the List of Wilful Defaulters to their boards or management. If such an individual is found in these positions, the borrower must take steps for their removal.
Legal action can be initiated by the banks against the borrowers and sureties to recover the dues or to enforce foreclosure.
These steps provide banks an opportunity to deal with wilful defaulters, deny them fresh credit facilities and also ensure that they recover their dues through appropriate legal measures.
As per RBI’s guidelines, a wilful default occurs when a borrower deliberately fails to repay a loan despite having the ability to do so. It also includes diverting or siphoning borrowed funds, disposing of secured assets without the lender’s knowledge or approval, and failing to fulfil an agreed equity infusion commitment despite having the financial capacity. A wilful default can have more serious consequences than an ordinary loan default because it may involve stricter action by the lender. This rule applies to individuals, companies, and other such business entities who have taken loans from banks or financial institutions.
A person will be considered a wilful defaulter if they have:
Being a wilful defaulter is worse than being a loan defaulter. It can lead to uncertain and stricter legal actions, making it difficult for you to get loans in the future. If you are marked as a wilful defaulter in the official documents, it can cause serious damage to your financial reputation.
A borrower may be considered a defaulter when they fail to meet their repayment obligations as specified in the loan agreement, including missed EMIs, overdue interest or other required payments. Banks have certain guidelines provided by the Reserve Bank of India. These include SMA classifications and NPA status. The following table describes how they would categorise the repayments of a typical bank term loan.
These classifications enable lenders to understand if there are issues with repaying the loan and can take the appropriate steps to recover the debt. Being classified as an NPA can affect your chances of borrowing in the future, so you should contact your lenders as soon as you expect issues with your EMI. Talking through the options available to repay may help prevent further issues.
Note: This is for typical bank term loans. The RBI has different rules regarding income recognition and asset classification for other credit facilities. NPA does not mean that criminal action will be taken or that you will need to settle the loan.
Your credit score plays an important role in your finances. You can be a good person in real life, but if you have a bad credit score, lenders will judge you based on your credit score. Here is how a loan default can affect your credit score:
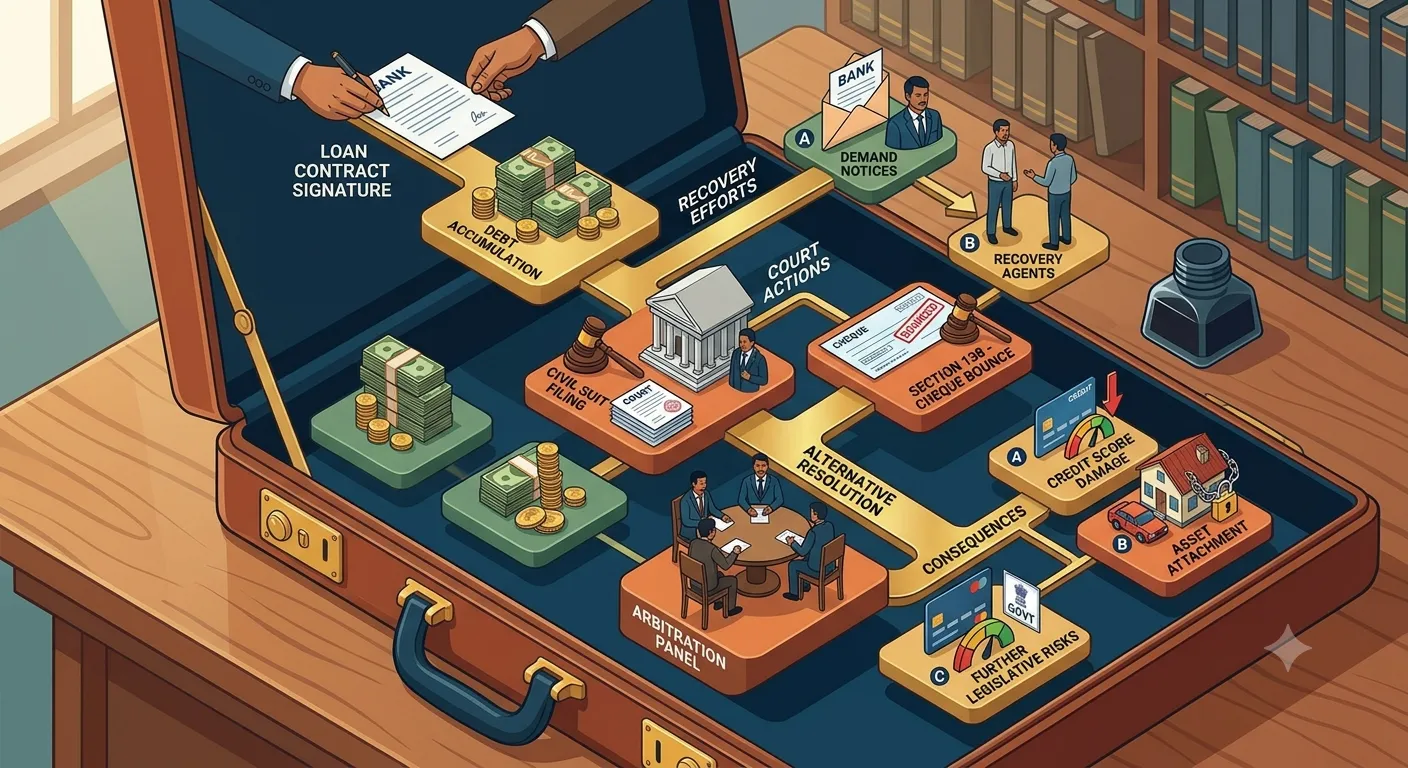
A loan defaulter can create serious repayment issues while affecting your financial future for many years. It is important to maintain your credit score to raise your chances of getting a loan when you need it.
Defaulting on a loan could affect your ability to get any credit in the future. As you will be seen by lenders as a risky borrower, you may struggle to gain any loans on good terms.
Whilst a loan default could affect your borrowing options, it can be improved over time by paying off any outstanding debts and paying your EMIs on time in the future.
Sooner or later, the loan defaulter list will follow you if you avoid paying your EMIs on time. Not only does it affect your credibility, but being a defaulter can also pull you into financial stress, lower your credit score, and lead to major consequences. This is exactly where LoansJagat will help you:
The main purpose of LoansJagat is to be a financial guardian angel for their customers. Our team will help you manage repayment, find suitable loan options, and make it easier for you to repay the existing loan.
A personal loan default can affect your credit rating and the types of loans you can take out in the future. Not making your EMIs may make matters worse. Contact your lender as soon as you are having difficulty repaying your loan. This allows you to discuss solutions to the problem. Make sure you keep up to date with how much you are in arrears, know what you need to pay back, and do not get into more debt than you can afford. By acting promptly, you can ensure you are managing your current debt.
Missing a loan payment may affect your repayment history and could lead to late payment charges, depending on your loan agreement and the lender's fee schedule. Your lender may also contact you regarding the overdue amount. To avoid further complications, clear the outstanding payment as soon as possible.
Yes, banks can take legal action to try and receive any overdue payments. This will depend on the situation and any relevant laws. Not all situations that involve loan default will result in criminal action.
No; however, if there was any fraudulent activity, cheating or other offences involved, then there could be criminal action.
Typically, bank term loans will be classed as NPA if they have had any overdue principal/interest for over 90 days.
Yes, missing or delaying payments can cause your CIBIL score to drop. This will depend on your repayment history.
Yes, however, it may be difficult to get approved. Lenders will look at your credit report, your ability to repay, any debts you may have, and your current eligibility.
It depends on the credit information regulations of the country. It will depend on what information is provided by the credit bureau. Please check your credit report to see what they have mentioned.
Recovery agents must comply with RBI's fair practices and recovery-related instructions. They must not intimidate or harass borrowers or intrude upon the privacy of their family members.
Before you miss any payments, please speak with your lender to explain why you are unable to make payment. They will be able to tell you what options are available. You can also look at your monthly outgoings to work out how much you can repay.
Yes, you can, if you cannot repay the full amount owed you can speak to your lender and come to an agreement to settle your loan. However, this may be marked as settled rather than closed on your credit report. This can affect your ability to borrow in the future.
Start your journey today
Apply Now*T&C apply