Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
A zero-interest credit card EMI offer, also called a no-cost EMI offer, allows you to spread the cost of an expensive purchase across smaller monthly instalments. Under this offer, the interest cost is offset as per the applicable terms and conditions. However, other charges may apply. While shopping for a new phone, laptop, or home appliance, you may have come across a credit card offer providing a no-cost EMI option.
Key takeaways
A No-Cost EMI ensures that the purchase amount is broken into instalments as per the terms of the offer. This facility may help you manage your finances while indulging in the latest mobile phone or shopping for a new refrigerator. The entire amount due for the purchase can be divided into easy monthly instalments, with the interest rate depending on the policies. It is a convenient way to buy expensive items without putting a strain on your monthly finances.
Zero-interest EMI on a credit card divides the purchase amount into smaller instalments for eligible products. This may allow buyers to pay over a period instead of making a lump-sum payment. The division of the payment amount is done based on the terms and conditions of the credit card issuer.
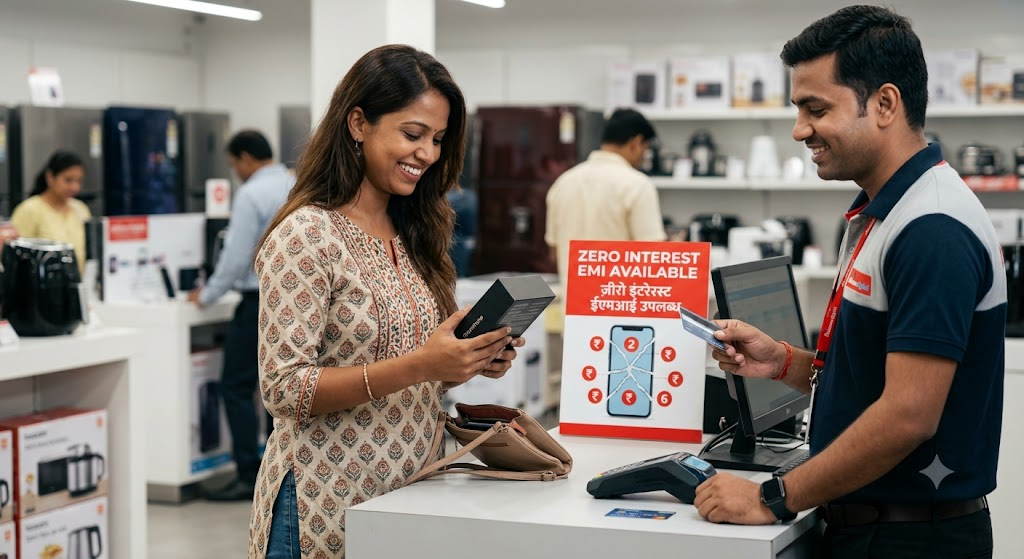
Choose the product or service (e.g., smartphone, laptop, etc.) that you are looking to purchase using a no-cost EMI.
While purchasing, select the No-Cost EMI option if it is available for your chosen product. The available repayment tenures (e.g., 3, 6, 9, or 12 months, etc.) may vary based on the merchant, product, and credit card issuer.
Upon choosing the No-Cost EMI option, the transaction is subject to approval by your credit card issuer. The purchase value is then converted into EMIs. The interest component, where applicable, is generally offset by a discount offered by the merchant or brand against the cash purchase price.
You can repay the purchase value in the form of monthly instalments due over the selected tenure. Processing fees and other charges may apply, depending on the offer and card issuer's terms. GST may also apply to the interest component, if any.
A No-Cost EMI option allows eligible purchases to be paid in monthly instalments. The repayment period depends on the offer terms. However, it is always recommended to carefully consider the terms and applicable charges for an offer before availing it.
This is how zero-interest credit card EMI works, depending on the options available for the selected product.
The difference between zero-interest EMI and regular EMI is very broad in terms of interest charged, interest payable, processing fees, etc. The differences are as follows:
Hence, these are some of the key differences between the regular EMIs and the no-cost EMIs on credit cards.
When using a credit card for a no-cost EMI or zero-interest EMI purchase, it is important to know its advantages and disadvantages. This can be related to interest charges, additional charges, budgeting, etc.
These are the major pros and cons of the zero-interest credit card EMI that one needs to know before choosing this option when making any purchase, as per availability.
Zero-interest EMI can help you manage your finances on huge purchases. With this, you can avoid a huge one-time payment and instead pay small amounts every month as instalments. The bank may charge interest, which the merchant or brand may offset through a discount or cashback. However, certain processing charges and taxes may also apply. Go through the terms and conditions of the offer before choosing zero per cent EMI as a payment method.
A no-cost EMI facility on a credit card allows you to repay eligible purchases in multiple instalments, with the interest component offset as per the applicable offer terms. However, additional charges may apply based on the issuer’s terms and conditions.
No-cost EMI cannot be considered completely free, because there can be hidden charges as per the credit card issuer’s terms and conditions.
Zero-interest EMI is available on selected products, depending on the merchant’s offer and the credit card issuer’s terms and conditions.
No-cost EMI could be a good choice if the interest is negated in the form of a discount and other charges are minimal. It depends on the rate of interest, repayment period, and special offers on different payment methods.
Yes, no-cost EMI and zero-interest EMI on a credit card are the same.
You may be able to repay the outstanding No-Cost EMI amount early. However, this is generally treated as foreclosure or pre-closure and may attract additional charges, depending on the card issuer's terms.
Choosing No-Cost EMI does not necessarily affect your credit score negatively. However, missed or delayed repayments may affect your credit score, depending on the issuer’s reporting to credit bureaus.
Banks offer a zero-cost EMI feature on their credit cards for multiple reasons, like boosting sales, attracting new cardholders, etc.
No-cost EMI may involve an interest offset through a discount, depending on the offer terms. It also allows the purchase cost to be divided into monthly instalments.
Additional charges on a zero-interest EMI purchase may include processing fees, GST on applicable fees or interest components, and other charges specified by the credit card issuer or merchant.
Start your journey today
Apply Now*T&C apply