By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
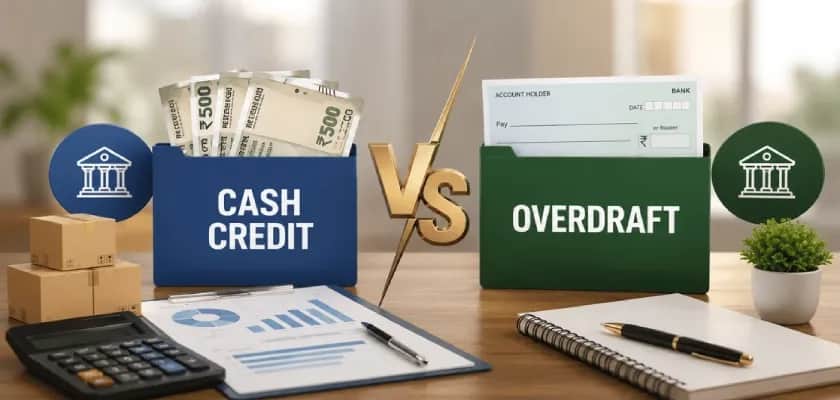
While contrasting Cash Credit vs Overdraft, it can be said that neither option can be called better or worse in absolute terms since each type has its own purposes. Cash credit seems more appropriate for businesses that need continuous working capital, while overdraft is more appropriate for people who want to cover a temporary lack of money.
Despite the fact that these financial products can offer fast access to money, there are still differences regarding limits of borrowing, calculation of interest, repayment process, conditions of obtaining and other features. Learning about these peculiarities is very important since it can help to make the right choice and ensure efficient financial management.
Whichever financial situation you have as a business person or an individual, the choice of the right financial product is important. This article will tell you about key differences, working principles, pros and cons of Cash Credit vs Overdraft.
Key Takeaways
Cash credit and overdraft facilities allow both individuals and companies to meet their short-term financial needs. Nonetheless, there are some differences in how such facilities work. In order to understand the difference between Cash Credit and Overdraft, you will have to consider what each facility entails.
Cash credit is a short-term borrowing facility extended by banks in order for the borrowers to be able to pay for their daily expenses. The borrower is free to withdraw cash as long as he or she sticks to the agreed limit.
The following are some characteristics of cash credit:
The main objective of cash credit is to facilitate the smooth running of business activities.
An overdraft facility permits withdrawal of more money than the balance in a bank account, subject to a certain fixed limit.
Some of the features of an overdraft facility are as follows:
It is a quick source of funds without applying for a loan each time funds are required.
Also Read: Overdraft Loan vs. Personal Loan: Key Differences Explained
The following table highlights the major differences between Cash Credit vs Overdraft:
The ideal option depends on financial needs, repayment capacity, and purpose.
Knowledge of the working procedure of Cash Credit and Overdraft facilities will assist borrowers in using these finance tools better. Although both the methods offer easy access to funds, there is a vast difference between the two when it comes to their working mechanisms.
Cash Credit facilities are basically meant for meeting the working capital requirements of companies. The banks first analyse the financial situation of the borrower to arrive at a borrowing limit.
The following are the basic steps involved in this process:
After the limit is fixed, companies have the liberty to withdraw funds anytime, as long as the total amount withdrawn does not exceed the sanctioned limit. Interest is payable only on the amount borrowed, but not on the entire limit sanctioned.
The Cash Credit facilities are offered for a fixed tenure and are usually extended yearly.
An overdraft service is usually associated with savings and current accounts where the client can take money out even if there is not enough money in his account. Overdraft services can be granted against fixed deposits, real estate, securities, salary accounts, and many other eligible assets depending on bank policy.
The working process comprises the following:
*T&C Apply
Interest is paid by the customer only on withdrawals made in excess of account balance. Depending upon the type of overdraft facility, the repayment process varies.
The majority of the overdraft facility is usually a short-term facility.
It will be easy for individuals to understand the merits and demerits of Cash Credit as compared to Overdraft facilities to make well-informed decisions regarding finances. Though Cash Credit and Overdraft both give a quick way to access money, there are certain differences among them based on their requirements and repayment conditions.
Businesses have opted for cash credit for a long time as it enables maintaining a sufficient amount of working capital and helps with business operations.
Firms which have few assets find it hard to get high credit limits.
An overdraft service is where account users can easily gain access to extra finances at any time of their choosing.
Overdrafts are used by individuals and organisations for emergency purposes.
Similar to any other financial instrument, there are also some drawbacks to an overdraft facility.
Taking into consideration the above-mentioned aspects, one will be able to choose the best financing instrument.
Cash credit and overdraft facilities are both useful financial instruments that help meet the requirements of short-term finance. Although cash credit is more appropriate for those firms that need regular working capital, an overdraft facility is very helpful in dealing with cash crunch situations. The difference between these two financing methods would help borrowers in choosing the appropriate method based on their finances.
Yes, a borrower is entitled to make use of both the facilities provided that his applications get approval from the lender. It is common practice to avail of cash credit for the payment of operational costs and an overdraft facility for meeting unforeseen financial obligations.
Yes, timely repayments and good credit behaviour will have a positive impact on the credit score. On the other hand, late payments and excess borrowing could lead to a lowering of creditworthiness.
Yes, there is a provision for a bank to withdraw or withdraw an overdraft facility at a given time. This can be done when the terms of the account are violated or where repayments become problematic.
It is recommended that businesses periodically conduct reviews of the financing needs to ensure that their sanctioned cash credit limit corresponds to their actual needs.
The limit of the cash credit account can be enhanced in case the borrower's performance level increases. The banks consider revenue growth, repayment history, and the value of the collateral provided before agreeing to enhance the limit.
Self-employed people can apply for an overdraft facility if they comply with all the requirements set by the bank.
In case the sanctioned limit is exceeded, the bank will charge additional fees, penalties, or even refuse to carry out the transaction.
Yes, almost all banks offer internet banking and mobile banking services to their customers to help them track their balance and transaction history. Also, it is easier for them to make payments using these services.
Yes, there could be processing fees, documentation fees, and renewal fees. However, it depends upon the bank’s policy and the chosen facility.
Yes, seasonal businesses can use such facilities because of the fluctuating cash flow.












