By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Anishka Bhadly
Anishka Bhadly is a content writer with a finance and business background. She has completed her bachelor's degree with a specialisation in finance and is currently pursuing an MBA in the finance field too. The knowledge she has gained from her studies and experience working with EdTech companies helped her combine theoretical knowledge with practical industry insight. Her expertise lies in creating well-researched, informative, and reader-friendly content in various banking, personal finance, loans, insurance, and investment-related topics.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
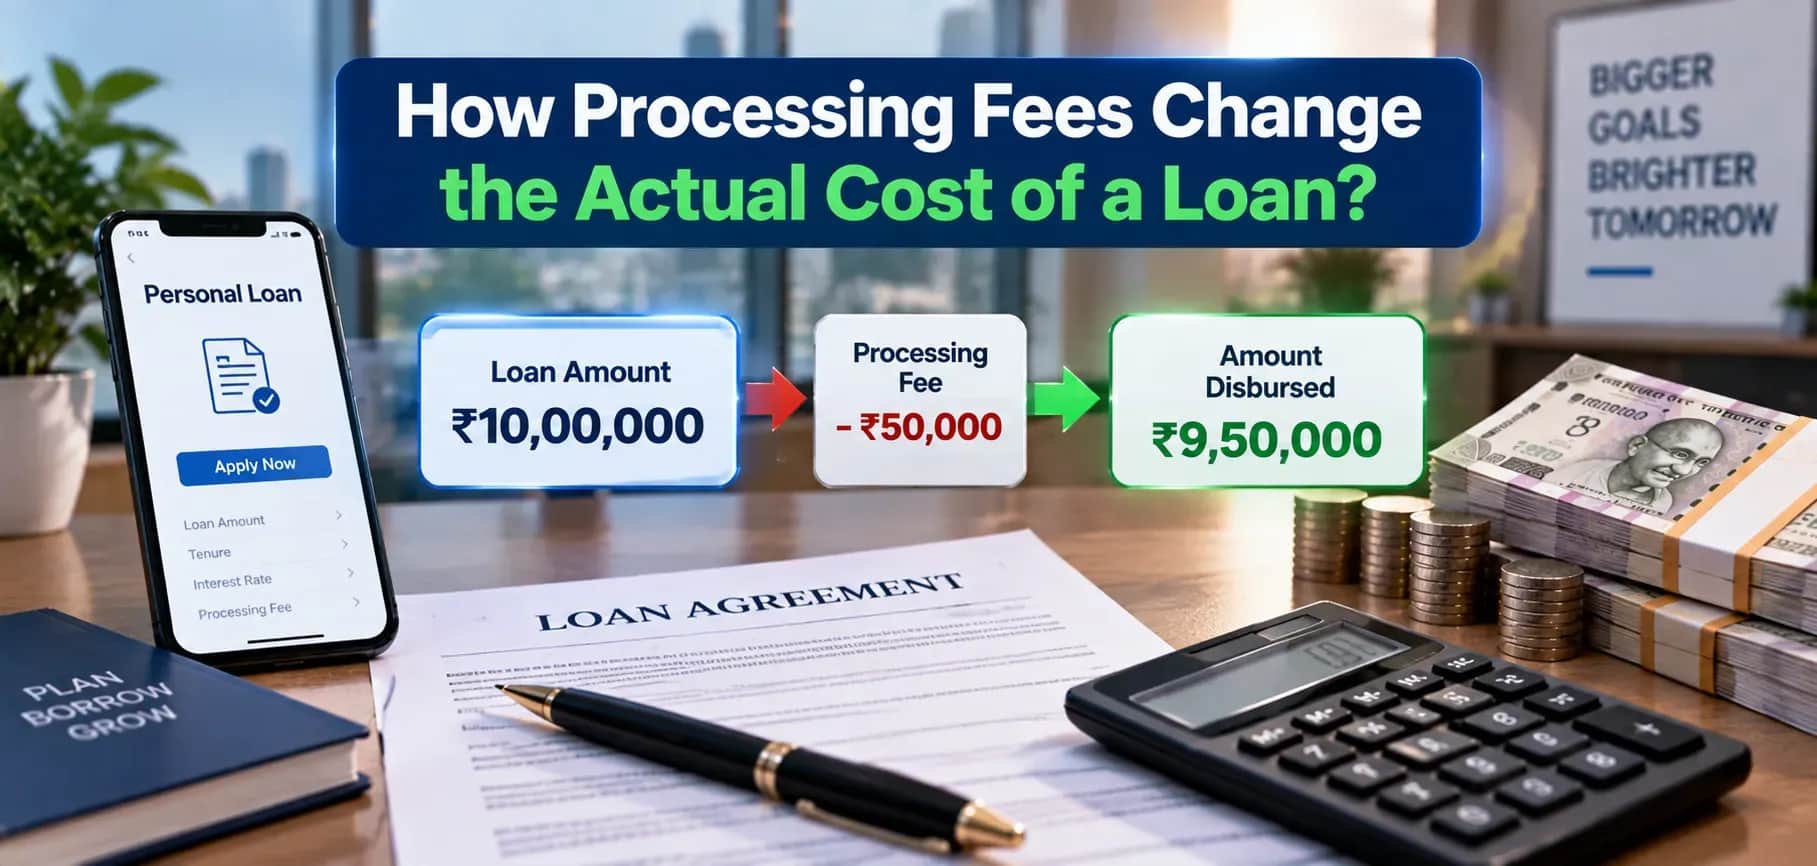
Processing fees make the loan more expensive since they represent additional sums of money that a borrower pays to a lender for processing and for giving out the loan. Therefore, such fees may decrease the amount of money that a borrower actually receives and increase the cost of a loan. The interest rate that is advertised is usually not the only cost associated with a loan. Thus, considering processing fees, taxes, an interest rate, additional costs, and the amount of money that one will be obliged to pay back, a borrower will be able to choose the best loan option. Also, comparing the annual percentage rate, or APR, and key facts statement will enable a borrower to determine the cost of a loan and make the right choice.
Key Takeaways:
A processing fee is a one-time payment that is charged by a lender for approving a personal loan to somebody and closing the loan. This fee is applied for costs incurred while screening, analysing, and processing the loan, so this is a convenient way for the business to cover expenses related to documentation and credit checking. The timing and manner in which the processing fee is collected will be determined by the lender and the specific terms of the loan agreement. It can either be collected separately or deducted from the amount of money that has been disbursed. Comparing the processing fee of different institutions for personal loans can allow one to get a cheaper rate for the service.
The processing charge can sometimes make your loan much more expensive than it actually appears. There are various fees that determine the overall cost of the loan, some of which are listed below:
One would need to be wary of the overall cost of the loan, including the processing fee. The interest rate is not the actual representation of the cost of the loan. One should calculate the APR (Annual Percentage Rate) of the loan, taking into account every expense mentioned above, in order to compare the offers of the different lenders.
A personal loan, besides the interest rate and EMI, may include several other charges such as processing, foreclosure, and maintenance charges. Knowing what the charges mean and how they can affect your repayment tenure helps you understand the actual cost of the loan and compare different lenders. Here is a breakdown of the various charges:
*T&C Apply
Now that you understand the various charges that apply to your personal loan, you can compare and evaluate the total cost of the loan. Do not forget to consider the interest rate and processing fees before applying for a personal loan.
A loan’s interest rate isn’t the only factor that makes up its total cost. Processing fees, taxes that may apply to the loan, and other charges may add to the amount you’ll ultimately pay and lessen the amount you actually get. Always read the Key Facts Statement, compare the APR, calculate the net amount of money you get to pay off the loan, and make sure of the overall amount owing back to you. Occasionally, a slightly superior interest rate which incorporates reduced fees could potentially work out as a lower overall cost option than a loan with a reduced rate yet increased fees.
What is a processing fee on a personal loan?
A processing fee is a charge that the lender levies against the borrower for processing and scrutinising the loan application. These fees may include verifying and processing the documents, clearing credit reports, and other administrative tasks.
What are foreclosure charges on a personal loan?
The prepayment or foreclosure charges are the costs the lenders levy against the borrower while paying off the personal loan before the assigned tenure. Therefore, one should enquire about the charges beforehand on closing the loan before the maturity date.
Are processing fees refundable?
The processing fees are usually non-refundable, and each lender has its own policy about it. Therefore, one should check the terms and conditions and clarify all doubts before signing the loan agreement and paying the demand draft.
Do I have to pay GST on a personal loan processing fee?
Yes, GST is applicable on the processing fee in a personal loan, which is generally 18%. The amount of GST payable depends upon the processing fee that a lender levies and the tax rate, which is constant. GST may be applicable on other charges as well that the lender levies on a customer.
Can processing fees cut into the loan amount I receive?
Yes, the processing fees can reduce the amount of the loan one receives. If the lender deducts the processing fees along with the taxes from the loan amount, one will receive less money than the sanctioned amount.
What are maintenance charges on a personal loan?
Some lenders charge maintenance charges for certain personal loan products or services. It depends on the lender whether they levy such charges or not.
How can one reduce the cost of a personal loan?
One should compare the interest rate, processing fee, taxes, foreclosure charges and the overall amount to be repaid. One can find the most reasonable deal by comparing the overall cost of taking a personal loan.
Is the interest rate the only deciding factor while choosing a personal loan?
No, the interest rate is not the only deciding factor. One needs to consider processing charges, taxes, foreclosure charges and other applicable charges and then decide the total cost of the loan.
How will an EMI calculator help in choosing the loan?
An EMI calculator will help a borrower to get an idea of the monthly instalment that he needs to pay, the total amount that will be paid as interest and the overall amount of repayment. By using an EMI calculator, one can determine if the loan repayment fits in a budget or not.
While applying for a personal loan, what are the key elements to look at?
The key elements to look at are the interest rate, processing fees, applicable taxes, other charges, foreclosure charges and the overall amount to be repaid. By understanding these elements, it becomes easier to avoid getting surprised at the total cost of the loan at the end.












