
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
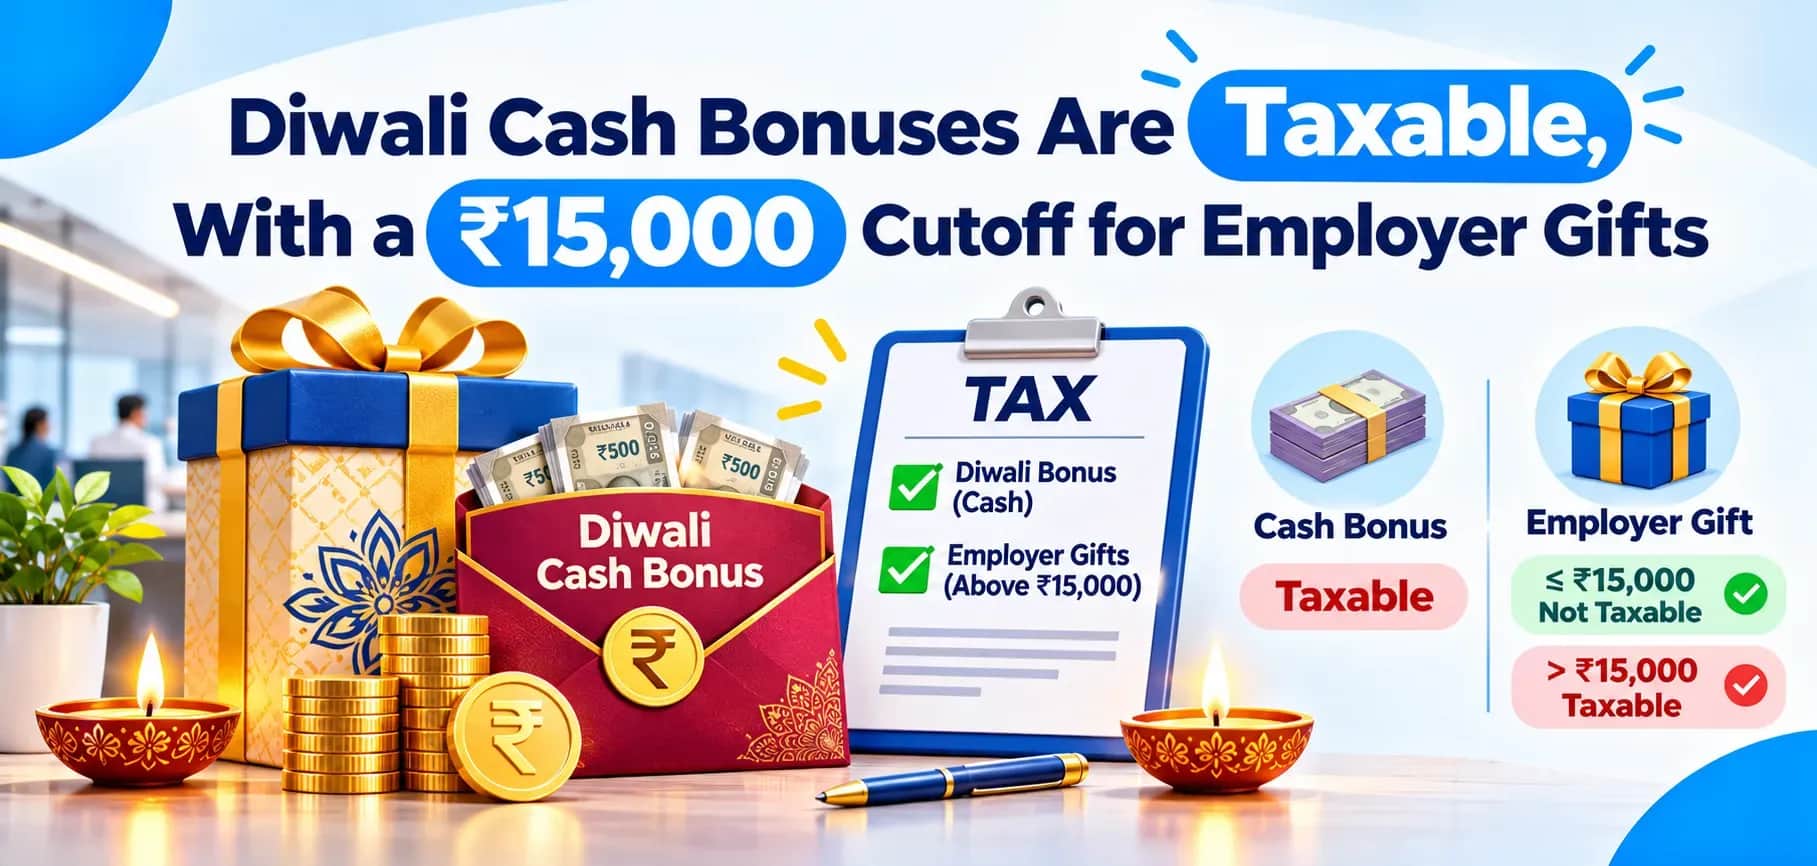
A Diwali cash bonus counts as salary. The tax exemption for qualifying employer gifts and vouchers applies only to yearly totals of less than ₹15,000.
A Diwali cash bonus paid to an employee in India in November 2026 goes into that year’s salary income. A shopping voucher from the same employer can have a taxable value of zero. Payroll looks back to 1 April. It counts the voucher alongside any qualifying gifts the employer has given to the employee or their household members since then.
For the tax year ending 31 March 2027, the exemption covers annual gift totals below ₹15,000. The previous exemption limit was ₹5,000 or less. The higher threshold took effect on 1 April 2026, when the Income-tax Act, 2025 and the Income-tax Rules, 2026 came into force.
Rule 15 covers qualifying gifts, vouchers and tokens given to an employee or a member of the employee’s household. A gift can count towards the total even if it was given outside a festival or ceremony. Mint gives the example of an employee who receives a ₹9,000 festive voucher and a ₹5,000 shopping voucher. At ₹14,000 for the year, both vouchers are tax-free.
At ₹14,000, the employee has room for less than ₹1,000 in further qualifying gifts. If the employer gives another ₹1,000 voucher by 31 March 2027, payroll treats the entire ₹15,000 as a taxable perquisite, or employment benefit.
The bonus goes into salary income whether the employer pays it in cash, by cheque or by bank transfer. Mint’s 10 November report also treats cash gifts and gifts that can be converted into money, such as gift cheques, as taxable. The employee’s final tax bill depends on annual income, eligible deductions and the slab rates and rebates under the chosen old or new tax regime.
An eligible resident employee earning only a salary owes zero income tax under the new regime on gross pay of ₹12.75 lakh. After the ₹75,000 standard deduction, taxable income is ₹12 lakh. At that amount or below, section 156 of the Income-tax Act, 2025 provides a rebate of up to ₹60,000.
The employee in Mint’s example keeps the rebate after receiving a ₹50,000 Diwali bonus. The payout takes the ₹12 lakh annual salary to ₹12.50 lakh in gross pay. Subtracting the standard deduction leaves ₹11.75 lakh in taxable income. If a bonus pushes taxable income just over ₹12 lakh, marginal relief may reduce the extra tax.
The payslip records the cash bonus and any taxable gifts. It also shows how much tax was deducted at source (TDS). Employers account for taxable amounts when calculating salary TDS. Form 130 replaces Form 16 as the salary TDS certificate for tax year 2026–27. Employees can check the certificate against their payslips before filing. Those with only salary income have a statutory filing deadline of 31 July 2027.
Any qualifying voucher received by 31 March 2027 goes into the year’s gift total. Employees who received a cash bonus need to include it in annual salary. Under the new regime, the payout may change the final tax bill for employees close to the ₹12 lakh rebate limit.
Yes. Payroll counts the entire Diwali cash bonus as taxable salary, even below ₹15,000. The final tax bill is worked out on total income under the employee’s tax regime, taking into account any deductions or rebate they qualify for.
Yes. A qualifying shopping voucher can have a taxable value of zero if its value, together with that of other qualifying gifts, vouchers and tokens received from the employer during the tax year, stays below ₹15,000.
Yes, if the spouse is a member of the employee’s household. A ₹4,000 voucher sent to the spouse and an ₹11,000 hamper given to the employee bring the total to ₹15,000. The full amount is taxable.
Yes. An eligible resident individual in the new regime can still qualify for the rebate if total taxable income, including the bonus and after eligible deductions, stays within ₹12 lakh and all income is taxed at slab rates.
If the employer deducted tax from salary for tax year 2026–27, the due date for issuing Form 130 is 15 June 2027. Employees can use the certificate to check the salary and tax deductions reported by payroll.
Start your journey today
Apply Now*T&C apply











