
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
EPFO can process eligible claims in about a day, but for claims to be automated the right KYC, an active UAN, and correct bank information are mandatory.
The Employees’ Provident Fund Organisation expects most fresh PF claims to be settled on the same day or within 2 days under its new centralised processing system. Central Provident Fund Commissioner Ramesh Krishnamurthi announced the target on 31 July 2026 at the Global Industrial Relations Summit in New Delhi. The change concerns EPFO members across India and could speed up access to savings during illness, unemployment, education expenses or a housing payment. A Press Information Bureau update dated 4 August 2026 later reported near-same-day settlement for most eligible claims processed by EPFO’s Kochi office through CITES.
In the short term, a verified claimant may receive money before an urgent bill becomes overdue. Over time, central processing could reduce office visits and employer follow-ups. The popular “24-hour claim” description has a downside. It may create a fixed expectation when manual checks are still required. EPFO has not announced a universal 24-hour payment guarantee, and bank credit can take longer after approval.
A provident fund advance often arrives during an awkward week. A hospital may ask for a deposit before treatment. A worker between jobs may need rent and school fees together. Faster processing gives eligible members earlier access to their savings without taking a short-term loan. For a household on a thin budget, even 3 or 4 fewer working days can change when a payment gets made.
CITES also removes an old location problem. An employee may have worked in Jaipur, shifted to Pune and filed a claim after moving to Bengaluru. Centralised processing reduces dependence on the original regional office. That should help migrant workers and employees who changed jobs several times, provided their records connect to the same UAN.
LoansJagat’s analysis is that faster settlement changes cash timing, not claim eligibility. A member should not promise a hospital, landlord or school that PF money will arrive the next day merely because the account is KYC-linked. Its online PF withdrawal guide, published on 9 July 2026, also points members towards UAN activation, linked KYC and the correct online claim route before submission. That preparation is still the safer approach.
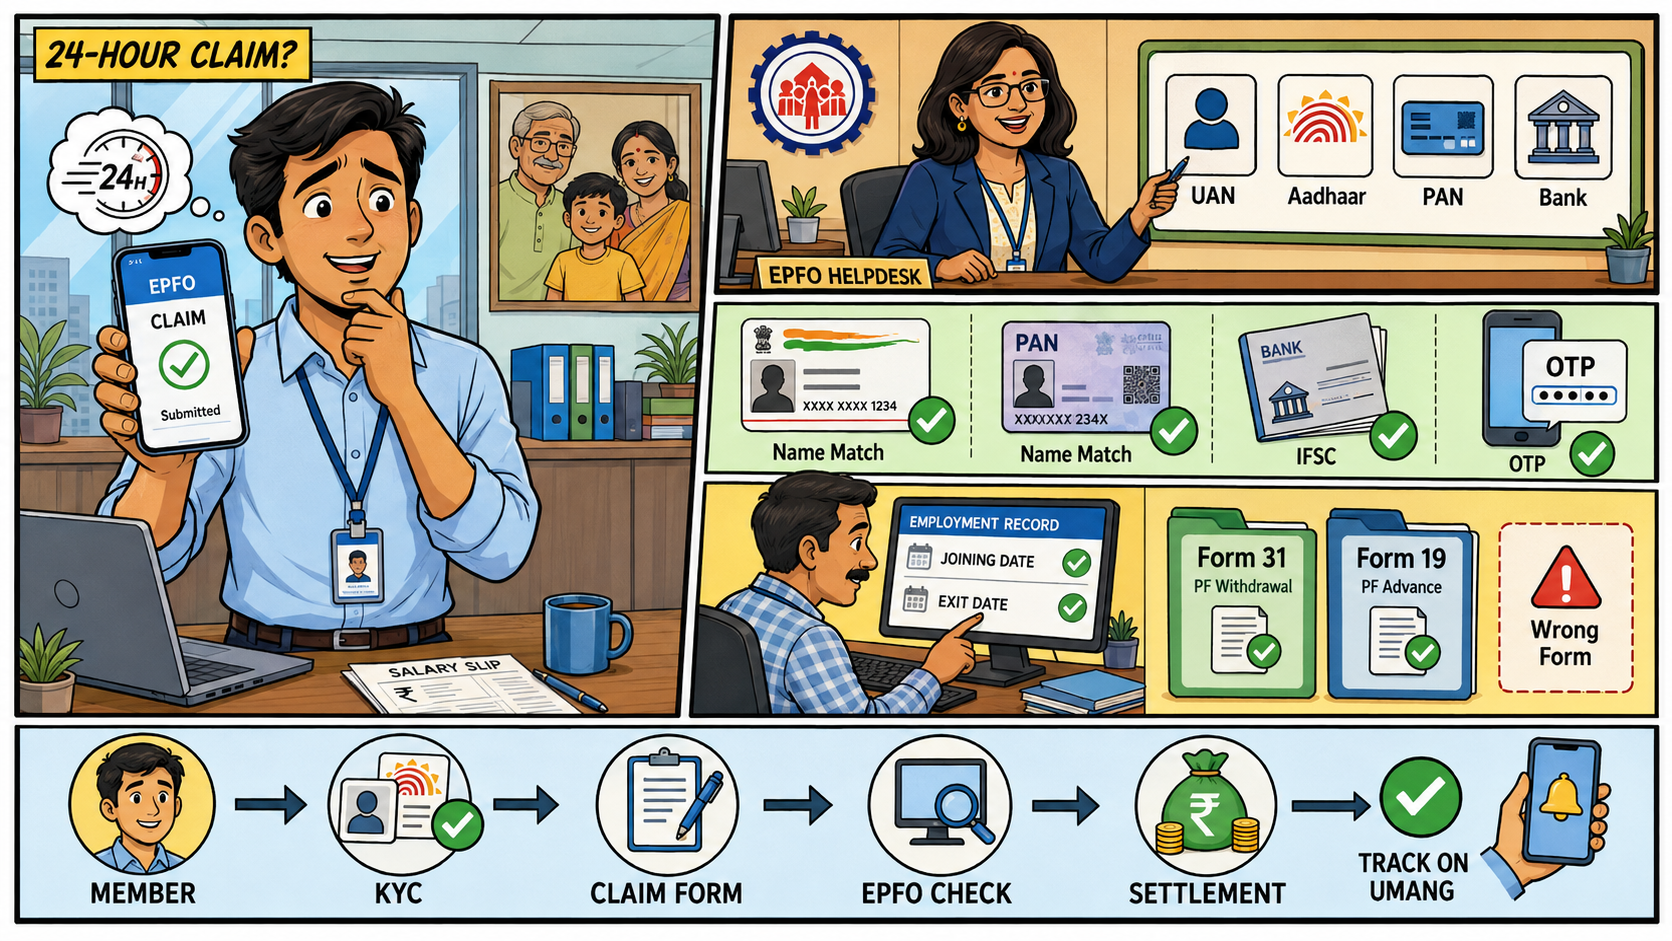
EPFO’s official website asks online claimants to link Aadhaar, PAN and bank details with the PF account. The Aadhaar name, birth date and gender should match the UAN profile. The linked mobile must receive OTPs. PAN applies to tax checks in relevant cases, while the bank account must belong to the claimant.
Employment data needs another look. Joining and exit dates should appear correctly. Form 31 covers eligible advances, while Form 19 generally covers final PF settlement. A wrong claim type may trigger rejection or manual review. This 2-column check can catch common gaps.
Matching records improve the chance of automation but do not create eligibility. EPFO still checks service length, purpose, available balance and scheme conditions. Members should track an existing claim through the official portal or UMANG. Repeated submissions may add another check.
EPFO expanded auto-settlement during the COVID-19 period. It later covered eligible claims for illness, education, marriage and housing. Applications can pass system checks without routine human handling when records and conditions match.
The Ministry of Labour and Employment release dated 24 June 2025 marked a bigger step. EPFO raised the automatic advance-claim ceiling from ₹1 lakh to ₹5 lakh and set a target of up to 72 hours. During FY 2024-25, auto mode handled 59% of advance claims. The wider limit allowed more requests into the automated route.
Another change followed in October 2025. The Central Board of Trustees grouped 13 partial-withdrawal provisions under essential needs, housing and special circumstances. It standardised minimum service at 12 months. An eligible member may withdraw 75% of the available amount, while 25% remains protected, subject to the EPF Scheme.
By August 2026, CITES showed a shorter turnaround. The Press Information Bureau said on 4 August that national auto-settlement had reached 84% for Form 31 and 50% for Form 19. Kochi showed same-day movement for most eligible claims, but that regional result does not create a legal 24-hour deadline.
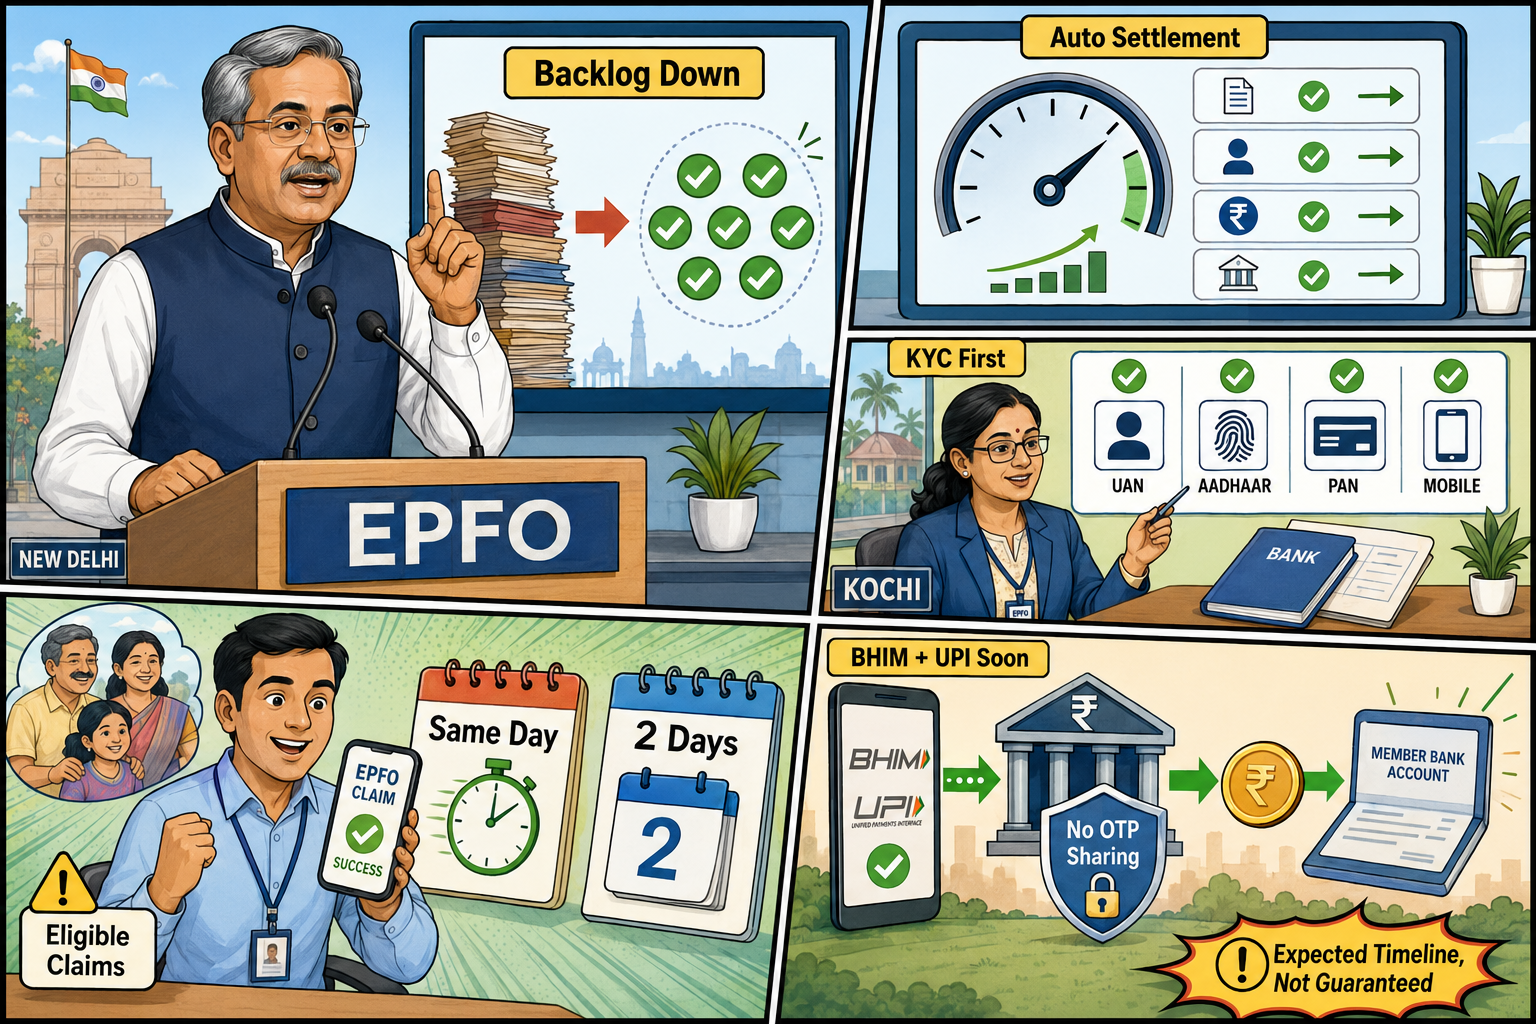
Ramesh Krishnamurthi said on 31 July 2026 that EPFO had almost removed its claim backlog. Auto-settlement, he added, was reaching as high as 90%. His aim was to settle most fresh claims on the same day or within 2 days. He described an expectation based on system performance, not a binding deadline.
Uttam Prakash, Regional Provident Fund Commissioner-I in Kochi, gave members a direct fix on 4 August 2026. He asked them to update KYC and keep the UAN authenticated and linked with Aadhaar, PAN and an active mobile number. Bank details deserve the same check before filing. His advice is simple, yet it addresses the errors that often push a digital claim towards manual handling.
The CPFC also said EPFO was preparing settlement through BHIM and a UPI-linked bank account. He expected the framework within about 1 month of 31 July. Members should wait for a formal launch. Receiving PF money will not require a UPI PIN, a shared OTP or an agent’s fee.
Members can log in to the UAN portal, compare the profile with Aadhaar, inspect bank KYC and check whether the employer entered the exit date. Old balances should appear under the active UAN after transfer.
After filing, the member should keep the claim ID and watch the status. “Under process” does not mean rejection. If it remains unchanged beyond the service period, the claimant can use EPFO’s grievance facility. Random SMS or WhatsApp links should be ignored.
EPFO’s move towards same-day and 2-day settlement can make provident fund savings more accessible during a financial emergency. The higher ₹5 lakh auto-settlement ceiling, central processing and fewer pending claims have created the conditions for quicker decisions.
Still, a 24-hour claim depends on eligibility and accurate digital records. Members need an active UAN, matching Aadhaar details, verified bank KYC and the right claim form. The system can move quickly when those pieces line up. When they do not, manual review remains part of the process.
An eligible, fully verified claim may be settled on the same day. EPFO has not guaranteed 24-hour payment for every applicant, and bank credit may take longer.
No. A member should track the existing claim and avoid a duplicate request. Manual verification, KYC errors or bank checks may extend the processing time.
Eligible advance claims for illness, education, marriage and housing can enter auto-settlement, subject to service, balance, KYC and scheme checks.
No. The UAN should be active, and Aadhaar, PAN (where applicable), bank details and the registered mobile number must be accurate.
Not always. Settlement means EPFO has approved and sent the payment. The member’s bank may need additional time to reflect the credit.
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers










