
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
EPFO members can access 75% of eligible PF savings, Press Information Bureau records show, while 25% remains invested and final settlement waits increased nationwide in 2026.
On 10 August 2026, Minister of State for Labour and Employment Shobha Karandlaje told the Lok Sabha that EPFO had widened partial access to provident fund savings. Members may withdraw up to 75% of the eligible balance under 3 broad groups. The rule covers registered workers across India during unemployment, illness, education expenses, marriage or housing needs.
A household can use a large part of its PF without waiting for complete settlement. After a job exit, however, a member may wait 12 months for the final 25% of EPF and 36 months for an eligible EPS withdrawal benefit. Retaining 25% can protect later savings, though a family without another income may need it earlier.
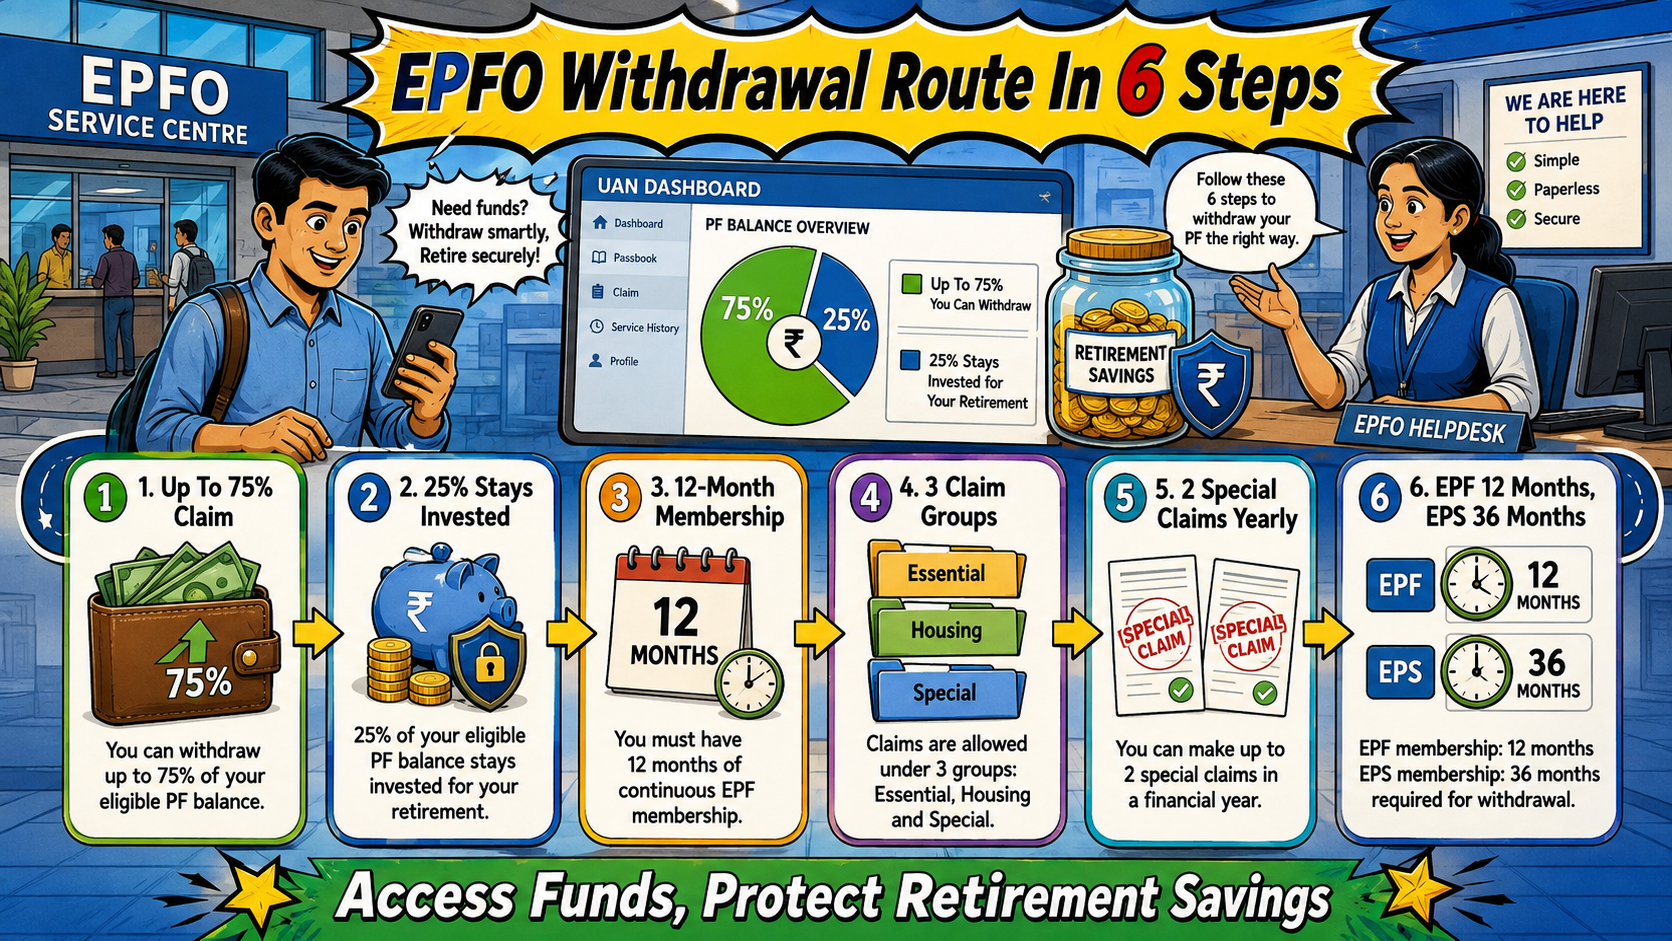
The revised rules give members access to a large portion of their provident fund while protecting some savings for retirement. Here is how the process works:
Earlier provisions used different conditions and calculations for each purpose. Some advances relied mainly on the employee’s share and interest. The revised calculation can include eligible employee and employer EPF contributions with interest. That can produce a larger amount during illness, unemployment or an urgent housing payment.
A LoansJagat calculation considers an employee with an eligible EPF balance of ₹4,00,000. A 75% withdrawal would provide up to ₹3,00,000, while ₹1,00,000 stays in the account. If the household spends ₹50,000 each month, the available amount could cover 6 months of expenses. It would still leave a gap if unemployment lasts 12 months. This calculation shows both sides of the rule: quicker access to a substantial sum, followed by a longer wait for complete settlement.
Soayib Qureshi, Partner at PSL Advocates & Solicitors, told Business Standard on October 17, 2025, that families would likely be more affected by the prolonged waiting time as they struggle to pay rent and other bills. The old 2-month settlement window enabled households to pay bills. Now employees could run out of money, as the search for a new job could take over three months.
A member should first check health insurance, bank savings and household income. If these cannot cover the expense, a partial PF claim may cost less than high-interest debt. The LoansJagat PF withdrawal guide separates partial access from final settlement and highlights UAN, bank and exit checks. Taking only the required amount leaves more money earning EPF interest.
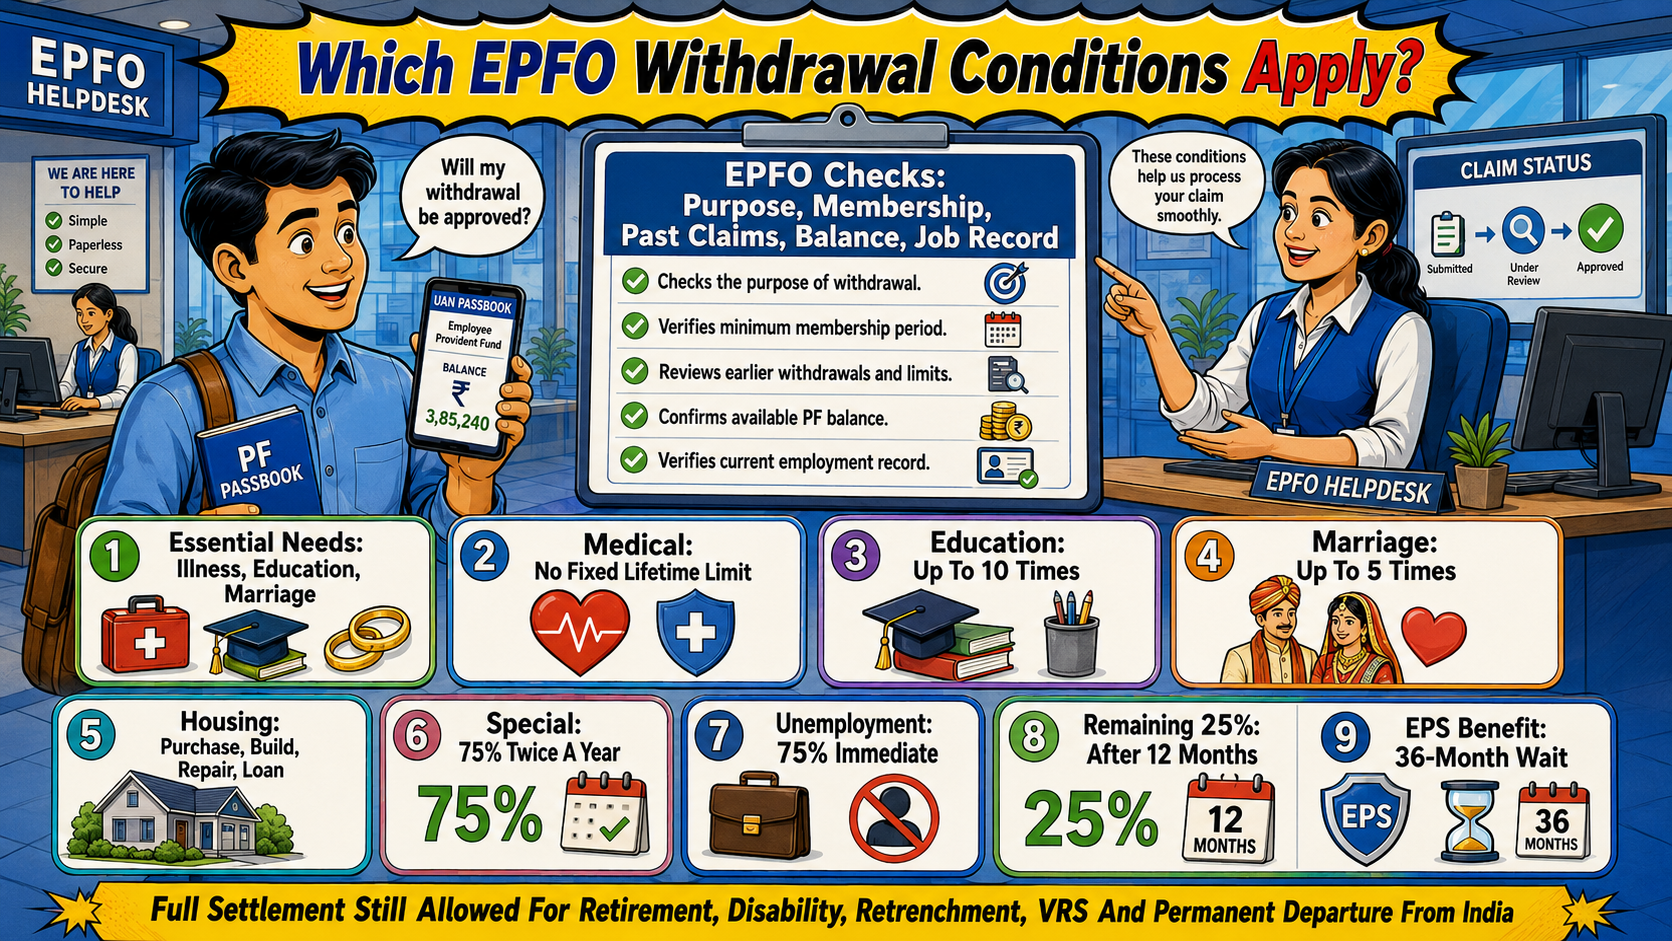
“Up to 75%” sets the maximum but does not promise the same payment for every claim. EPFO will check the purpose, membership period, earlier withdrawals, available balance and employment record.
The 25% condition does not stop every full withdrawal. Complete settlement remains available for retirement at the prescribed age, permanent disability, incapacity, retrenchment, voluntary retirement and permanent departure from India. Ordinary resignation takes the 12-month route.
The Central Board of Trustees approved the updated withdrawal framework at the 238th meeting on 13th October 2025. The Ministry of Labour and Employment made a statement about 2 days later saying several workers faced a situation of low retirement balances due to repeated withdrawals. From the data presented, it was clear that 50% of members had less than ₹20,000 at final settlement and 75% had less than ₹50,000.
Officials said keeping 25% invested would preserve future interest and compounding. The Ministry referred to the 8.25% EPF rate applicable at that time. Repeated withdrawals remove later earnings, but the retention rule can restrict cash during unemployment.
The older framework contained 13 partial-withdrawal provisions. Service requirements varied and could extend up to 7 years for certain purposes. Marriage and education shared a combined lifetime limit of 3 claims. Under the revised framework, EPFO grouped withdrawals into essential needs, housing needs and special circumstances. The common membership requirement became 12 months, while education claims rose to 10 and marriage claims to 5.
Final settlement changed in the other direction. The earlier rule generally permitted full PF withdrawal after 2 months without employment. The revised rule allows 75% access during unemployment but holds the remaining 25% until 12 months have passed. EPS withdrawal benefits moved from the earlier 2-month period to 36 months, subject to pension eligibility.
The legal foundation arrived through the Employees’ Provident Funds Scheme, 2026. The Ministry notified it through G.S.R. 525(E) on 29 June 2026 in the Gazette of India, Extraordinary, Part II, Section 3(i). The scheme replaced the Employees’ Provident Funds Scheme, 1952, from its publication date.
Karandlaje told the Lok Sabha on 10 August 2026 that members could use the special-circumstances option twice every year without stating a reason. She also said employee groups, recognised trade unions, employers and central and state government representatives had discussed the amendments through the Central Board of Trustees before notification.
Central Provident Fund Commissioner Ramesh Krishnamurthi defended the policy on 16 October 2025. He said EPFO wanted to give members more control and automate claims. Rajya Sabha member Saket Gokhale argued on 15 October 2025 that workers should not remain unemployed for 12 months to receive their complete savings.
EPFO wants workers to reach retirement with money left in the account. Jobless members may place immediate household costs first. The 75% facility reduces that pressure but may not cover a full year.
Before filing, a member should verify the UAN, Aadhaar-linked mobile number and bank account shown on the Employees’ Provident Fund Organisation website. Former employees should check the date of exit. A spelling difference or incomplete service history can delay payment.
Form 31 covers eligible advances. Form 19 applies to final EPF settlement, while Form 10C covers specified EPS claims. Members should select the correct form and review the displayed amount before Aadhaar authentication. A new job normally calls for transferring the balance through UAN.
The revised EPFO conditions give members access to 75% of eligible PF savings for several needs, while protecting 25% for retirement. For someone facing a hospital expense or loss of income, that access can prevent costly borrowing. It can also cover only part of a long unemployment spell.
Members should distinguish partial withdrawal, final EPF settlement and EPS withdrawal before filing. The category chosen, service record and available balance will decide the payment. A careful claim preserves more retirement savings and lowers the chance of rejection.
No. The member must meet the relevant membership, purpose and account conditions. The approved amount may also be lower than 75% if the eligible balance is smaller.
The remaining 25% becomes available after 12 months of unemployment under the revised final-settlement condition. Specified retirement, disability, retrenchment and emigration cases follow separate provisions.
Yes, the eligible calculation can include both employee and employer EPF contributions with interest. The EPS pension portion remains separate and follows pension rules.
The portal may not show it when the date of exit is missing, the required unemployment period has not passed or the service record needs correction.
No. The 36-month wait concerns eligible EPS withdrawal benefits. Premature final EPF settlement has a separate 12-month period.











