
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
EPFO notified 8.25% interest for FY 2025–26 on 1 July 2026, drawing on investment earnings to support annual returns on members’ provident fund savings accounts.
Key Highlights
The Employees’ Provident Fund Organisation notified 8.25% interest on 1 July 2026, following Labour Ministry approval, and directed regional and zonal offices to credit members’ accounts. Trustees had recommended the rate at their New Delhi meeting. The notification established the return on eligible EPF balances for FY 2025–26.
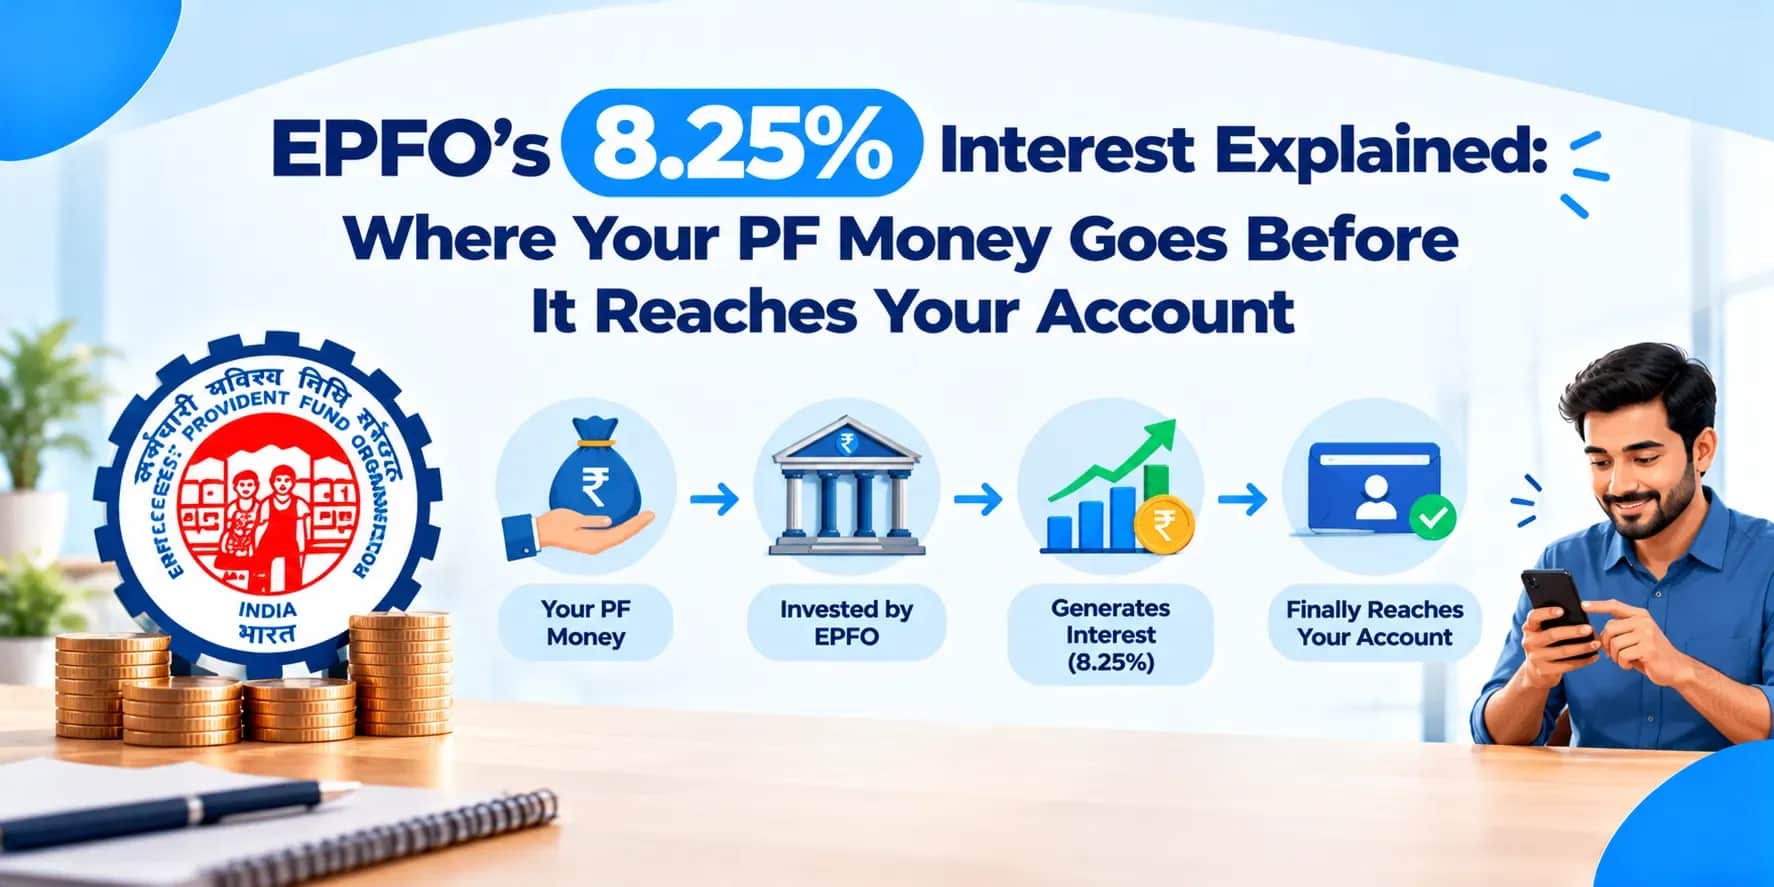
EPFO earns income by investing workers’ pooled savings before crediting annual interest. Debt securities and equity exchange-traded funds, or ETFs, form part of this portfolio. Market losses can affect investment earnings. Members, however, receive the approved annual rate rather than separate returns from individual holdings, supporting the accumulation of retirement savings.
EPFO’s pooled system gives workers access to professionally managed investments without requiring each member to select bonds or ETF units. On 13 October 2025, trustees approved 4 fund managers to manage the debt portfolio for 5 years. EPFO’s managers operate within the prescribed investment framework.
Retained savings also benefit from compounding. Interest becomes part of the balance that earns subsequent interest. In its clarification dated 15 October 2025, the Labour Ministry warned that repeated withdrawals had prevented lower-paid workers from receiving the full benefits of compounding. Withdrawals meet immediate needs but reduce savings left for retirement.
Rashid Ali, co-founder of Cashlo App, explained in comments published on 30 October 2026 that trustees review investment income, accumulated surplus and liabilities before recommending interest. Sheersham Gupta, director at Rupeezy, identified interest, dividends and capital gains, alongside possible losses, as factors affecting the sustainable payout.
EPFO’s investment controls address how the fund manages those risks. The Labour Ministry’s announcement dated 2 March 2026 records approved ETF entry and exit procedures, exposure limits and oversight through the Investment Monitoring Cell. These measures govern investment operations and strengthen monitoring of members’ pooled savings.
Union Minister of State for Labour and Employment Shobha Karandlaje described EPFO’s investments in a written Lok Sabha reply dated 2 December 2024. EPFO invests in debt securities and ETFs under the notified investment pattern and trustees’ guidelines.
The parliamentary reply dated 2 December 2024 states that EPFO does not invest directly in individual company shares. ETF units provide exposure to securities held by the funds. Members receive annual EPF interest through the pooled system rather than separate ETF gains in their accounts.
EPFO’s trustees recommend interest after reviewing the fund’s earnings and obligations. Government approval precedes the notification directing offices to credit members’ accounts. For FY 2025–26, the recommendation came on 2 March 2026 and the notification followed on 1 July 2026.
The sequence explains why a trustees’ recommendation and an interest credit are separate steps. EPFO’s investment income supports the payout, while the approval process establishes the rate applicable to members for the specified financial year.
For borrowers, EPFO’s 8.25% rate measures earnings on retirement savings. A loan instalment includes repayment of principal as well as interest, so comparing an EMI amount directly with PF interest gives an incomplete comparison. The relevant analysis separates the total cost of borrowing from the savings removed through a PF withdrawal.
EPFO’s 8.25% interest for FY 2025–26 follows pooled investment, a financial review and government approval. Professional management handles the portfolio, while compounding supports retained savings. The annual credit reflects this process rather than the performance of an individual bond, ETF or company share.
EPFO notified 8.25% annual interest for FY 2025–26 on 1 July 2026 after government approval. Regional and zonal offices received instructions to credit the approved interest to members’ EPF accounts.
EPFO calculates interest on monthly running balances and credits it annually. Monthly calculation and annual credit are separate processes. Contributions and withdrawals change the balances used to calculate the interest due for the financial year.
EPFO does not directly invest in individual company shares, as confirmed in the parliamentary reply dated 2 December 2024. Its equity investments use ETFs, including funds tracking the Nifty 50 and Sensex.
EPFO members receive the declared annual interest rate. They do not receive separate returns from each bond or ETF. Investment earnings contribute to the pooled fund’s finances, which trustees review when recommending interest.
EPF interest adds to the retained balance and contributes to subsequent interest earnings. The Labour Ministry’s 15 October 2025 clarification identified repeated withdrawals as a reason lower-paid workers missed the full benefits of compounding.
Start your journey today
Apply Now*T&C apply











