
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
India’s fintech sector now faces a harder test: proving that wider financial access can consistently produce safer choices, longer participation and stronger household investment outcomes.
Key Highlights
India’s fintech story has reached a stage where a new account, an app download or a completed trade reveals only part of the picture. What happens to the investor afterwards is drawing closer scrutiny. In its May 2026 paper, Reimagining Financial Distribution: Scale, Trust, and Sustainability, PwC and FICCI called for greater attention to the quality of financial decisions, a concern also raised by experts quoted by Moneycontrol. SEBI Investor Survey 2025, published online on 20 January 2026, explains why the debate has grown. Around 63% of Indian households knew about at least 1 securities-market product, while only 9.5% had invested in securities.
The shift could affect brokers, wealth apps, mutual fund platforms and first-time investors across India. In the short term, firms may spend more on advisers, support and product checks. Some may lose transaction revenue if they remove prompts that encourage frequent trading. Over time, better guidance could help households avoid unsuitable products and panic exits. Yet easy entry paired with weak advice can expose a new investor to losses before that person has learnt how the product works.
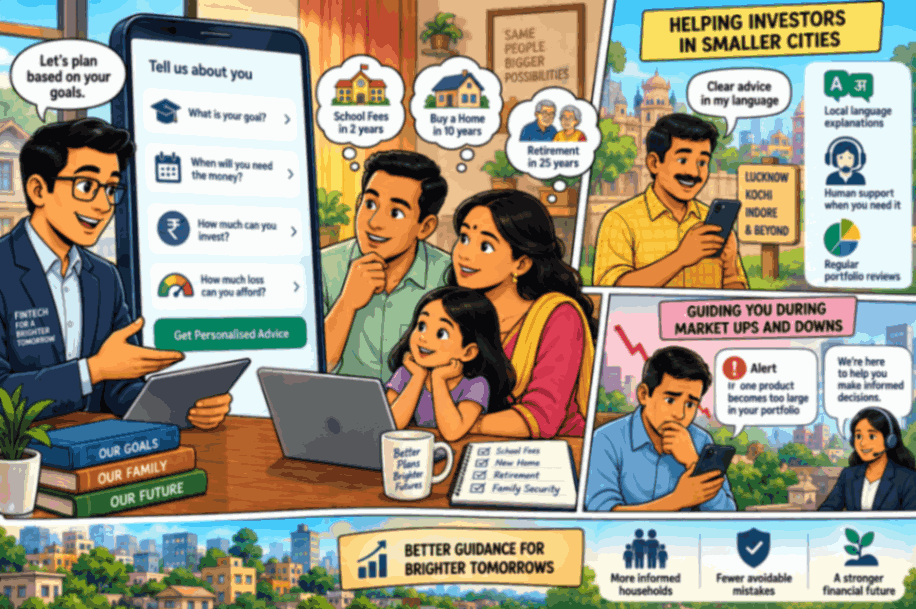
For a household, the change begins after onboarding. A platform would ask why the money is being invested, when it will be needed and how much loss the customer can afford. A person saving for school fees due in 2 years should not receive the same suggestions as someone investing for retirement after 25 years. Charges, exit conditions and risk should appear before the order.
Smaller cities may see a larger benefit because digital access has travelled further than affordable advice. An investor in Lucknow, Kochi or Indore can open an account quickly, yet may have nobody to call during a market fall. Outcome-led service would add local-language explanations, portfolio reviews and human support. It could also warn families when 1 risky product has become too large within their savings. These steps cannot remove loss, but they can reduce avoidable decisions.
The PwC-FICCI paper asks firms to replace acquisition-heavy scorecards with measures tied to a customer’s journey. Suggested indicators include retention, SIP continuity, goal progress and long-term satisfaction. A risk-profile form completed in seconds offers little protection if later recommendations do not match the customer’s income, time period or ability to carry a loss.
The solution reaches app design and business incentives. Platforms can show costs beside returns, explain recommendations and slow down orders for complex products. They should also review whether revenue rises when customers trade more, even when those trades hurt them. From a LoansJagat editorial view, projected wealth should appear beside risk and non-guarantee information. The LoansJagat SIP guide states that returns depend on market performance and fund selection. That warning belongs beside any projected corpus.
India’s access numbers answer different questions. A bank account shows entry into formal finance, while a demat account provides the route to hold securities. Neither confirms useful advice or goal completion.
The figures do not support slower access. They show why the next scorecard must go further. Firms can examine whether customers remain invested, pay reasonable costs and hold suitable products. Regulators can compare rapid growth with complaints, dormant accounts and repeated loss.
India’s earlier phase removed barriers that once kept formal finance beyond many households. Jan Dhan widened access to basic banking. Aadhaar-supported verification reduced paperwork, while UPI made digital payments part of everyday spending. Discount brokers and mobile investment apps then cut the time and cost needed to buy mutual funds, shares and bonds. A process that once required branch visits could often be completed from a phone.
The gains brought a new difficulty. Product choice expanded faster than dependable advice. SEBI announced its Investor Survey through Press Release 63/2025 on 30 September 2025, then uploaded the main report and data on 20 January 2026. The study found that many households knew about securities but had not invested. It also recorded the influence of personal contacts and financial influencers. Platforms must now help customers separate regulated guidance from persuasive online content.
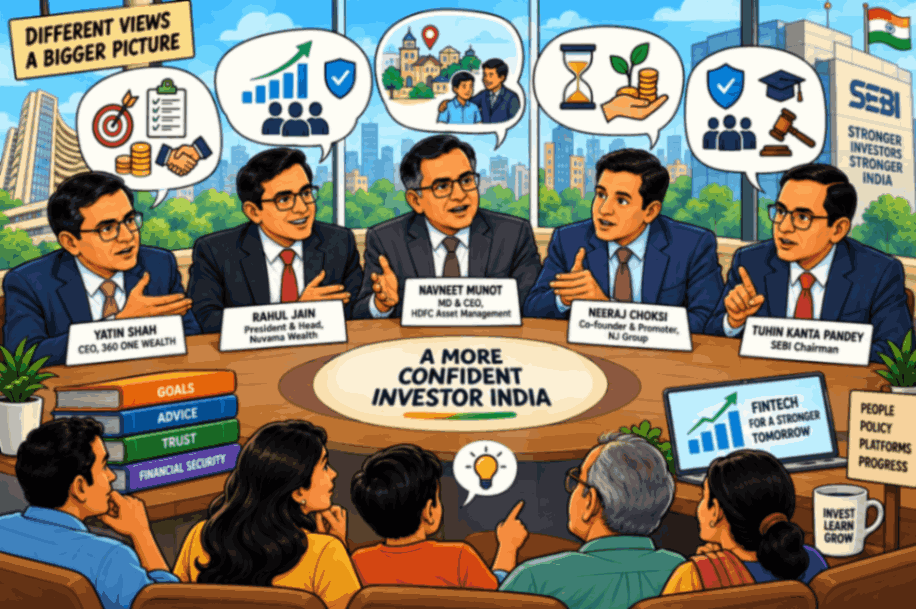
Yatin Shah, CEO of 360 ONE Wealth, argued in the PwC-FICCI report that the industry has a quality-of-advice problem. His approach starts with the customer’s goals, an investment policy statement, disclosed fees and no hidden conflicts. Technology can carry this process to more households, but only when suitability forms part of every interaction.
Rahul Jain, President and Head of Nuvama Wealth, said product availability is no longer the main constraint. Distribution now depends on quality, reach and trustworthiness. His comments point towards advice-led models that continue supporting a customer after the initial purchase, particularly when markets fall or household needs change.
Navneet Munot, MD and CEO of HDFC Asset Management Company, highlighted human guidance for first-generation investors in smaller towns. Digital systems can lower delivery costs, but a person may still need help with a decision involving years of savings. Neeraj Choksi, Co-founder and Promoter of NJ Group, said distributors create value by helping investors remain with suitable funds rather than chase short-term performance.
SEBI Chairman Tuhin Kanta Pandey wrote in the Investor Survey foreword that its findings would guide financial education, investor protection, grievance redressal and wider participation. This places accountability beside growth. Fintech firms could therefore face harder questions about who created a recommendation, which data shaped it, how conflicts were disclosed and what support followed when a customer complained.
India has proved that technology can widen financial entry at huge scale. The next test will examine what those accounts and apps deliver after registration. Fintech platforms cannot promise profits or control market prices. They do control product displays, prompts, warnings, fees, recommendations and customer support.
An outcome-based model would judge whether the customer chose a suitable product, knew the risk and stayed on course for a stated goal. It may produce fewer flashy activity numbers. Yet it could create something more useful: investors who know what they own, why they own it and when they may need to change course.
It refers to the quality of the customer’s result, including product suitability, costs, risk taken, time invested and progress towards a financial goal. It does not mean guaranteed returns.
India already has wide banking and investment access. Experts now want firms to examine whether customers receive suitable guidance, avoid harmful behaviour and remain invested long enough to pursue their goals.
No. Market-linked returns cannot be guaranteed. Platforms can still improve disclosures, risk checks, fee information and customer support, which may reduce avoidable mistakes and unsuitable purchases.
A beginner can review regulatory registration, fees, risk warnings, complaint channels and the reason behind each recommendation. Promises of assured market returns should be treated as a warning sign.
No. A demat account only provides access. Investors still need a goal, suitable product choice, risk limits, fee information and dependable guidance before placing an order.












