By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Indian bank customers now have wider nomination choices, quicker deceased-account claims and compensation when lenders delay returning pledged gold after a loan closes in 2026.
India’s revised banking framework gives depositors, nominees and gold-loan borrowers stronger protection during situations that often bring branch visits and paperwork. The Press Information Bureau confirmed that nomination provisions took effect on November 1, 2025, while banks received time during 2026 to implement revised deceased-customer and gold-collateral procedures across India.
In the short term, families should find it easier to claim fixed deposits after a depositor dies, provided they submit complete documents. Borrowers also gain a direct payment if a lender delays pledged jewellery. There is a difficult side. Branches may apply new procedures unevenly at first, and a nomination can still conflict with a will or succession law.
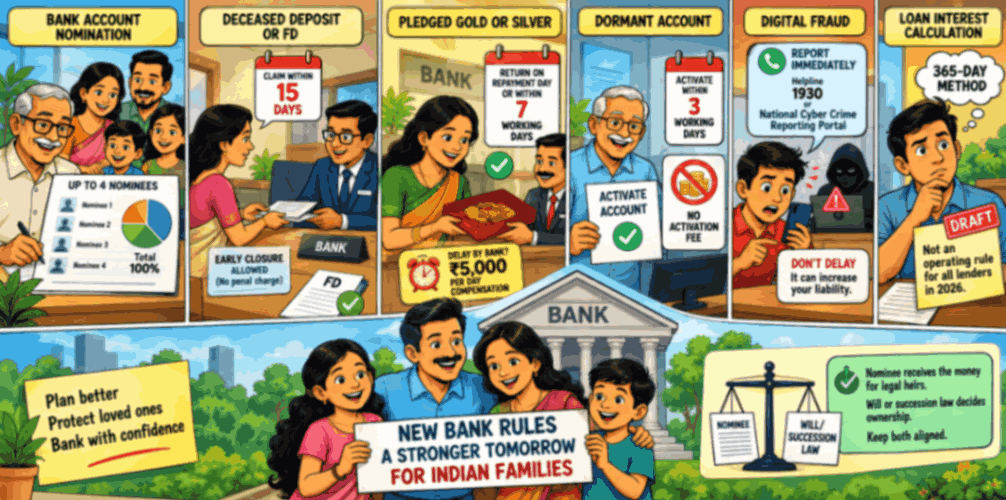
The most visible change is the option to name up to 4 nominees. A depositor may divide the deposit through simultaneous nomination, with shares totalling 100%. Successive nomination places people in a recorded order. For lockers and articles in safe custody, only the successive option is allowed.
The added choice helps larger households plan. A parent may divide a deposit among 3 children, while a senior citizen may place a spouse first and an adult child second. Yet bank payment does not decide inheritance. A nominee normally receives the money for the legal heirs, while the will or succession law decides ownership. Both records should point in the same direction.
For a deceased customer’s deposit, a bank should ordinarily ask the nominee or survivor for a claim form, death certificate and identity document. It should not demand probate, a succession certificate or an outside surety merely because the balance is large. Directions issued on September 26, 2025 gave banks until March 31, 2026 to comply. A bank-caused delay after complete documentation attracts at least the prevailing Bank Rate plus 4% a year on the delayed amount.
Joint deposits need closer attention. Unless the account permits survivors to close the FD, the bank may seek consent from surviving holders and the deceased holder’s legal heirs. Families should request the standard claim checklist in writing. That can prevent fresh demands after filing.
Gold-loan borrowers receive different relief. After full repayment, the lender must return pledged gold or silver on the same day or within 7 working days. The ₹5,000 daily payment begins when a lender-caused delay crosses that period. It may not apply if the borrower fails to collect the articles after notice. The valuation certificate must record purity, gross weight, net weight and deductions.
A LoansJagat review of the changed gold-loan rules points to a practical borrower benefit. Written valuation and return records reduce arguments over what the lender accepted and handed back. A family pledging wedding jewellery should also keep photographs, the valuation certificate and a stamped closure receipt.
Previously, bank accounts generally carried only 1 nominee. If that person died before the depositor or could not complete the claim, the family could enter a longer process. Branches also sought different papers for similar deceased-account balances. The revised framework seeks consistency without removing legal-heir rights.
Dormant-account and KYC provisions have been misreported as entirely new 2026 rules. An account generally becomes inoperative when the customer makes no transaction for more than 2 years. Savings interest continues and activation carries no fee. CKYC has operated since 2016, letting an institution retrieve an existing record with consent. Fresh papers may still be sought when details change or the record is incomplete.
Online fraud rules need a date check. The 2026 framework can provide zero liability when the bank caused the loss or an eligible third-party breach is reported within 3 working days. Relief announced in June 2026 for certain small customer-negligence cases starts on January 1, 2027. It is not a refund guarantee for every complaint.
The Ministry of Home Affairs reported in a Lok Sabha reply published on July 28, 2026 that the Citizen Financial Cyber Fraud Reporting and Management System had helped save more than ₹11,158 crore across over 32.80 lakh complaints up to June 30, 2026. Speed remains the customer’s strongest protection. A person who notices an unknown transfer should contact the bank and 1930 immediately, then preserve messages, screenshots and the complaint acknowledgement.
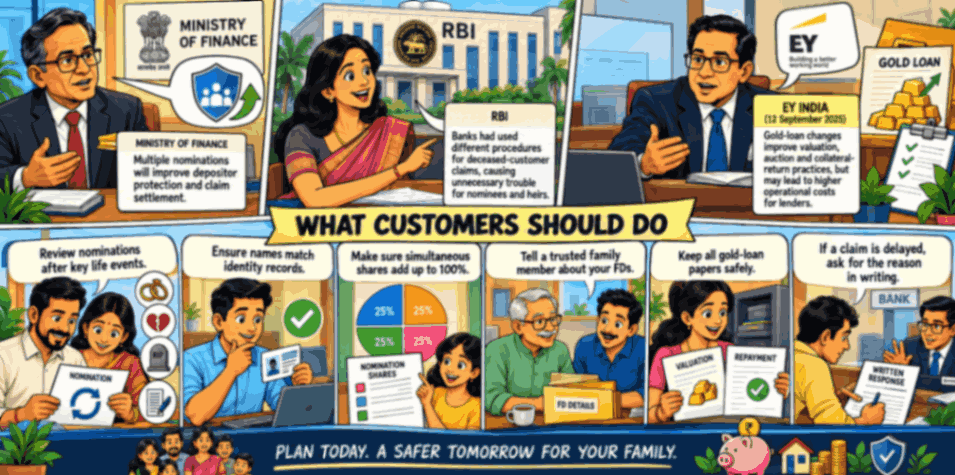
The Ministry of Finance said multiple nominations should improve depositor protection and claim settlement. Regulators also recorded that banks had used differing procedures for deceased-customer claims, which caused avoidable trouble for nominees and heirs. EY India’s assessment dated September 12, 2025, co-authored by Manik Mahajan, said the gold-loan changes improve valuation, auction and collateral-return practices. It also flagged higher operational costs for lenders adapting branches and technology.
The customer’s response need not be complicated. Depositors should review nominations after marriage, divorce, a nominee’s death or any revision to a will. Names must match identity records, while simultaneous shares must reach 100%. FD holders should tell a trusted family member where deposit details are kept. Gold-loan customers should retain every valuation and repayment paper. When a branch delays a claim, the applicant should request the reason and missing-document list in writing before escalating the complaint.
The 2026 banking changes give families a better route through events that are already stressful, especially death claims and recovery of pledged jewellery. Multiple nominees reduce dependence on 1 person, while fixed processing periods place greater responsibility on the bank. Yet forms alone cannot prevent every family dispute.
Customers should treat nomination, KYC and estate papers as connected records. A yearly review takes little time. Keeping those details current, reporting fraud immediately and collecting written proof at loan closure can turn a new banking rule into protection that works when it is actually needed.
Yes. A depositor may appoint up to 4 nominees simultaneously or successively. Simultaneous nominees receive recorded shares totalling 100%, while successive nominees are placed in an order of priority.
Yes. The revised procedure permits premature closure without a penal charge after death. In a joint FD, the bank may still require consent from survivors and legal heirs unless the deposit includes a suitable mandate.
Not automatically. The bank may release the balance to the registered nominee, but inheritance is decided by the will and applicable succession law. The nominee may have to pass the money to the legal heirs.
The nominee should approach the bank with its claim form, the depositor’s death certificate and an accepted identity document. If the bank asks for additional papers, the family should request the requirement in writing.
It applies when the lender fails to return pledged gold or silver within 7 working days after full repayment or settlement and the delay is attributable to the lender. Borrower-caused delay can fall outside the payment rule.