By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Managing multiple loans involves more than making monthly EMI payments. You also need to track interest rates, repayment periods, outstanding balances and other charges. But what if your current loan terms no longer suit your financial situation? An AI-powered assessment can help you review your financial profile and identify possible ways to manage existing loans more effectively. From refinancing to consolidation and restructuring, the right approach depends on your income, repayment capacity and loan details.
Key Takeaways
AI can analyse financial information to identify patterns and potential opportunities. In loan management, this may include reviewing your income, existing EMIs, repayment history and other financial details.
Based on this information, an AI-powered platform can help identify whether your current loan arrangements could be optimised.
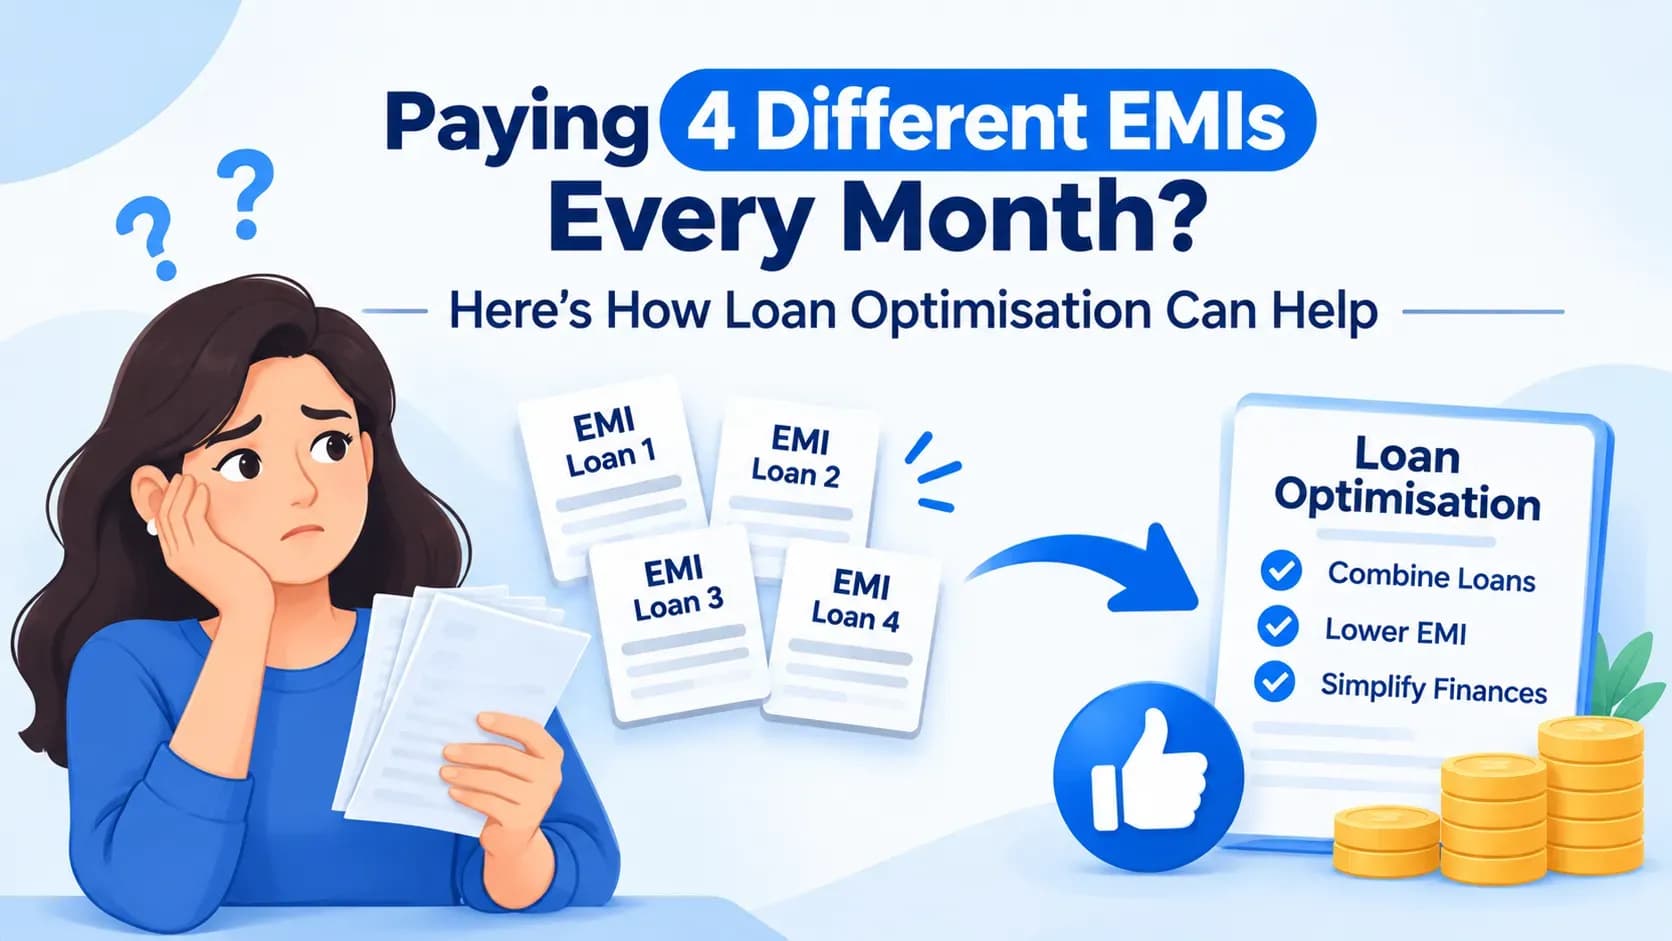
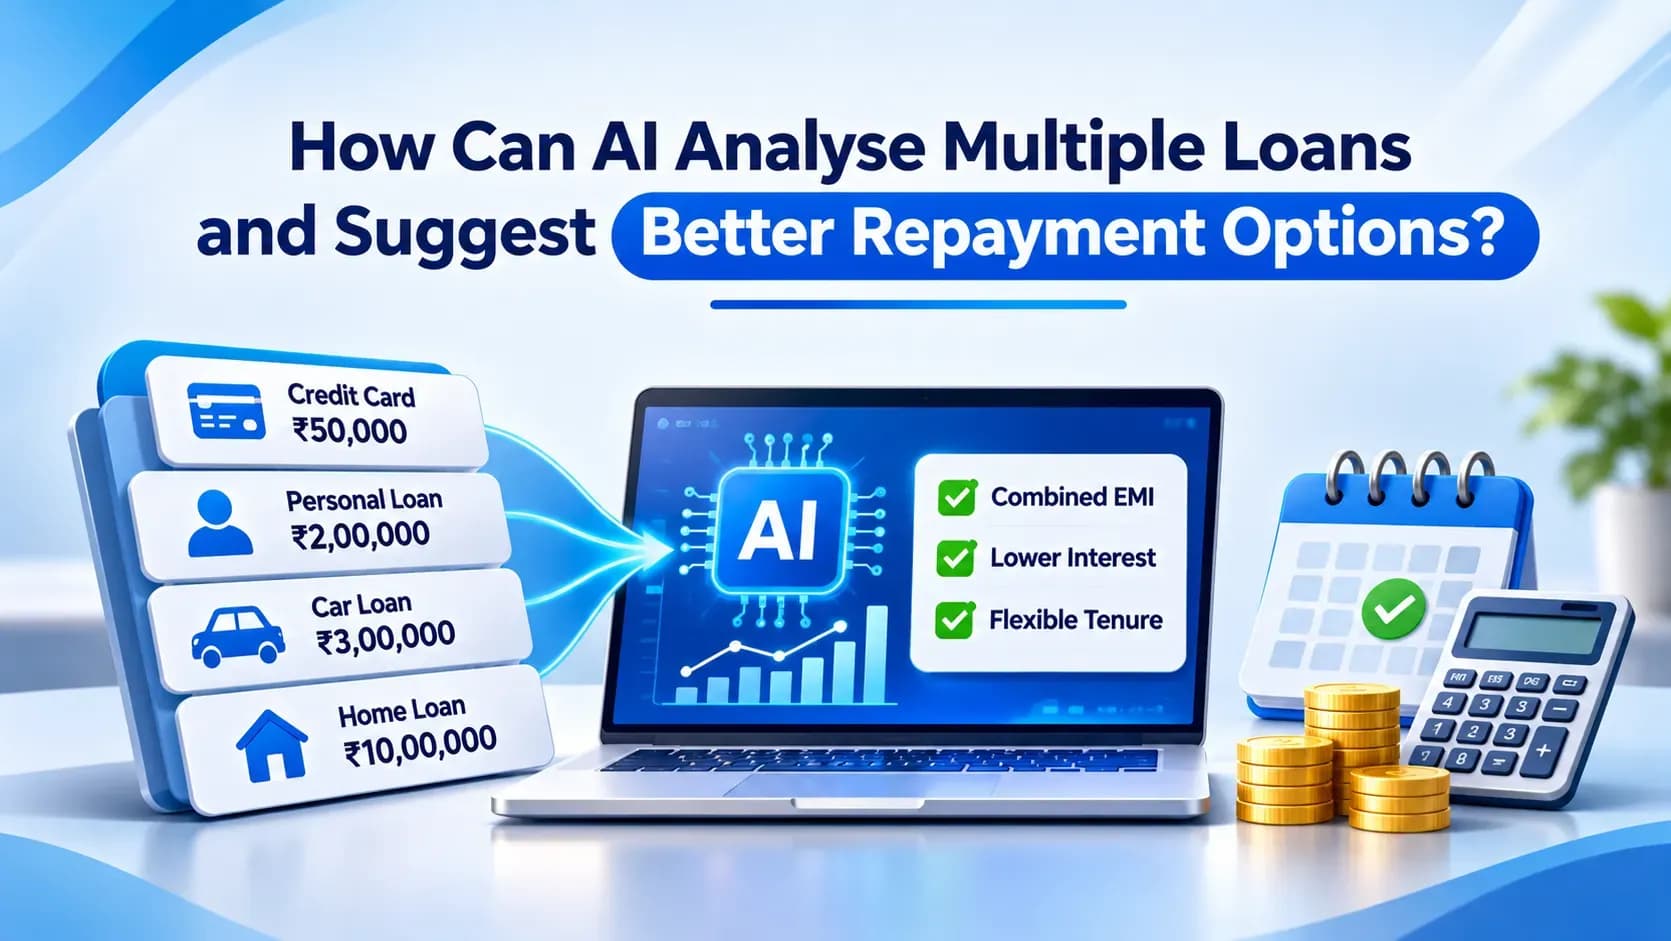
For example, consider someone paying three different EMIs every month. Each loan may have a different interest rate, outstanding balance and repayment period. Managing these commitments can become difficult, especially when a large part of the monthly income goes towards repayments.
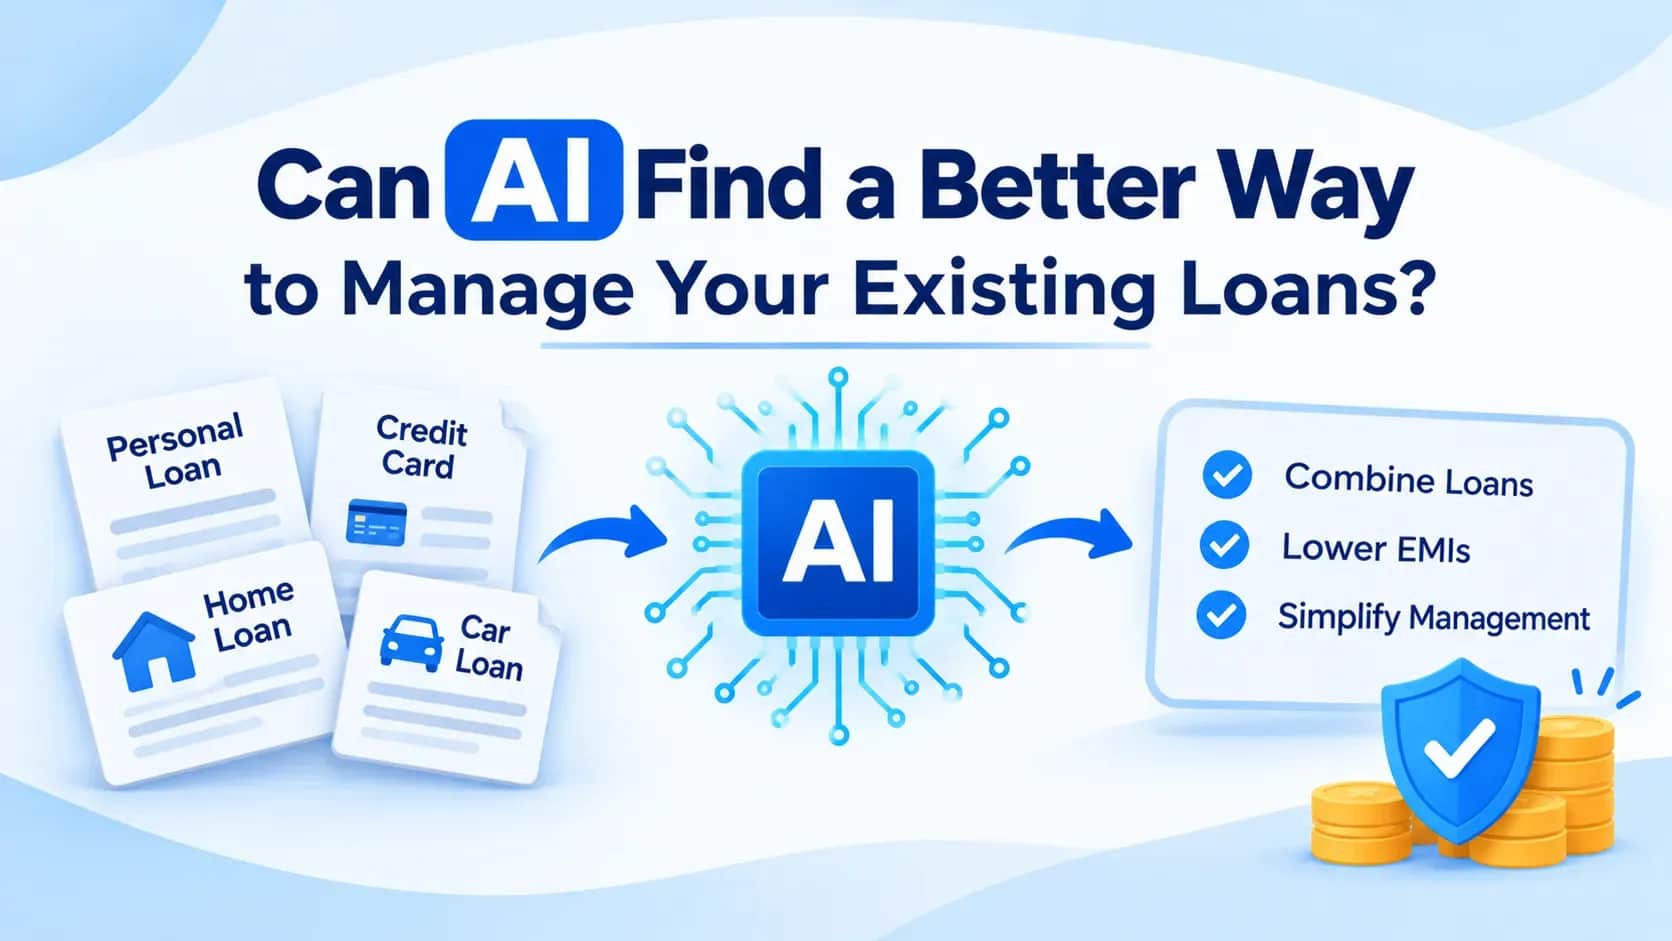
An AI-powered assessment can bring these details together and highlight possible options, such as:
AI can help identify possibilities, but it does not guarantee loan approval, better terms or savings. The final decision depends on lender policies, eligibility and the cost of the proposed arrangement.
A suitable loan optimisation plan needs to consider more than the number of loans you have. Your overall financial position also matters.
Here are some important factors an AI-powered assessment may consider:
Your income helps determine how much you can comfortably allocate towards loan repayments. A change in income can also affect your repayment capacity.
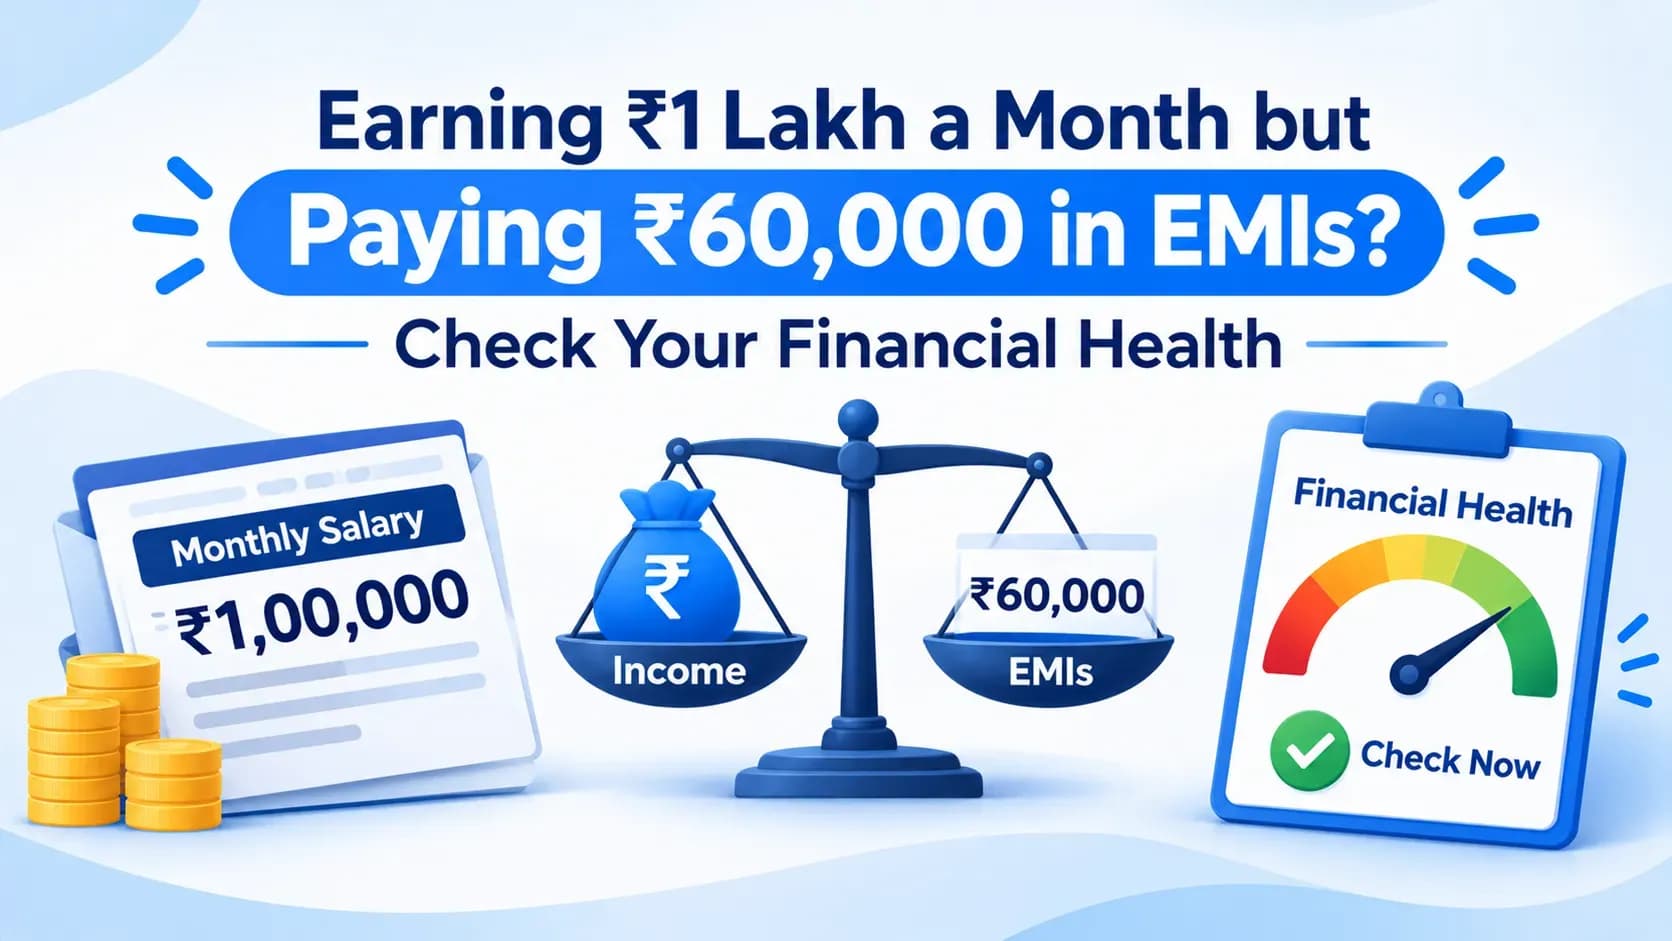
For instance, someone earning ₹80,000 a month may find it difficult to manage ₹45,000 in EMIs alongside household expenses and savings.
The number and amount of your existing EMIs indicate how much of your monthly income is already committed to repayments.
If several EMIs take up a significant share of your income, reviewing your repayment arrangements may help identify opportunities to improve monthly cash flow.
Your repayment history provides insight into how you have managed previous and current credit commitments. Missed or delayed payments can affect your credit profile and may influence a lender's assessment.
The outstanding principal, interest rate, remaining tenure and applicable charges help determine whether changing your existing loan arrangement makes financial sense.
A lower interest rate does not automatically mean a better deal. Processing fees, foreclosure charges and a longer repayment period can increase the total amount payable.
Your savings and available emergency funds also matter. If most of your income goes towards EMIs, you may have limited room to manage unexpected expenses.
Considering these factors together provides a broader view of your financial position than looking at individual loans separately.
Depending on your financial profile and existing loan terms, an AI-powered assessment may identify different ways to manage your repayments.
If you are managing multiple loans or credit card dues, consolidation may allow you to combine eligible outstanding amounts into one loan.
Instead of tracking several repayment dates, you may have one EMI to manage. However, check the new interest rate, processing fees and total repayment amount before proceeding.
Consolidation may not be suitable if the new loan increases your overall borrowing cost.
Refinancing involves replacing an existing loan with a new one. This may be worth exploring if your financial profile has changed or more suitable financing options are available.
For example, a borrower with an existing personal loan may compare offers from other lenders to check whether a different interest rate or repayment tenure is available.
Consider the outstanding balance, foreclosure charges, processing fees and total interest payable before switching.
If your current EMI is difficult to manage, you may approach your lender to discuss restructuring.
Depending on the lender's policies and your circumstances, this could involve changes to the repayment schedule or loan tenure. Any revised arrangement must be approved by the lender.
Restructuring may affect the total interest payable and other loan terms, so understand the implications before accepting an offer.
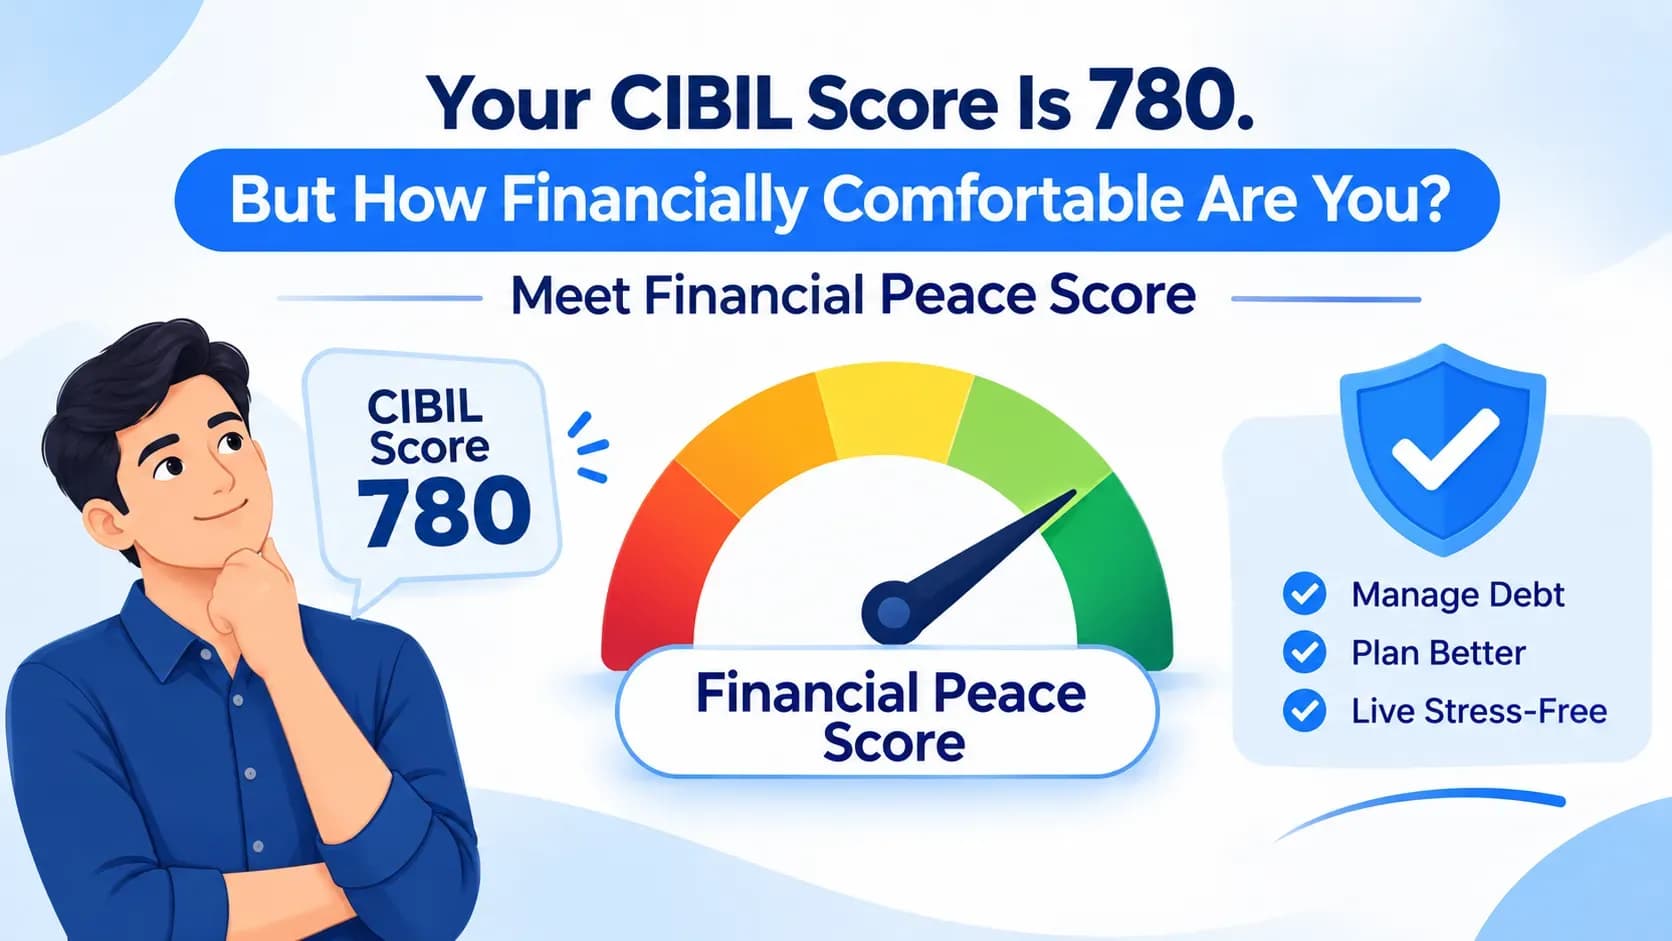
A CIBIL score provides information about your credit history and repayment behaviour. However, it does not show your complete financial position, including how comfortably you manage EMIs alongside regular expenses and savings.
 Apply Now
*T&C Apply
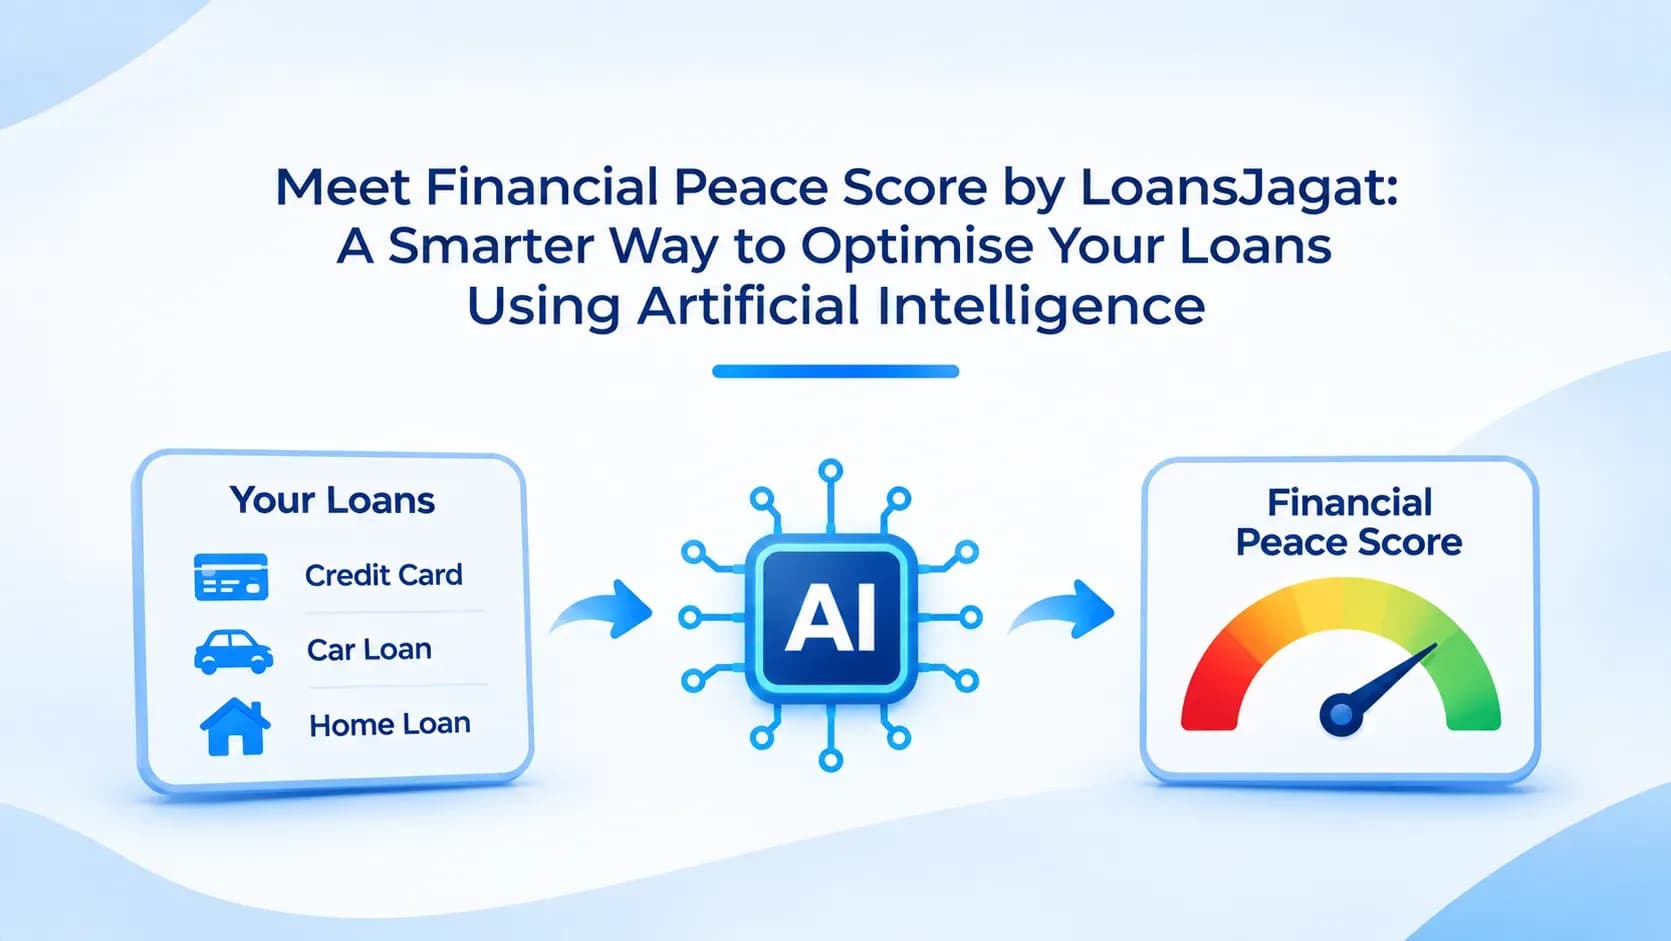
LoansJagat's Financial Peace Score takes a broader view of financial wellness. It helps you understand your financial position and explore possible ways to manage existing loan commitments.
Here is how the process works:
Step 1: Check Your Financial Peace Score
Start by checking your Financial Peace Score on LoansJagat. The assessment considers your financial profile to provide a broader view of your financial health.
Step 2: Get Your Score and Personalised Plans
Once the assessment is complete, you can view your Financial Peace Score along with personalised loan optimisation plans. You do not need to complete a separate step to access these plans.
Step 3: Explore AI-Powered Optimisation Opportunities
The AI-powered platform uses your financial profile to identify possible optimisation opportunities. These may include consolidation, refinancing, restructuring and other suitable options.
Step 4: Compare Available Loan Options
LoansJagat helps you compare offers from 50+ banks and NBFCs. You can review the available terms and understand which options may align with your financial requirements.
The final offer, interest rate and approval depend on the lender's assessment and eligibility criteria.
An AI-powered recommendation can help you identify options, but you should evaluate the financial implications before making a decision.
Keep these points in mind:
Do not choose an option only because it offers a lower EMI. The overall cost and your ability to repay should guide your decision.
AI can make it easier to review existing loan commitments by bringing financial details together and identifying possible optimisation opportunities. However, the right option depends on your income, repayment capacity, outstanding balances and lender terms. LoansJagat's Financial Peace Score combines a broader financial wellness assessment with AI-powered personalised loan optimisation plans. It helps you look beyond your credit score and explore ways to manage your existing loans more effectively.
An AI-powered platform can assess your financial profile and existing loan commitments to identify possible options, such as consolidation, refinancing or restructuring.
AI can identify potential loan optimisation options that may change your monthly repayment amount. However, the outcome depends on the new loan terms, charges and lender approval.
The impact depends on the action you take. Applying for new credit, closing existing loans or changing repayment arrangements may affect your credit profile differently. Check the implications before proceeding.
Consolidation may help combine multiple eligible dues into one repayment, while refinancing replaces an existing loan with a new one. Compare the total cost and terms before choosing.
LoansJagat's Financial Peace Score assesses your broader financial position and provides personalised AI-powered loan optimisation plans. You can explore options such as consolidation, refinancing and restructuring, and compare offers from 50+ banks and NBFCs, subject to eligibility and lender terms.