By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
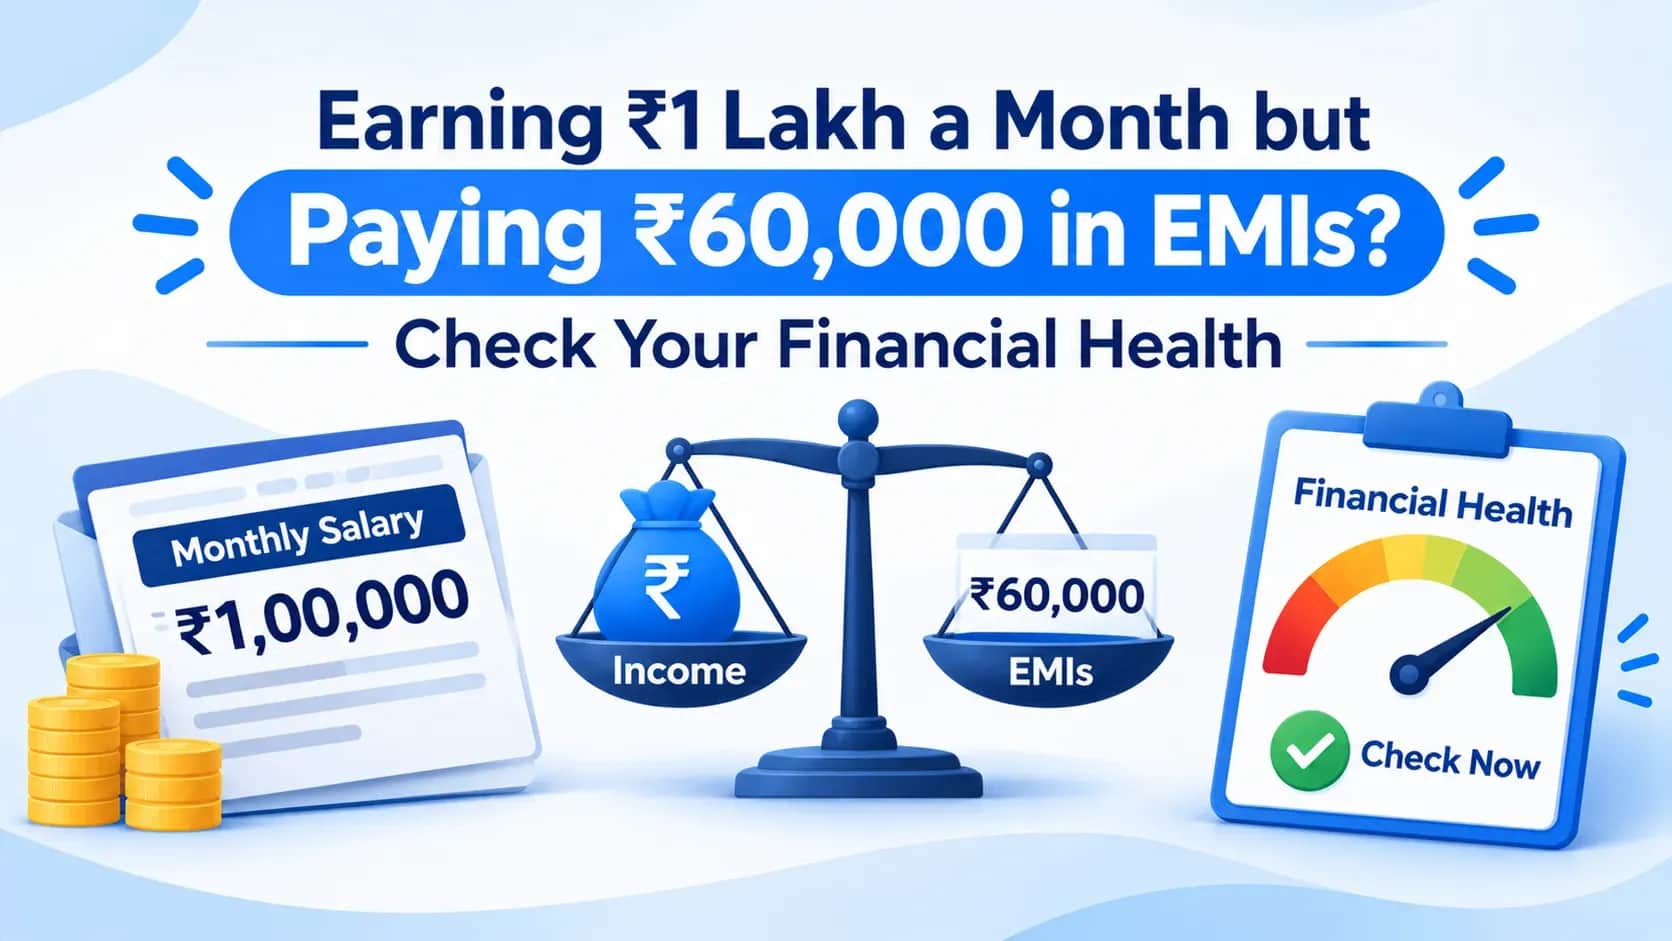
A monthly income of ₹1 lakh may seem comfortable, but the amount left after loan repayments matters just as much. If ₹60,000 goes towards EMIs, you have only ₹40,000 remaining for household expenses, savings, emergencies and other financial needs. This does not automatically mean your finances are unhealthy, but it is worth reviewing how much of your income is committed to repayments. Understanding your EMI-to-income ratio can help you assess whether your current loan commitments leave enough room for other financial priorities.
Key Takeaways
If your monthly income is ₹1 lakh and your total EMIs amount to ₹60,000, you spend 60% of your income on loan repayments. The calculation is simple:
EMI-to-income ratio = (Total monthly EMIs ÷ Monthly income) × 100
In this example:
This means more than half your monthly income is already committed to loan repayments. The remaining ₹40,000 must cover rent, groceries, utility bills, transport, insurance, savings and other expenses.
Whether this arrangement is manageable depends on your living costs, household responsibilities, savings and other financial commitments.
Your EMI-to-income ratio helps you understand how much of your income is committed before you account for everyday expenses.
Monitoring it can help you identify financial pressure early and make more informed borrowing decisions.
When a large share of your salary goes towards EMIs, you have less flexibility to manage other expenses.
For example, a person paying ₹60,000 in monthly EMIs may find it difficult to manage a sudden medical expense or an increase in household costs without using savings or additional credit.
Before taking another loan, consider whether your current income can support an additional EMI.
A new repayment may appear affordable on its own. However, when combined with existing EMIs, it could put pressure on your monthly budget.
Your savings depend on what remains after loan repayments and essential expenses.
If most of your income goes towards EMIs, you may find it difficult to build an emergency fund or save for future goals.
Your financial circumstances may change over time. A loan that was manageable earlier may become difficult to accommodate after a change in income or expenses.
Reviewing your EMI commitments can help you identify whether your current repayment arrangements still suit your financial position.
An EMI-to-income ratio of 60% indicates that a significant part of your income goes towards repayments. However, there is no single percentage that determines whether every borrower can comfortably manage their EMIs.
Lenders may use their own eligibility calculations, including the Fixed Obligation to Income Ratio (FOIR), when assessing loan applications. FOIR considers existing fixed monthly obligations in relation to income. The acceptable level can vary by lender, loan type and borrower profile.
Your personal financial comfort also depends on factors beyond lender eligibility.
Consider two people earning ₹1 lakh per month:
Both earn the same salary and have the same non-loan expenses. However, Person B has more room for savings, emergencies and other financial goals.
This example shows why income alone does not determine financial comfort. Existing repayments and everyday expenses also matter.
If your EMIs leave limited room for other financial priorities, review your existing loan arrangements before taking on additional credit. Here are a few options worth exploring.
List all your loans, including their outstanding balances, interest rates, remaining tenures and monthly EMIs.
Check whether the current terms still suit your financial situation. Also account for processing fees, foreclosure charges and other applicable costs before considering a change.
 Apply Now
*T&C Apply
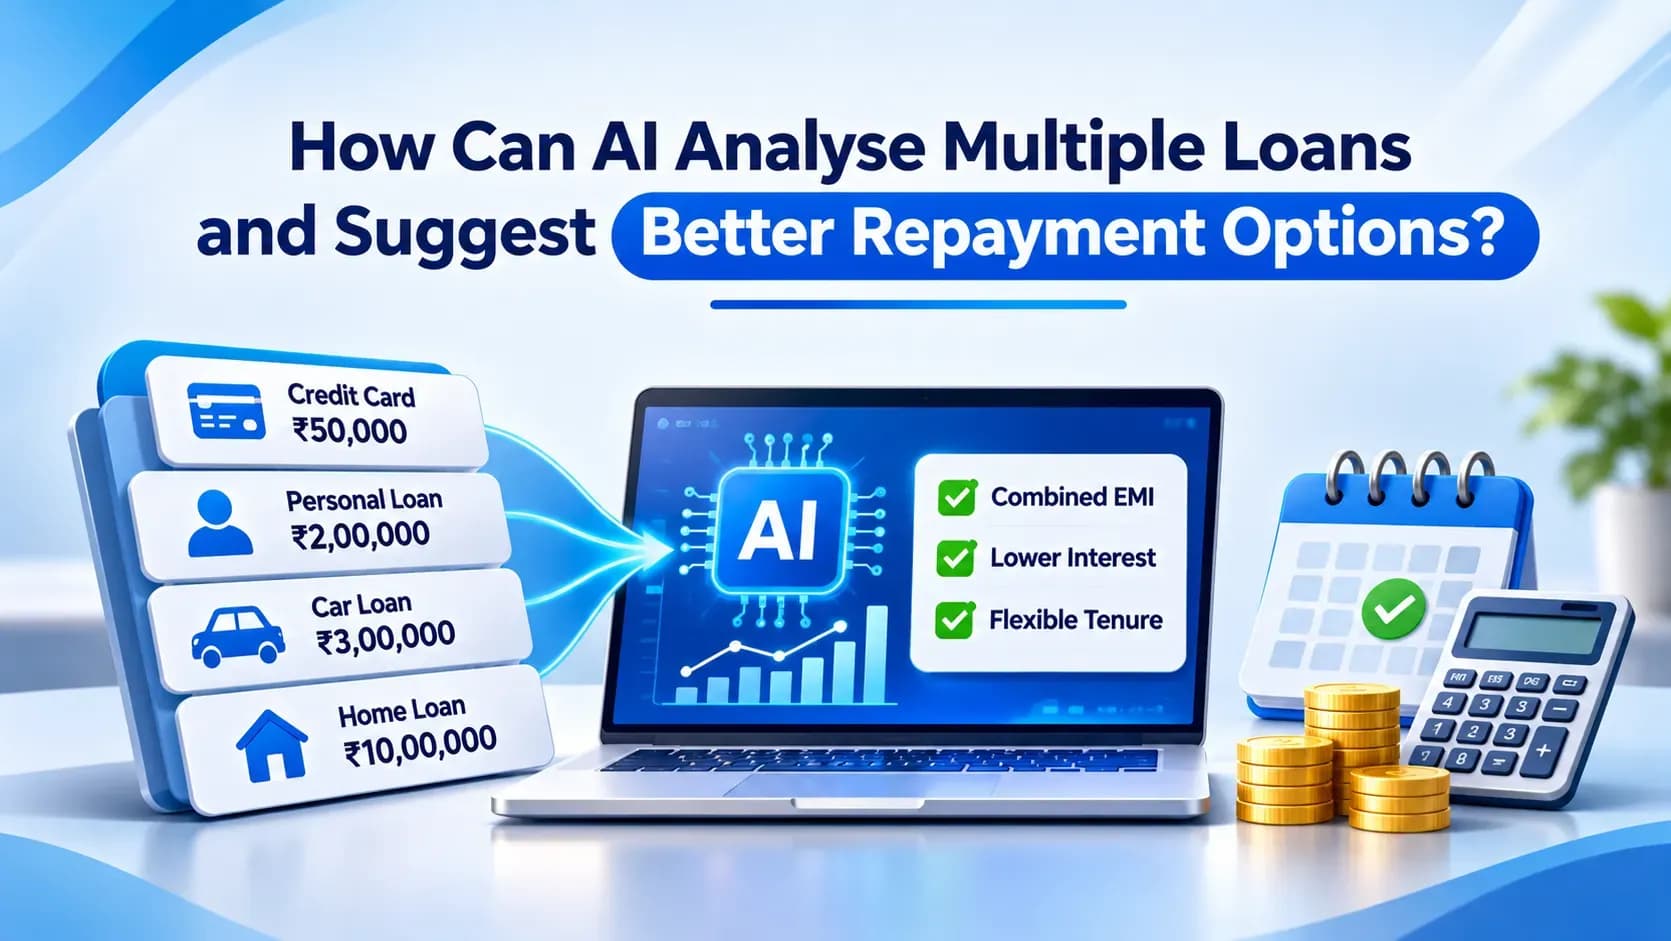
If you are managing multiple loans or credit card dues, consolidation may allow you to combine eligible outstanding amounts into one loan.
This could make repayments easier to track and may change your monthly EMI. However, compare the total repayment cost and new loan terms before proceeding.
If your existing loan has a relatively high interest rate, you may explore refinancing options from other lenders.
Compare the available interest rates, processing fees, foreclosure charges and remaining tenure. A lower EMI should not be the only reason to switch.
If your current repayment schedule is difficult to manage, contact your lender to understand whether restructuring is possible.
Depending on the lender's policies, revised terms may involve changes to your repayment schedule or tenure. Any change requires lender approval and could affect the total interest payable.
Before applying for another loan, calculate how the new EMI would affect your monthly finances.
Account for essential expenses, savings and unexpected costs. Borrow only when the repayment fits your financial capacity.
Your CIBIL score helps lenders understand your credit history and repayment behaviour. However, it does not provide a complete picture of how comfortably you manage your income, EMIs, expenses and savings.
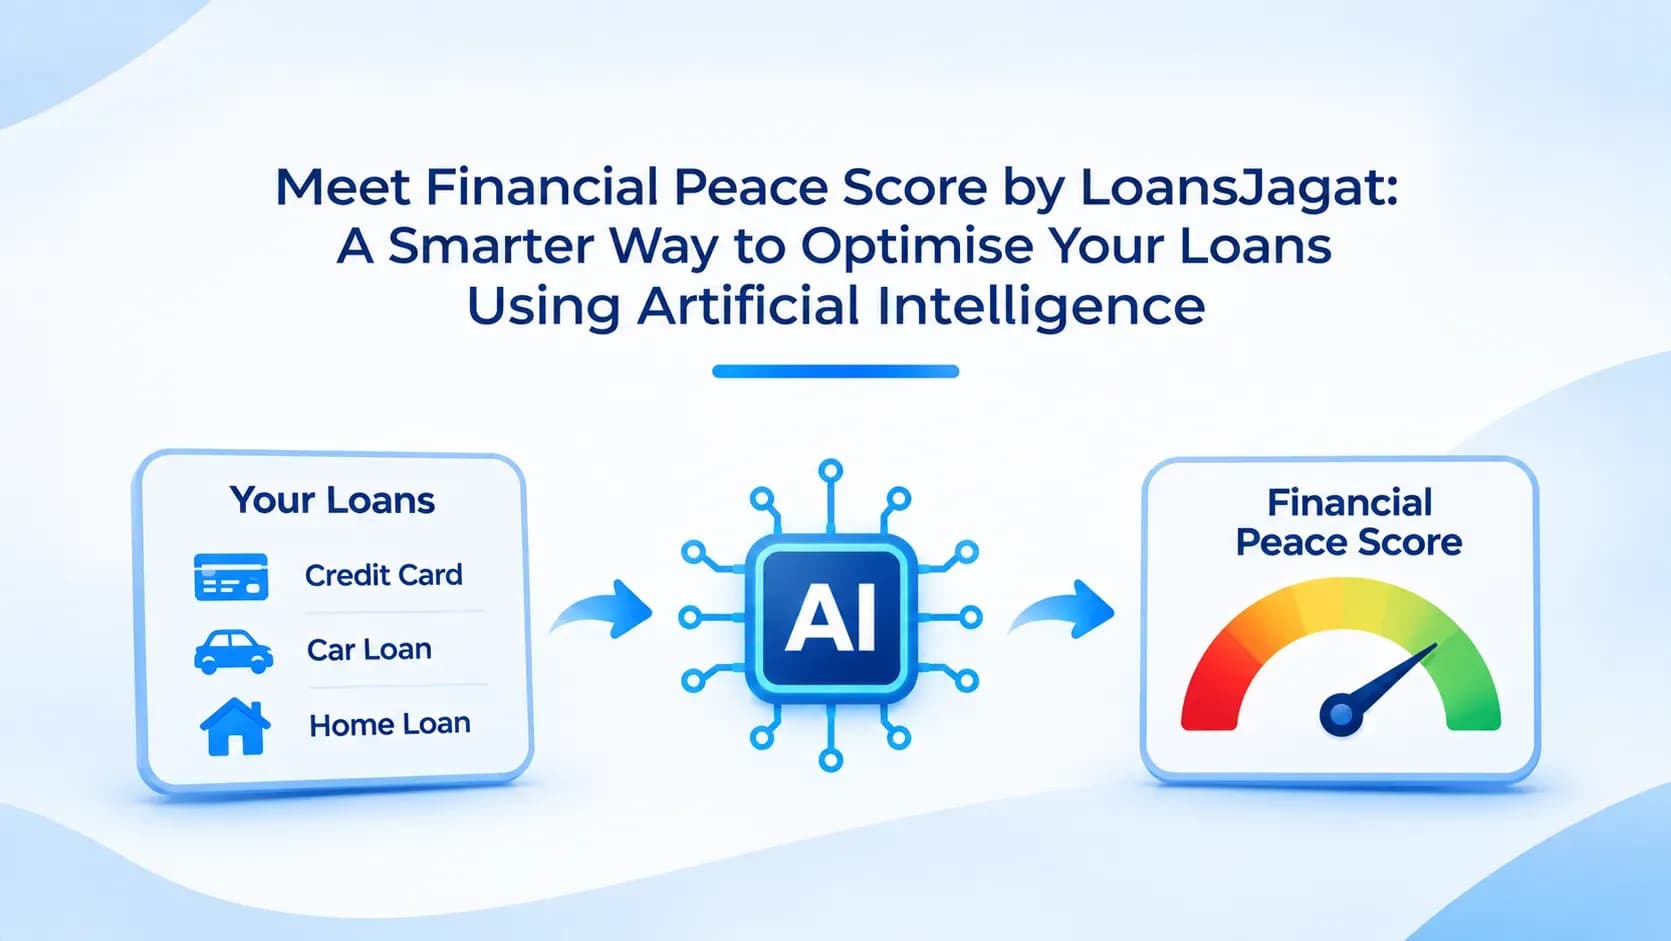
LoansJagat's Financial Peace Score looks beyond your credit score to assess your broader financial wellness.
After checking your score, you can immediately view personalised loan optimisation plans based on your financial profile. Its AI-powered platform helps identify opportunities to manage existing loan commitments through options such as consolidation, refinancing, restructuring and more.
Here is how it can help:
The availability of options and final terms depend on lender policies and eligibility. Comparing the total cost before making a decision remains important.
Earning ₹1 lakh a month does not automatically mean you have enough financial flexibility. If ₹60,000 goes towards EMIs, the remaining income must cover all your other expenses and financial priorities.
Reviewing your EMI-to-income ratio can help you understand how much of your salary is committed to repayments. You can then assess whether your existing loan terms still suit your needs. LoansJagat's Financial Peace Score helps you look beyond your CIBIL score, understand your broader financial position and explore personalised loan optimisation plans.
The EMI-to-income ratio is the percentage of your monthly income spent on loan repayments. It is calculated by dividing total monthly EMIs by monthly income and multiplying the result by 100.
It depends on your essential expenses, savings, household responsibilities and other financial commitments. A 60% ratio leaves 40% of your income for all other needs, so reviewing your budget is important.
The EMI-to-income ratio measures the share of income spent on loan EMIs. FOIR considers existing fixed financial obligations against income and is used by lenders when assessing loan eligibility.
Start by reviewing your outstanding balances, interest rates and repayment tenures. Depending on your eligibility, you may explore consolidation, refinancing or restructuring to manage your existing commitments.
A good CIBIL score reflects your credit history, but it does not fully represent your savings, monthly expenses, emergency funds or overall repayment comfort.
LoansJagat's Financial Peace Score provides a broader assessment of your financial wellness and displays personalised AI-powered loan optimisation plans. These plans help you explore possible ways to manage existing loans based on your financial profile.