
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Employees moving abroad can withdraw EPF under a specific overseas exception, but eligible EPS withdrawal benefits may still remain locked for up to 36 months.
Indians leaving the country for jobs abroad now have a specific EPF withdrawal route under the Employees' Provident Funds Scheme, 2026. The Ministry of Labour and Employment notified the scheme through G.S.R. 525(E) on 29 June 2026 in New Delhi. Paragraph 49 allows a member to withdraw the full EPF amount immediately before migrating from India for permanent settlement abroad or for taking employment abroad. The broader 12-month waiting condition for final EPF settlement does not apply to this specified overseas case.
The pension side is different. The E.P.S., 2026 was informed on 29th June 2026 by G.S.R. 527(E), provides for withdrawal benefit or issuing of Scheme Certificate to an eligible member of the Scheme who leaves before becoming eligible to receive pension. The benefit from the withdrawal is generally payable within 36 months of the member's departure from the scheme or when they reach the scheme's superannuation age, whichever is earlier. For a family paying visa charges, airfare, overseas rent deposits and other relocation expenses, expecting EPF and EPS money together could therefore create a short-term cash shortage.
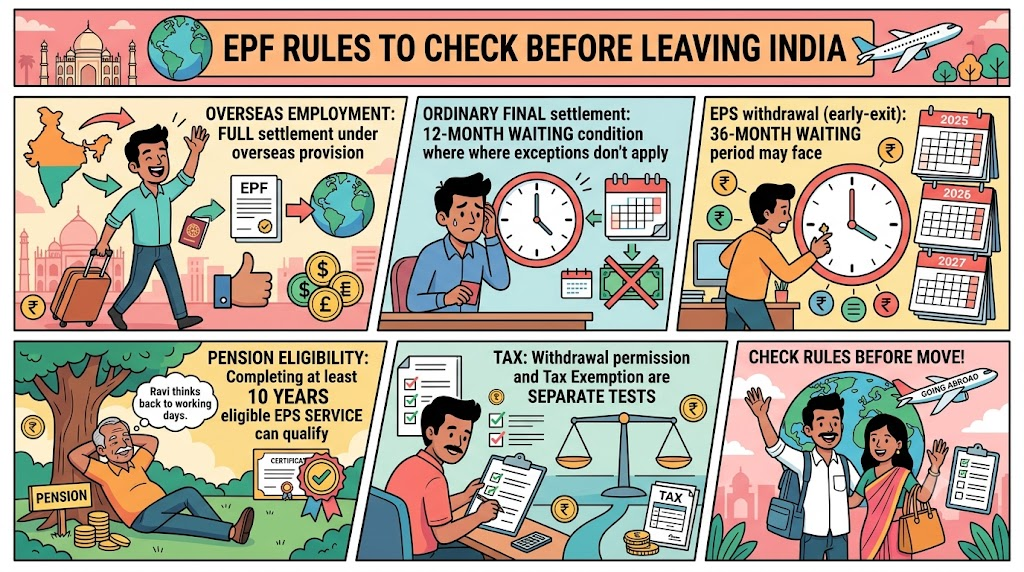
The most useful part of the 2026 change for overseas workers is the exception written into the final-settlement provision itself. An employee does not have to read the 12-month rule and assume that PF money will remain unavailable for a year after leaving India. Where the employee qualifies under the provision covering permanent migration or taking employment abroad, full EPF withdrawal is specifically allowed. That can release a large part of accumulated employment savings at a time when relocation costs are often high.
There is still a reason to slow down before filing the claim. Employees commonly refer to their EPF and EPS balances together as "PF", although the 2 benefits work differently. A worker with less than 10 years of eligible pension service may have an EPS withdrawal option, while somebody expecting to return to covered employment in India could consider preserving service through a Scheme Certificate. Employees who are already near the 10-year pension threshold need an even closer check. Closing pension service for immediate cash can affect future eligibility.
The main rules can be compared below.
That split is especially relevant for younger employees who have worked in India for only a few years before accepting positions in Dubai, Singapore, London or another overseas market. EPF may help fund the move. EPS could follow a different timeline. The employee should calculate available relocation money without automatically including the pension withdrawal amount.
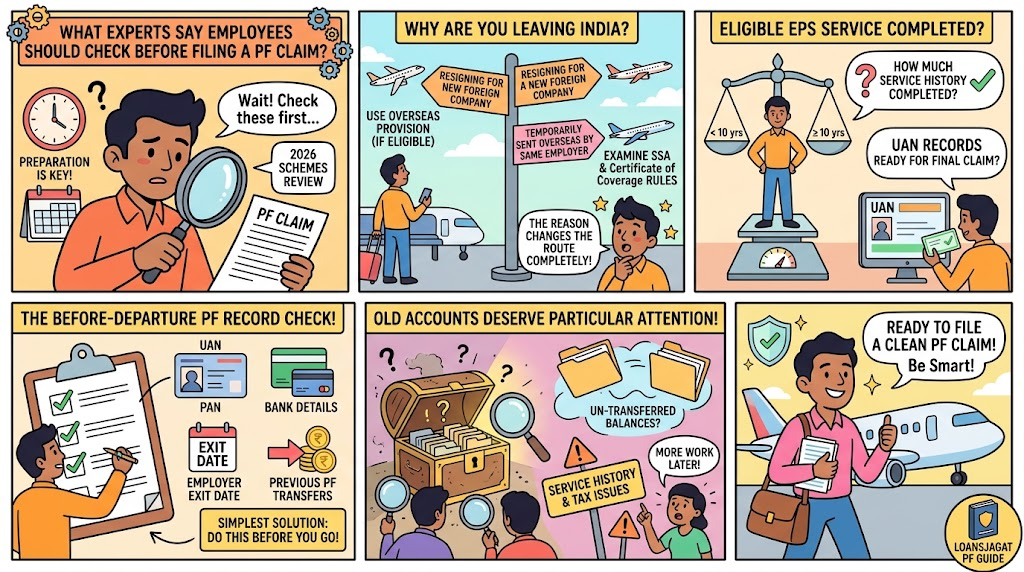
Payroll and retirement specialists reviewing the 2026 schemes have focused on 3 practical checks: why the employee is leaving India, how much eligible EPS service has already been completed and whether the UAN records are ready for a final claim. The first point changes the route completely. An employee resigning from an Indian company to join a new employer abroad may use the overseas-employment provision if eligible. A worker temporarily sent overseas by the same Indian employer may instead need to examine Social Security Agreement and Certificate of Coverage rules.
The simplest solution is to complete a PF record check before departure rather than after reaching another country. The employee should verify the UAN, Aadhaar, PAN, bank details, employer exit date and previous PF transfers. Old accounts deserve particular attention. If earlier balances were never transferred, service history and tax treatment may require more work later. The practical withdrawal process, including UAN and bank-account checks, is also explained in this LoansJagat PF withdrawal guide.
LoansJagat's view is that employees moving overseas should treat EPF and EPS as 2 separate financial decisions. EPF can provide relocation liquidity when the overseas exception applies. EPS should first be checked against past service and future pension eligibility. Using the pension component as expected moving-day cash without checking the 36-month provision can leave a gap in the relocation budget.
Tax also needs a separate check. A person can be legally eligible to withdraw EPF and still have a taxable withdrawal. The Income Tax Department's current law provides for 10% TDS on a taxable recognised provident fund payout of ₹50,000 or more where the applicable exemption conditions are not met. Continuous service of 5 years remains an important tax test, and transferred service with an earlier employer can count in qualifying cases. Income Tax Department, Section 392 of the Income-tax Act, 2025.
Read Also: Supreme Court Flags Private Access to EPFO, UAN and PAN-Linked Records
The longer withdrawal timeline had been signalled months before the new schemes came into force. On 13 October 2025, Union Labour and Employment Minister Dr Mansukh Mandaviya chaired the 238th meeting of the Central Board of Trustees, EPF, in New Delhi. The Board approved a broader restructuring of EPFO withdrawal provisions.
Among those decisions, the premature final EPF settlement period was changed from 2 months to 12 months, while the final pension withdrawal period was moved from 2 months to 36 months. The government said the change was aimed at limiting early depletion of retirement savings while leaving partial withdrawals available for members who needed access to money.
A further clarification came from the Ministry of Labour and Employment on 15 October 2025 after claims about the reforms circulated on social media. The Ministry explained that a member generally needs at least 10 years of EPS membership to qualify for pension at retirement. It also argued that withdrawing pension accumulation too early ends membership and can reduce future pension protection.
The new EPF, EPS and Employees' Deposit-Linked Insurance schemes were later approved by the Central Board at its 239th meeting on 2 March 2026 as part of the shift to the Code on Social Security, 2020. The final EPF and EPS notifications followed on 29 June 2026.
That sequence explains why a worker leaving India may come across conflicting advice online. Older guides still refer to a 2-month final-settlement rule. Other pages repeat the newer 12-month period without discussing the overseas exception. The actual 2026 provision needs to be read according to the employee's reason for exit.
Moving overseas in 2026 does not automatically force an employee to leave the full EPF balance untouched for 12 months. The new scheme contains a specific provision allowing full withdrawal immediately before eligible permanent migration or taking employment abroad. That can be useful when a worker needs access to savings for a genuine relocation.
EPS needs more patience. An eligible member leaving before pension qualification can face the 36-month withdrawal-benefit rule, while somebody approaching 10 years of pension service may prefer to preserve that record. Before the flight, the safer order is straightforward: check the reason for exit, confirm EPF and EPS service separately, fix UAN and KYC records, review previous transfers and check the tax result. A few checks in India can prevent a much longer PF chase from another country.
Yes. EPF Scheme 2026 permits eligible full withdrawal immediately before permanent migration from India or taking employment abroad.
No. The 12-month general final-settlement condition does not replace the specific withdrawal provision available for eligible overseas employment or migration.
EPS 2026 delays eligible withdrawal benefits to encourage members to preserve pension service and possibly return to covered employment.
The employee should examine pension eligibility and the Scheme Certificate option before withdrawing, since closing service can affect future pension rights.
Yes. Withdrawal eligibility and income-tax exemption are separate. Service duration, transferred PF history and the applicable tax provisions must be checked.











