
By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related News
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
A consumer commission’s PF delay order shows why submission records, written deficiency notices and the 20-day settlement rule can protect retirees from avoidable financial hardship.
The Mumbai Suburban District Consumer Disputes Redressal Commission has directed the Employees’ Provident Fund Organisation to pay 6% annual interest to a retired employee after finding a 35-day delay in his provident fund settlement. PTI reported the decision from Mumbai on 9 September 2026. The claimant, a former employee of Fleet Maritime Services (India) Pvt Ltd, had sought payment of ₹14,06,272. The commission gave EPFO 45 days to comply with its order.
The order applies directly to a single claimant, but it can change how PF members preserve application records. A retiree may have assigned that money to treatment, rent, a home payment or family expenses. A delay creates an immediate cash shortage. Over time, the ruling may push EPFO offices to issue written deficiency notices. It also warns members that an incomplete application may stop the 20-day clock.
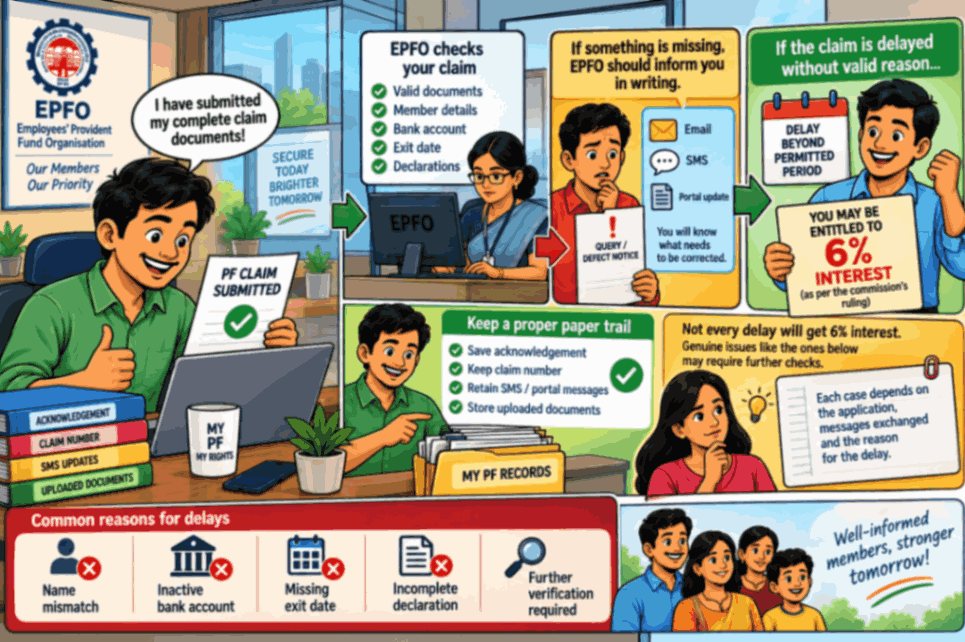
The commission’s approach gives members a useful starting point when a claim remains pending. The date of a complete submission can decide when the processing period begins. An acknowledgement, claim number, SMS or portal update can establish that date. If EPFO later says a declaration was absent, the member’s saved documents can show what was uploaded and whether the office raised the problem at the time.
There is a positive result for claimants who keep a proper paper trail. EPFO may still reject or return a claim for a genuine defect, but it should communicate that defect in writing. The ruling does not promise 6% interest whenever a claim crosses 20 days. A name mismatch, inactive bank account, missing exit date or incomplete declaration can require further checks. Each dispute will turn on the application, the messages exchanged and the reason for the delay.
Economist and Economic Advisory Council to the Prime Minister member Sanjeev Sanyal discussed faster PF processing and accountability under the 2026 framework in July. He highlighted the 12% penal interest provision where an official delays a complete claim beyond the permitted period without sufficient cause. That rule is separate from the commission’s 6% award.
Prevention starts before the application goes online. The name against the UAN should match Aadhaar, while the bank account must remain active and correctly seeded. Joining and exit dates also need checking. A LoansJagat analysis of the EPFO claim finds that the strongest lesson is evidentiary: save the acknowledgement, uploaded files, deficiency request and later submission. A borrower waiting to close expensive debt may pay extra interest during a 35-day delay.
The employee said he submitted a complete application on 19 October 2016. EPFO said the joint declaration was absent, the papers were returned on 7 November and completed documents reached its office only on 2 December.
EPFO released ₹14,06,272 on 14 December. It argued that payment came within 20 days of receiving the completed application. Yet no written rejection or deficiency communication showed that EPFO had notified the employee after the October filing.
The timeline below shows where the 2 versions separated.
The commission found that EPFO had failed to establish that the 19 October claim was incomplete. It used that filing to count the delay. Payment arrived later, but EPFO could not support its reason for shifting the starting date to 2 December.
The employee will not receive 6% of ₹14.06 lakh for a full year. The annual rate covers only 35 days. A simple 365-day calculation places the interest near ₹8,091, though the compliance figure may differ slightly.
The government had already shortened the PF claim-settlement period before this employee applied. Gazette Notification G.S.R. 525(E), issued on 2 July 2015, reduced the earlier 30-day period to 20 days for a claim complete in all respects. That timing shaped the commission’s calculation. The employee filed on 19 October 2016, and the delayed period was counted from 9 November.
A Ministry of Labour and Employment release, originally issued on 31 May 2021, also states that complete claims carried a statutory 20-day requirement. The release dealt with COVID-19 advances and set a 3-day processing target for eligible pandemic claims. That faster target did not convert every PF application into a 3-day claim.
In Regional Provident Fund Commissioner versus Shiv Kumar Joshi, decided on 14 December 1999, the Supreme Court held that a PF member could be treated as a consumer and fund administration amounted to a service.
The Press Information Bureau reported on 27 January 2023 that Nidhi Aapke Nikat 2.0 had launched across 685 districts. Monthly camps allow members, pensioners and employers to raise unresolved complaints with EPFO officials.
The retiree maintained that his 19 October application contained the required documents. His complaint covered the gap between the deadline that followed and payment on 14 December.
EPFO said the joint declaration was absent, the papers were returned on 7 November and the complete set came on 2 December. It argued that the 14 December payment fell inside 20 days from the later date.
The commission rejected that defence because EPFO could not produce supporting written communication. It found deficient service and ordered 6% annual interest on ₹14,06,272 for 35 days.
The order also recognised the hardship caused when retirement money arrives late. It placed responsibility on EPFO to process a complete claim on time or record why it could not.
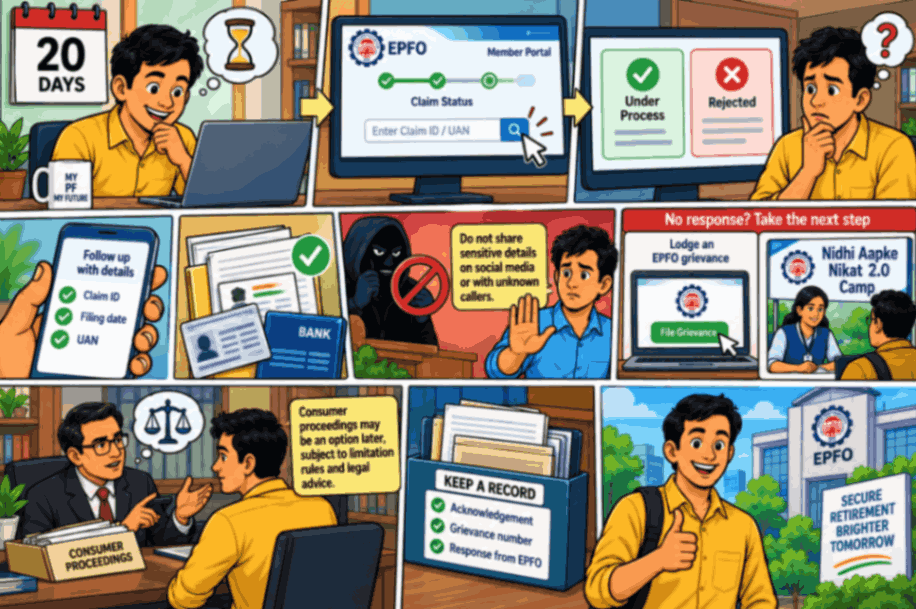
The member should check the online status and look for any rejection message. A follow-up should quote the claim ID, filing date and UAN. The acknowledgement, identity documents and bank proof should remain ready. Sensitive details must not be shared on social media or with unknown callers.
Where no useful response arrives, the member can lodge an EPFO grievance or visit a Nidhi Aapke Nikat 2.0 camp. The grievance number and response should be saved. Consumer proceedings may become an option later, subject to limitation rules and legal advice.
The ₹14.06 lakh PF dispute grew from a short payment delay into a case lasting several years. The retiree relied on the 19 October 2016 application. EPFO relied on a later date, 2 December, when it said the complete papers arrived. Missing written communication decided which version the commission accepted.
PF members do not need complicated files to protect themselves. They need dated ones. The UAN profile should be checked before filing, while the acknowledgement, uploaded documents and every deficiency message should be kept afterwards. If a complete claim crosses the prescribed period, a documented follow-up can carry far more weight than repeated calls with no record.
No. The Mumbai commission granted 6% annual interest after finding a 35-day delay in this specific claim. Another member must show that the application was complete and that EPFO lacked sufficient cause for taking longer.
At 6% per annum for 35 days, interest on ₹14,06,272 is approximately ₹8,091 using a 365-day calculation. The amount is far lower than 6% for a complete year.
EPFO can identify an incomplete claim, but written communication helps prove when it found the defect and informed the member. In this dispute, the absence of such proof weakened EPFO’s defence.
The member should check for a deficiency message, save the current status and raise a formal grievance with the claim details. A delayed status alone does not prove eligibility for interest.
EPFO said the original application lacked the declaration and relied on that point to calculate the deadline from 2 December. The commission rejected the argument because EPFO could not prove that it notified the claimant in writing.












