By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author

Arshathul Afia
Arshathul Afia is a journalism graduate and fintech content writer with 4+ years of experience in digital publishing and research-led writing. She has written 200+ articles covering personal finance, lending, banking, digital payments, credit, insurance, and major financial developments in India. At LoansJagat, she focuses on simplifying complex fintech news, RBI updates, loan-related changes, policy developments, and industry trends for everyday readers. Her journalism background helps her approach stories with research, context, and clarity, while her SEO experience ensures content remains discoverable and relevant. She aims to make financial news easier to understand, practical, and useful for readers across India.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
SBI Research estimates India may draw up to $85 billion through foreign-currency routes in 2026, giving banks more dollars and rupee relief for households too.
SBI Research sees up to $85 billion coming through the RBI-backed foreign-currency facility. The report involves SBI Research, Indian banks, non-resident Indian depositors and overseas borrowing routes. It came at a time when the rupee, crude oil and foreign capital flows were being watched closely in Mumbai, New Delhi and global currency markets.
The short-term impact can be positive for India because more dollars can support liquidity and reduce pressure during volatile trading weeks. A steadier rupee can also soften imported inflation pressure, especially when oil prices move up. The longer-term risk is different. If banks raise deposits only because the temporary window looks attractive, they may face renewal pressure later. A large foreign-currency inflow needs careful handling; otherwise the stress can return when deposits mature.
For Indian households, this may first show up through the rupee and imported costs. India pays for crude oil, some electronics, machinery, and several raw materials in foreign currency. When the rupee weakens sharply, import bills become heavier. That can travel into fuel, logistics and retail prices after some time. More dollar inflows do not cut prices overnight, but they can help reduce sudden currency pressure.
The positive side is wider than currency trading. If banks get stronger dollar flows from NRIs and overseas borrowings, the financial system gets more foreign-currency comfort. That can help during weeks when foreign investors sell Indian assets or crude prices spike. For NRIs, FCNR(B) deposits offer a way to keep money in foreign currency with Indian banks. LoansJagat explained after the June 8 opening that the window was aimed at drawing NRI dollar deposits and supporting rupee stability. That borrower and depositor angle is important because retail users often read this policy through bank rates, loan pricing and remittance decisions, not through forex jargon.
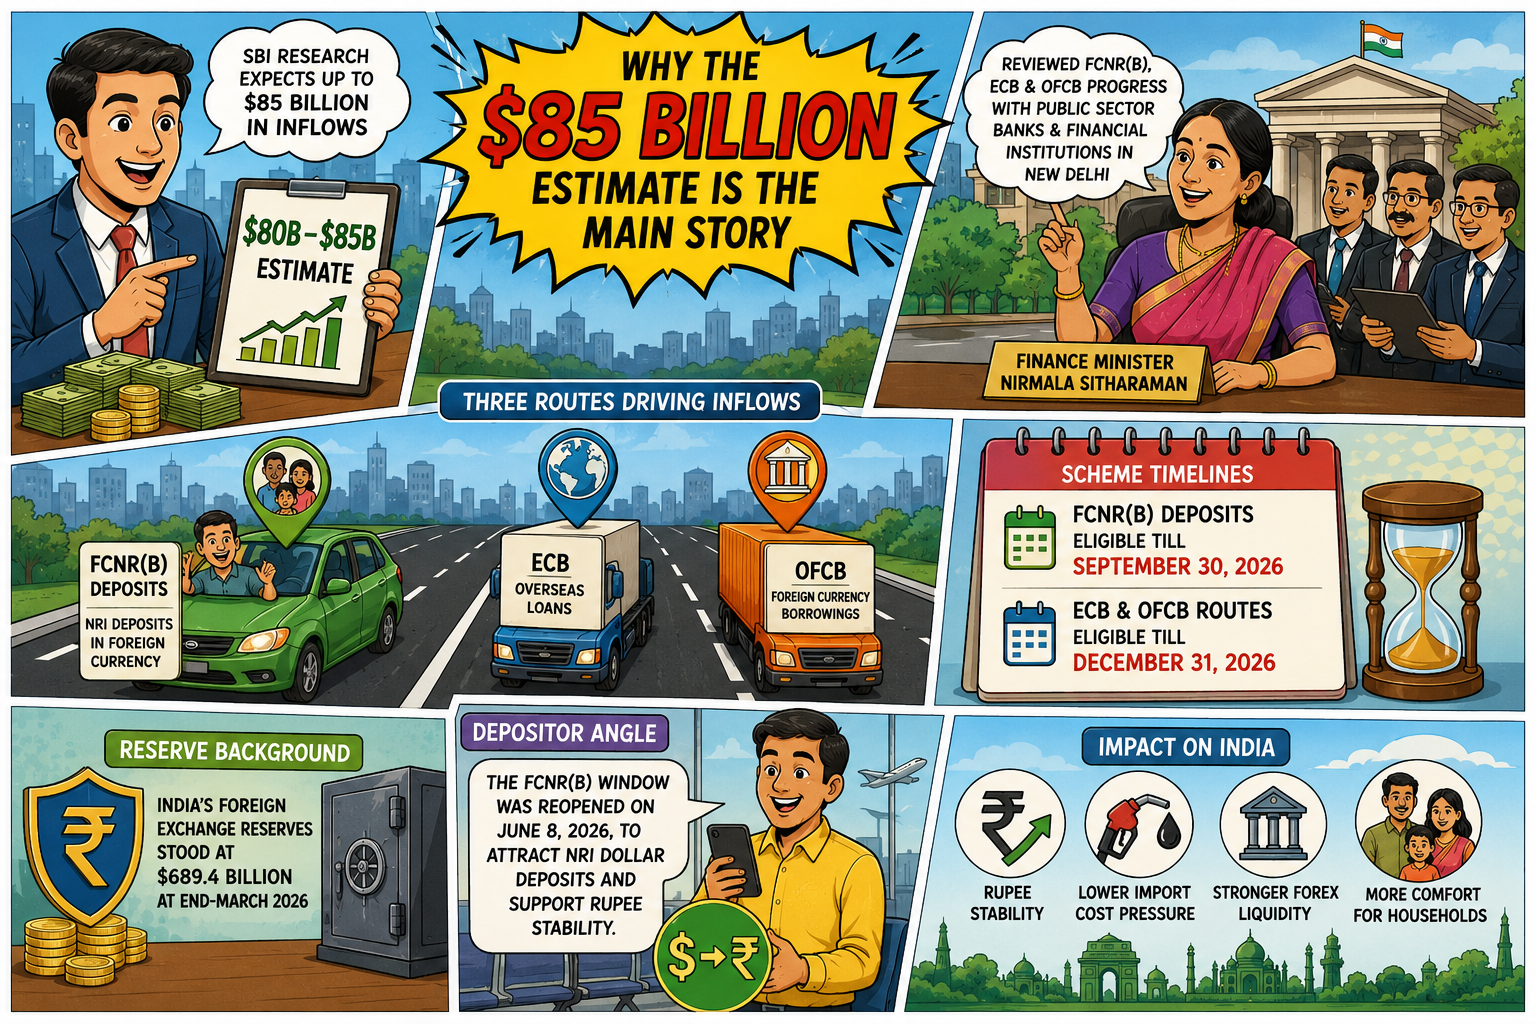
The fresh attention comes from SBI Research’s Ecowrap estimate. The report says FCNR(B) deposits alone may bring $65 billion to $70 billion, while the total amount through FCNR(B), ECB and OFCB routes may reach $80 billion to $85 billion. That figure is still an estimate. It should not be read as an official final number. The real outcome will depend on bank mobilisation, NRI response, overseas borrowing plans and global dollar conditions.
The scheme has 3 lanes. FCNR(B) deposits are the retail-heavy NRI lane. ECBs are overseas loans raised by eligible Indian borrowers. OFCBs are foreign-currency borrowings by eligible overseas branches or banks. The government has pushed banks to use all 3, but FCNR(B) is carrying the early story.
India already had a large reserve buffer, but the government still wanted more active foreign-currency mobilisation because currency pressure can arrive quickly. A reserve stock helps. Fresh inflows help differently. They improve market comfort when pressure is current, not only historical.
SBI Research has taken the stronger view among recent estimates by placing the possible inflow at $80 billion to $85 billion. Its projection depends heavily on FCNR(B) mobilisation. That means banks will need to keep NRI outreach active across the Gulf, Singapore, Hong Kong, the UK and the US. The Press Information Bureau release dated July 13, 2026, also said banks reported healthy interest from these NRI markets during the Finance Minister’s interaction with bank chiefs.
The fix is not only higher deposit rates. Banks need to avoid pushing leveraged FCNR(B) products too aggressively because a product sold badly can create problems later for depositors and lenders. A safer approach would be simple pricing, proper risk explanation and strong maturity planning. For borrowers, the analysis is straightforward. A stronger rupee environment can support rate stability, but it does not guarantee cheaper loans by itself. Loan pricing still depends on bank funding costs, credit quality, competition and future monetary policy.
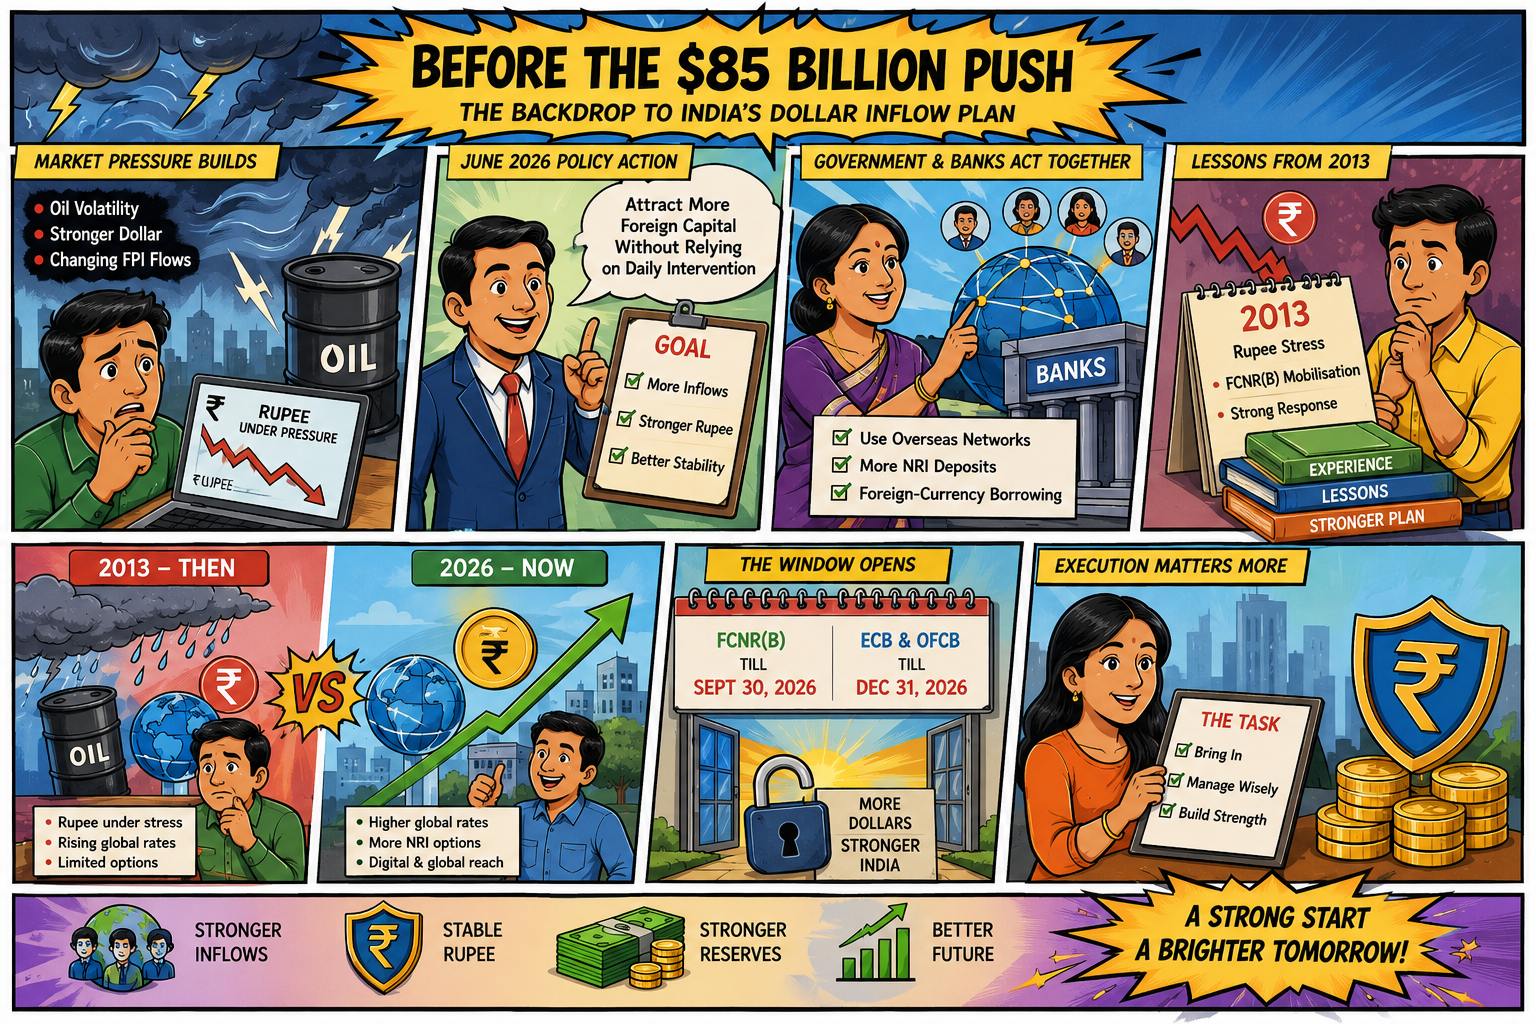
The scheme followed a period of pressure on emerging-market currencies. Oil volatility, stronger dollar trades and changing foreign portfolio flows had made the rupee sensitive. The June 2026 policy action was meant to attract more foreign capital without relying only on day-to-day currency intervention. The government also wanted banks to use overseas networks more actively, especially for NRI deposits and foreign-currency borrowing.
Earlier, India had used FCNR(B)-linked mobilisation during rupee stress in 2013. That earlier episode remains a reference point for bankers, but the 2026 setting is different. Global rates are higher, NRIs have more overseas options, and Indian banks must compete harder for dollar deposits. That makes execution more important than the announcement. A policy window can open the door. Banks still have to bring money through it.
Finance Minister Nirmala Sitharaman’s July 13, 2026 meeting with public sector banks gave the official push. According to Press Information Bureau, she asked banks to strengthen outreach to NRIs and use GIFT City more actively. Bank chiefs told the minister that they were seeing interest across FCNR(B), ECB and OFCB channels. That gives the scheme a government-bank-market connection, not only a central bank angle.
SBI Research’s view adds the market estimate. Its $85 billion upper projection has made the scheme newsworthy because it links inflows with the balance of payments, rupee comfort and bank funding. The useful reader-level takeaway is this: if the estimate plays out, India gets extra foreign-currency strength in FY27. If the inflow slows after the first rush, the scheme still helps, but the bigger headline will look stretched.
India’s dollar-inflow plan has moved from a policy action to a market story. SBI Research’s $80 billion to $85 billion estimate gives the scheme a bigger frame because it points to stronger NRI deposit mobilisation, bank participation and possible support for the rupee.
The next test is follow-through. Banks need to bring in deposits without overselling risk. NRIs need fair pricing and clean product terms. For India, the benefit is extra foreign-currency comfort during a volatile year. The warning is also simple. A fast inflow can help today, but only careful renewal and repayment planning will decide how useful it remains later.
SBI Research estimated that India may attract up to $85 billion through foreign-currency routes.
SBI Research gave the estimate in its Ecowrap report, reported by Business Standard on July 27, 2026.
FCNR(B) is a foreign-currency deposit account that NRIs can hold with Indian banks.
They are leading the expected inflows because NRIs can keep deposits in foreign currency.
A steadier rupee can reduce imported cost pressure, especially in fuel and transport-linked prices.
Not directly. Loan rates depend on bank funding costs, credit risk and future policy decisions.
The risk is heavy dependence on temporary inflows that may create pressure when deposits mature.












