By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
‘Simplify Finance for Everyone.’ This is the common goal of our team, as we try to explain any topic with relatable examples. From personal to business finance, managing EMIs to becoming debt-free, we do extensive research on each and every parameter, so you don’t have to. Scroll up and have a look at what 15+ years of experience in the BFSI sector looks like.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
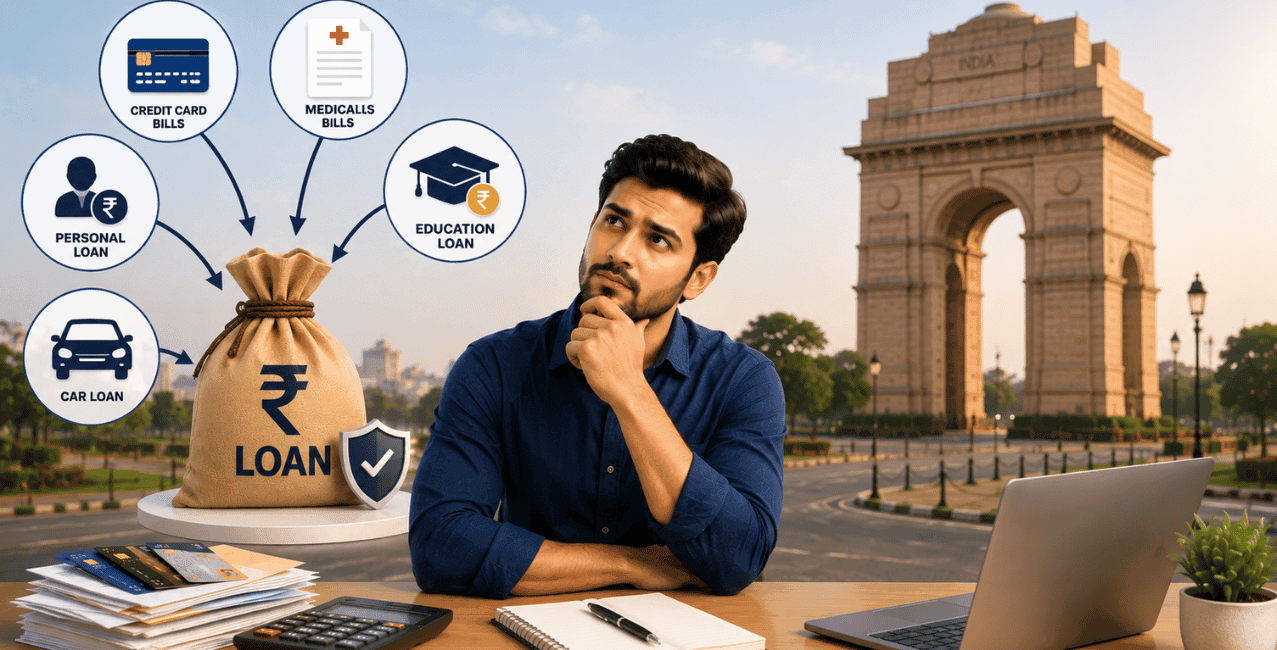
Debt is not a problem if you can pay it easily. But if you have multiple loans and credit card bills pending, it becomes difficult to manage. You get confused while understanding EMIs, interest rates and due dates. In this situation, a debt consolidation loan becomes a good option. You can combine your multiple loans and get one personal loan, which is called a debt consolidation loan. This loan is used to pay off previous multiple loans. Now you don't have to deal with multiple EMIs and due dates monthly. In this article, we are going to understand when you should consider a debt consolidation loan.
Key takeaways
You use a credit card when you need urgent money. But you must also be aware that borrowing money without proper planning can lead to debt problems. Especially when you use multiple credit cards. When you make payments, it becomes difficult to manage due to high interest and different due dates.
If you're struggling with several credit card payments and loan payments, debt consolidation loans can definitely help by combining them into a single monthly payment.
Debt consolidation is used when you are struggling with multiple loans. It simply combines all your loans and turns them into a single payment. So that you can pay it on time. It's not the only reason why you should consider debt consolidation. There are many different benefits of debt consolidation.
It can help you pay off multiple debts at once, reduce the stress of managing different EMIs, and make your repayments easier. In some cases, you don't even have to take a new loan. You can choose options like a balance transfer to manage your existing debt more effectively.
Here I am telling you the seven common signs that indicate it may be the right time to consolidate your debts.
1. When most of your income goes towards EMIs
It is difficult to manage several EMIs each month. Every EMI has different due dates, which can increase the chances of missing a payment.
Here is why Aarav needs debt consolidation
Aarav is a marketing professional. He has three credit card balances.
Read More - How can I get a consolidation loan
Aarav takes a debt consolidation loan of ₹6,00,000 at an interest rate of 12% for 40 months. His new EMI is approx ₹18,000, which is lower than the ₹21,500. This reduced his monthly EMI amount by ₹3,500.
Instead of paying three credit card bills with high interest, Aarav now pays one lower EMI and saves money on interest.
2. When You Have Multiple Loans or Credit Card EMIs
Multiple loans are difficult to manage, you have to pay EMI separately, remember each due date, and calculate the outstanding amount. As compared to multiple loans, single debt is always easy to manage. Also, if you have a good credit profile you can get a new personal loan on less interest which will save your money.
For example:
If you have ₹2,00,000 loan from 3 credit cards with 30% interest rate for 24 months.
Total interest paid: ₹2,68,662.48 - ₹2,00,000 = ₹68,662.48
You decide to get a new debt consolidation loan of ₹2,00,000 on 15% interest rate for 24 months.
Total interest: ₹2,32,736.40 - ₹2,00,000 = ₹32,736.40
This way you save interest= ₹68,662.48 - ₹32,736.40 = ₹35,926.08
This is how debt consolidation can help you.
3. When You Have a Clear Plan to Avoid New Debt
Debt consolidation works best for you when you want to be debt-free and improve your spending habits. It combines your multiple debts into one single debt with lower interest. It makes your repayment easy and manageable. When you avoid taking on more debt unless it's necessary, only then can you get the full benefit of debt consolidation.
When you miss EMIs, it can result in late payment charges and negatively affect your credit score. And if you're frequently paying late EMIs because of multiple repayment schedules, consolidating your debts can make repayment easier and more organised.
5. When you keep paying only the Minimum Amount
This is the big red flag in loan payments. Paying only the minimum amount due on your credit card is one of the biggest signs that you may need debt consolidation. Your minimum payment only covers interest and charges, so only a small portion of the debt is covered. As a result, it takes years to repay the balance.
If you are unable to pay the full amount every month, debt consolidation can help you combine your debts into one loan with a lower interest rate.
*T&C Apply
This can make repayments easier and reduce your financial stress. If you continue paying only the minimum amount, losing your job or facing any financial emergency could make it even harder to manage your debt. So, debt consolidation is the best option for you.
6. When You Want Better Control Over Your Budget
It is difficult to manage daily expenses with multiple loans, especially when you have been managing them for a long time. It can obviously give you anxiety even if you have a stable income. This can create financial pressure and make it difficult to achieve your financial goals.
If you are someone going through the same pain, debt consolidation can become the best solution for you. A debt consolidation loan can combine them into one EMI. You can easily pay one EMI.
Debt consolidation is also useful when you want to become debt-free faster. Paying EMIs for a long time can definitely make you feel frustrated. In this situation, you can go for debt consolidation just like Kartik.
Kartik, living in Bangalore, wants to repay his loans as quickly as possible. Although he pays more than the minimum amount every month, high interest rates are slowing down his progress.
Kartik's time to repay the loan is about 42 months. But he wants to be debt-free as soon as possible. So, he took out a debt consolidation loan of ₹10,00,000 at 10% interest for 2 years.
Then his monthly EMI becomes around ₹46,000, and it will take only 24 months.
If you are dealing with multiple EMIs, high-interest debt, missed due dates and want to get rid of this. You can go for a debt consolidation loan. With a debt consolidation loan, you can make only one EMI payment monthly instead of multiple. You also don't have to remember the different due dates. But you should remember that debt consolidation does not remove your principal amount. If you choose a longer tenure, it increases the total interest paid. If you choose a shorter tenure, you have to pay more EMI. That's why, before choosing a debt consolidation loan, you should compare the new interest rate, EMI, tenure, processing fees, foreclosure charges, and total repayment cost.
If you are someone who wants to ease the loan repayment journey by consolidating multiple loans, Loansjagat is here to help you. It provides one consolidated assessment of all existing loans. By comparing all the partnered banks and NBFCs it gives you the best consolidation options. A dedicated loan manager can coordinate the process. Loansjagat helps you track closure letters and NOCs after the relevant loans are settled. But the final decision depends on the eligibility, interest rates, loan terms, approval, and disbursal of the lender.
Yes, it can help. It can combine your expensive credit card balance and turn it into a lower-rate personal loan, which can reduce interest rates. Then you can get a loan with a longer tenure, which cuts your EMI. Then you don't have to pay multiple EMIs monthly. One payment is enough.
When you have multiple loans, you need to pay different EMIs on different dates. But when you combine all loans and turn them into a single debt consolidation loan, you have to pay only one EMI monthly. You can set this EMI date according to your income cycle and prevent unnecessary changes. This is how a debt consolidation loan helps you.
If you are using one credit card to pay another, you are in a cash flow cycle trap. When you get a new credit card to pay the bills of the previous one, it adds debt instead of removing it. Plus, this debt cycle can also carry hidden charges and compounding interest. That's why consolidation can be considered.
Potentially. If you qualify for a consolidation loan at a lower effective cost than some of your existing debts, combining them may reduce the interest burden. Compare interest rates, fees and the total amount payable rather than looking only at the EMI.
Usually, the main advantage of consolidation is combining multiple debts into one repayment. If you have only one loan, refinancing or restructuring that loan may be more relevant than a traditional debt consolidation strategy.
No. Consolidation changes the structure of your existing debt but does not eliminate the underlying borrowing behaviour. Taking new loans or rebuilding credit-card balances after consolidation can leave you with the new loan as well as fresh debt.
Be cautious. A lower EMI can improve monthly cash flow, but extending the tenure may substantially increase the total interest paid. Compare the total cost of the new loan with the remaining cost of your existing debts.
You can explore it, but eligibility may be affected because recent missed payments can weaken your credit profile. If you are already struggling to repay, assess the lender's eligibility requirements and the overall affordability of the proposed consolidation loan.
Your debt problem is temporary if it arises due to short term problems like medical bills. Because your regular income will cover it soon. Keeping your debt payments at or below 40–50% of your income is a general safety guideline, not a guarantee that your debt situation is safe. You need debt consolidation when your problem is long-term.
The first thing you should check before getting a debt consolidation loan is total cost. Compare the interest rate of the new loan and various charges. Then check prepayment charges. In case you are going to close this loan earlier, you will need to pay some charges on it, that's why it's important to know about them too.