By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
‘Simplify Finance for Everyone.’ This is the common goal of our team, as we try to explain any topic with relatable examples. From personal to business finance, managing EMIs to becoming debt-free, we do extensive research on each and every parameter, so you don’t have to. Scroll up and have a look at what 15+ years of experience in the BFSI sector looks like.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Other services mentioned in this article
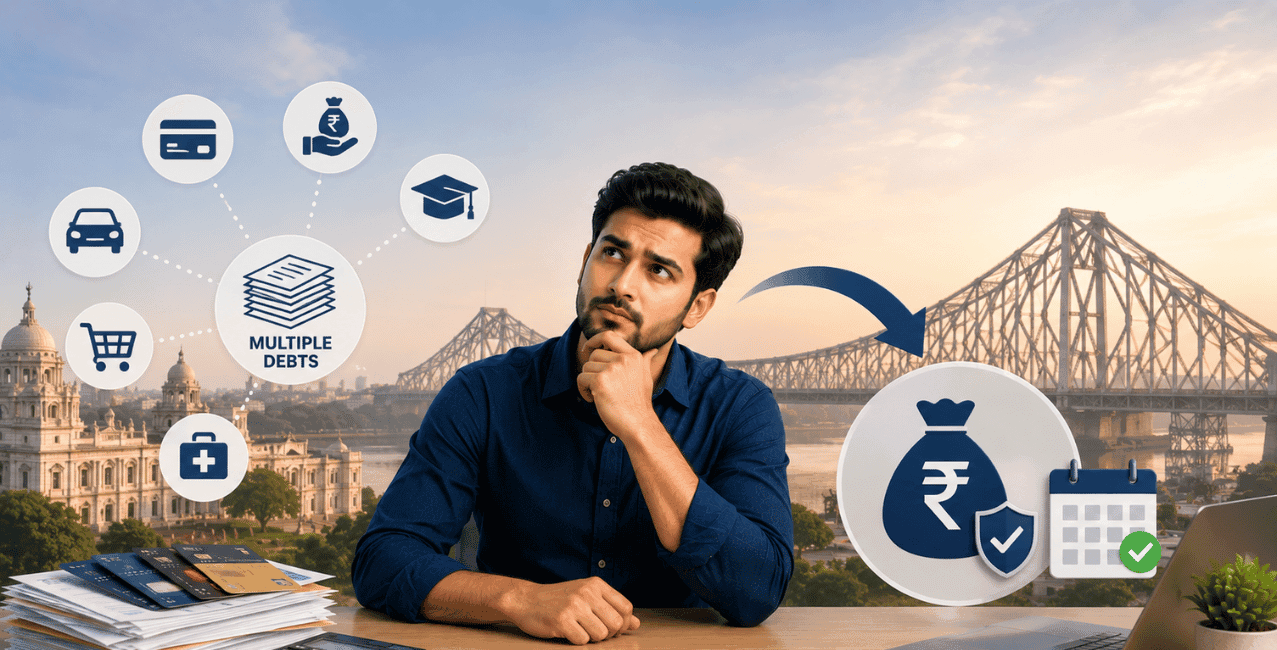
Debt consolidation and debt relief are two major concepts in banking. Debt consolidation is done when a borrower has multiple debts; after debt consolidation, those debts are combined into a single loan. This process makes it easier for borrowers to repay their loan at a very low interest rate. Whereas debt relief mostly focuses on reducing or settling the amount you owe when you are finding it difficult to repay your debts on time. The relief option is one of the most used methods by Indians. But which one is better is not clear here; both of them work differently, and the comparison depends on the borrower’s financial situation. Moreover, LoansJagat provides a one-stop place for the borrower for debt consolidation by connecting them with the right lender.
Key Takeaways:
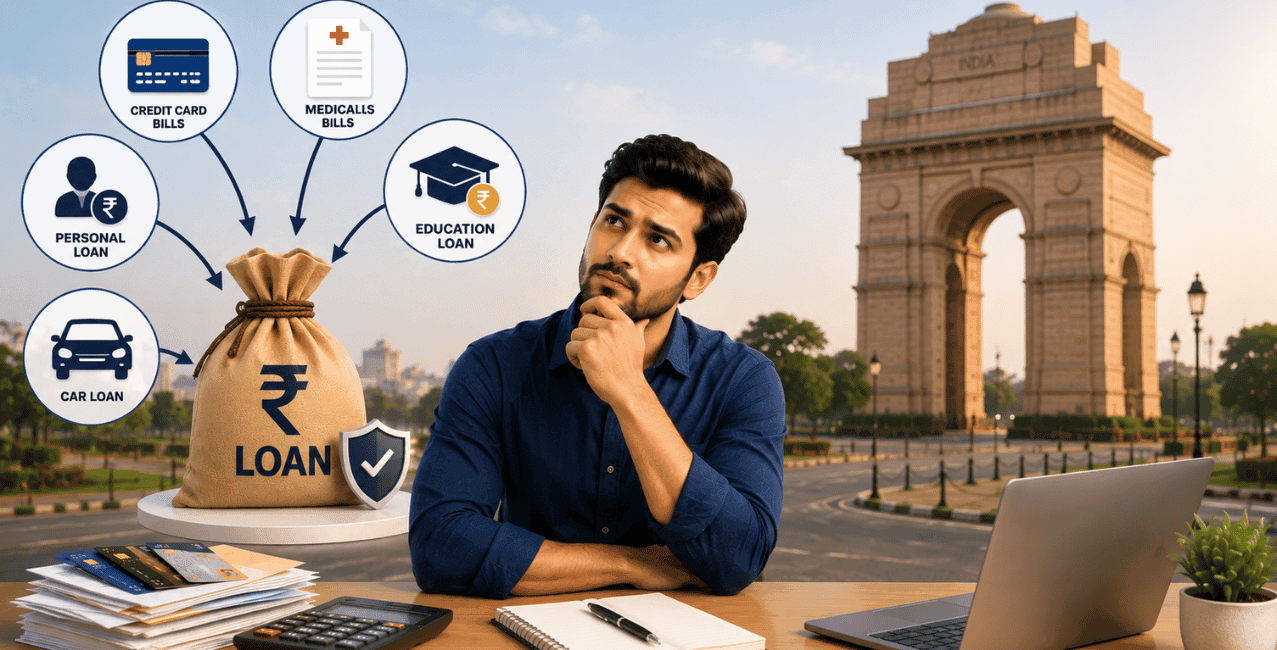
Debt consolidation is the process of combining multiple debts of the borrower into one new loan. This strategy works by keeping track of several credit cards or other unsecured debts; you repay one loan with one monthly instalment. This makes debt repayment simpler and easier to manage.
Most of the people choose a debt consolidation loan from a renowned bank or credit union or an online lender. Consolidation loans often offer lower interest rates than most credit cards when you have a good credit score. The main motive is to offer a lower interest rate, which can reduce your overall borrowing cost, while a fixed repayment schedule makes it easier to budget. Moreover, LoansJagat provides this debt consolidation facility to people by connecting them with the right lender.
One of the most special features of consolidation is that some lenders even offer to pay your existing creditors directly, and once your debts are cleared, you can make only one payment to the lender. But the downside is that consolidation does not reduce the total amount you owe; it only changes how you repay it.
As difficult as it sounds in theory, the process is fairly straightforward:
Let’s understand this with an example: Imagine you have three credit cards with different interest rates and payment dates; you can combine them into one personal loan. Instead of remembering multiple due dates, you'll have just one payment every month. This is why consolidation works best for most borrowers who have a steady income and can make regular payments.
There are several ways through which you can consolidate your debt. However, the main part depends on your financial situation. Here are two major ways that work like magic for loan consolidation:
A personal loan is one of the most common ways for debt consolidation. This method offers fixed interest rates, easy monthly payments, and repayment terms that range from one to seven years, or more in some conditions. If your credit score is good, you can qualify for a lower interest rate than what you are currently paying on credit cards.
A balance transfer loan offers flexible movement of your available outstanding loan balance to the new lender with manageable EMIs and a favourable interest rate. Several lenders in India provide this facility to people.
Debt settlement or relief is a process that mainly aims to reduce the total amount you owe. So, instead of repaying the full debt, you or a relief company negotiates with your creditors to accept a lower settlement amount. Basically, debt relief is often used by people facing serious financial hardship who cannot repay their debt at once. If the negotiation is done successfully, creditors may agree to forgive a portion of the outstanding balance after receiving the lump-sum payment. In conclusion, debt relief changes the amount you owe rather than reorganising your repayments.
Unlike consolidation, debt relief works a bit differently. Here are some steps that companies follow for a successful debt settlement:
1. Start with an assessment:
The first step is to look at your complete financial situation. This includes your outstanding debts, monthly income, regular expenses, and other financial commitments. A free initial consultation can help you understand where you stand.
2. Choose the right approach:
Once your finances are reviewed, the next step is to decide how the debt should be handled. Depending on your situation, this could involve restructuring or negotiating a settlement.
3. Join the programme:
If you move ahead, you may need to put aside a fixed amount each month in a dedicated account. The money builds up over time and can later be used to pay agreed settlements.
4. Discuss terms with creditors:
The debt relief team then contacts your lenders and works with them to find suitable repayment, restructuring, or settlement terms. They also help manage communication with the creditors during this stage.
5. Make the agreed payment:
When a creditor accepts the proposed terms, you can approve the payment from the dedicated account. It is important to get the settlement terms in writing before making any payment.
6. Complete the process:
Once all the debts included in the programme have been dealt with, the process comes to an end. You should receive the necessary documents confirming the settlements and can then focus on improving your credit record and getting your finances back on track.
Hence, this is hot debt relief works.
Both consolidation and relief include a cost or fee in return for providing you with the comfort of flexible payments. The fee may differ significantly in both cases; here is the complete information:
Debt Consolidation Costs:
Debt Relief Costs:
The companies working in the settlement process often charge a settlement fee ranging from 15% to 25% of the total debt. Since settlement negotiations can take months or even years, there is also no guarantee that creditors will agree to reduce your balances.
In most cases, debt relief and consolidation are far different from each other when it comes to affecting your credit score. One of the biggest differences between them is how they affect your credit score.
In simple words, consolidation has a limited impact on your credit score. This means that if you make payments on time and avoid taking on new debt, your credit score may gradually improve over time.
In this condition, the borrower’s credit profile plays a major role in determining which option is available and best for you:
Debt Consolidation
Most institutions and lenders need a fair to good credit score for debt consolidation loans or balance transfers, and borrowers with strong scores often qualify for lower interest rates and better terms.
Debt Relief
*T&C Apply
In the table below, we have discussed the features of both the settlement and management process:
Hence, both serve the major purposes for the borrowers related to their financial conditions. Moreover, there is no comparison to justify which is better than the other; it is totally dependent on the borrower’s financial standing and conditions. If the financial situation is hard, then debt relief can be a better option. On the other hand, if multiple EMIs become a burden, debt consolidation becomes a better option.
After reading this blog, we have understood that both consolidation and relief serve different purposes, which automatically means there is no better option between them. Both of them act according to the borrower’s financial conditions. Debt consolidation is usually taken when the borrower has too many debts in the form of credit dues, EMIs, etc. Whereas debt relief is chosen when the borrower faces intense financial hardship and is unable to pay the next instalment of an existing loan. Hence, the better option between debt consolidation and debt relief becomes totally dependent on the borrower’s financial situation.
Debt consolidation is the process of combining multiple loans into one loan to reduce the financial burden on the borrowers.
Debt relief is the action taken by the borrower to pay a lesser amount of the loan to the lender due to financial hardship.
No, not all banks provide standard eligibility for borrowers. Hence, all banks have their own eligibility and policies for providing the debt consolidation loan.
It totally depends on your financial situation. If you have multiple debts in front of you, then considering debt consolidation can be a good idea for you to reduce those burdens into one single loan.
Debt settlement is actually a form of debt relief. If you face intense financial hardship and are unable to pay the next instalment of your existing loan, then debt settlement can lower the financial burden.
Yes, one needs to pay the fees or charges before consolidating the debts. Moreover, the charges and policies related to paying fees can vary from one lender to another.
No, the credit score does not build after the debt relief process. This is because it includes processes like debt settlement, which can heavily damage the credit score.
No, there is no permission required in advance from the lender, but your lender must agree to the reduced settlement amount for debt relief.
The single similarity between debt consolidation and debt relief is that both reduce the financial stress of the borrower.
Debt consolidation initially lowers your credit score, which is very minor. This is due to the hard enquiry on your credit report and other factors. But as you regularly pay the instalment, your credit score increases.