By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Darshana Patel is a finance and tech writer with a strong background in journalism, financial economics, and political science, working with Loans Jagat. She has immense experience writing content through her previous work in fintech and edtech companies. Her contribution at Loans Jagat is to simplify finance-backed content and academically powered content for the readers.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
Debt consolidation vs loan restructuring are the two poles of the earth. Debt consolidation focuses on combining multiple debts into one for credit score building, whereas loan restructuring focuses on the reactivation of the ongoing loan through negotiation with lenders, which hampers the credit score. The only similarity is that both are practised during a financial crunch, but loan restructuring is practised during more intense financial difficulties faced by the borrowers, which is rare but possible.
Key takeaways:
Debt restructuring, which is also known as loan restructuring, is used when there is significant financial difficulty on the borrower’s side. It is mainly done through negotiating with the lender who provided the loan to the borrower.
It is completely different in comparison to debt consolidation. Debt restructuring needs complete reconsideration of the terms and policies, whereas in debt consolidation your existing debts are combined in a single loan.
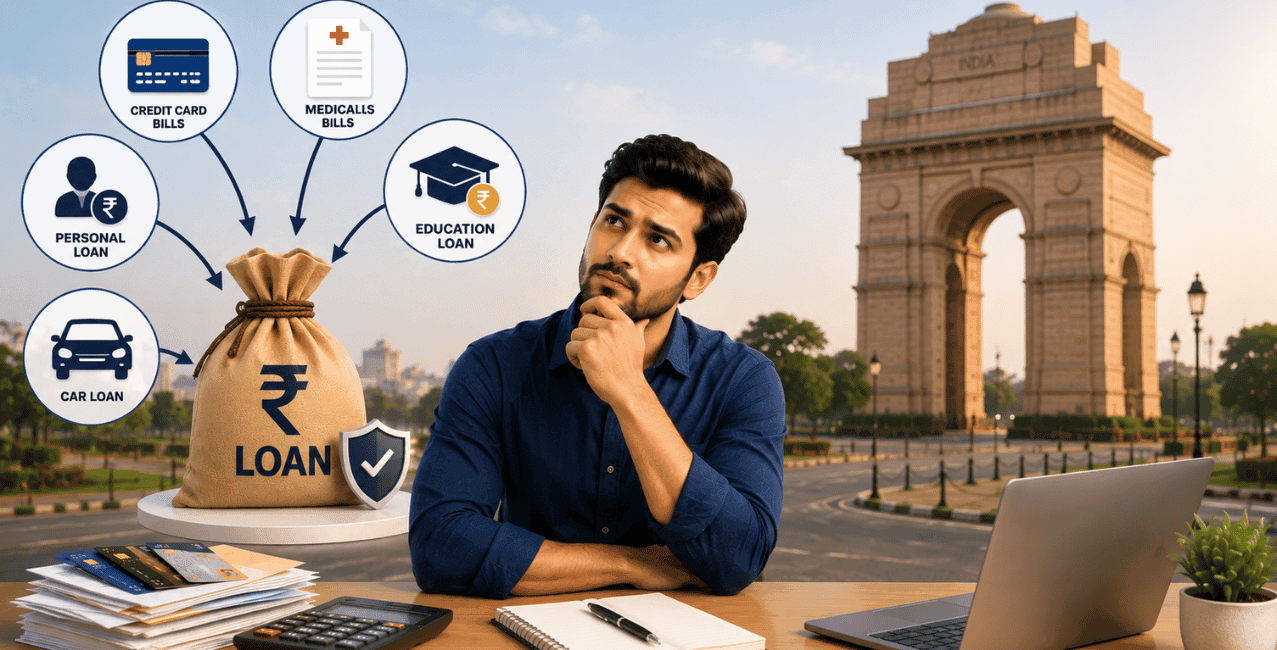
On the other hand, debt consolidation is the practice of consolidating multiple debts into one loan, and the borrower pays only a single instalment per month until the loan is repaid. But debt consolidation is not only practised in the form of taking a loan; one can also practise this through a balance transfer.
Debt consolidation is practised when one is facing a financial crunch in life and is planning to take another loan in the future. It helps borrowers to combine their multiple existing debts into one single loan. Through this, they can rebuild their financial credit score. This helps to mitigate their multiple financial burdens.
Hence, this is how debt restructuring is different from debt consolidation.
Loan restructuring has both good and bad faces, which is totally dependent on the borrower’s financial situation. But it is the difficult option one has to take to cover the debt if they face intense financial hardship. So, loan restructuring comes with a do-or-die situation.
Loan restructuring is the reactivation of the ongoing loan with the lender’s approval, which is also not guaranteed. But covering the loan is the priority, and the option that is left with the borrower in an intense financial crunch is loan restructuring.
Though loan restructuring comes with major consequences that borrowers never expected, there are certain advantages of loan restructuring.
Hence, these are the major advantages of loan restructuring.
Cons of loan restructuring need major consideration by the borrower because your credit score and your financial planning get heavily impacted.
Hence, these are the reasons why loan restructuring is not good for the borrower to overcome or relieve the debt.
A debt consolidation loan is a loan that is given by consolidating multiple loans for borrowers at a lower interest rate with longer tenures.
Pros of debt consolidation:
Debt consolidation eases repayment for the borrower, as they only need to pay a single instalment each month to cover all the multiple debts.
Hence, these are the major advantages of debt consolidation.
Though debt consolidation brings a major positive impact in terms of consolidating multiple debts, there are certain disadvantages one needs to know.
Hence, these are the major cons of debt consolidation.
The core difference between debt consolidation and loan restructuring is in terms of nature, scope, functions, and eligibility.
In economics, though, both fall under the aspect of debt management; debt consolidation and loan restructuring are different forms.
The table below shows the core difference between debt consolidation and loan restructuring:
*T&C Apply
Debt consolidation and loan restructuring have always functioned differently in every aspect and also target people with financial stress but result in different ways. One is intense in nature, and the other is slow but helpful in nature.
Hence, these are the core differences between debt consolidation and loan restructuring, where debt consolidation stands out as being better than loan restructuring.
Loan modification is usually done by people who are really going through intense financial stress by changing the interest rate or principal amount to be paid.
But how will the bank know who is really financially distressed or just wants to take advantage of the loan modification? Here come the eligibility criteria for the loan modification.
These are the eligibility criteria that one can follow to get the loan modification done:
Hence, these are the eligibility criteria for the loan modification on the existing loan taken by the borrower.
Yes, debt consolidation and loan restructuring are forms of debt management. Debt management is a broader economic concept of economics.
Debt management is the practice of managing debt through financial strategy, which includes debt consolidation, loan restructuring, and budgeting. Debt management brings financial stability and provides long-term financial relief to the borrower from financial stress.
The following are the functions of debt management:
Hence, this is how loan restructuring and debt consolidation are parts of debt management as a broad concept. Though loan restructuring and debt consolidation are concepts under debt management, both function in different ways and are totally opposite when it comes to features.
Bottom line:
Debt consolidation and loan restructuring are concepts of debt management. Debt consolidation focuses on building the credit score by combining existing debt into a single loan at a lower interest rate. On the other hand, loan restructuring is changing the loan aspects in agreement with existing loans, like the interest rate, loan terms, or principal amount. Both debt consolidation and loan restructuring are different in nature, scope, eligibility, and functions. Hence, debt consolidation is a better approach than loan restructuring when it comes to credit building, financial stability, and financial position.
Yes, a loan modification usually gets approved when one meets the proper eligibility criteria, like proof of financial stress, etc.
It is a good idea when you want to modify the loan terms in terms of tenure extension, but when it comes to a loan principal amount change or an interest rate change, it can impact your credit score negatively.
The drawback of loan modification is that it creates a dent in your credit score when the interest rate or principal amount is changed from the loan agreement.
The eligibility varies from bank to bank. For example, IDFC First Bank requires an age above 21 years and below 60 years to be qualified for debt consolidation with a credit score of 710 and above.
No, 700 is generally considered a good CIBIL score.
The biggest killer of a credit score is irregular debt repayments.
Qualifying for a debt consolidation loan depends on the lender’s eligibility criteria, which vary from one lender to another. If you meet the eligibility criteria, then it is not difficult to get.
One can increase the CIBIL score from 600 to 700 through proper financial management, paying credit dues on time if taken, etc.
The 7-year rule for a CIBIL score refers to the marking of financial activities in the credit report for 7 years, which cannot be changed until it is a mistake.