By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
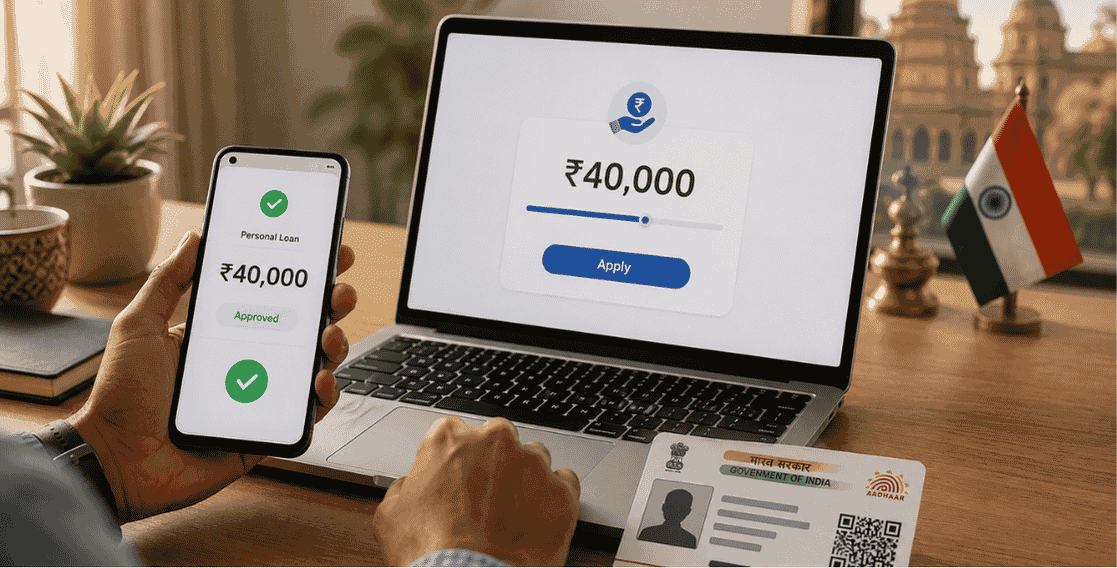
There's no actual product called an "Aadhaar card loan." What people mean is a personal loan where Aadhaar based e-KYC replaces the paperwork. Want ₹40,000 online? Punch in your Aadhaar number, verify with an OTP sent to your registered mobile, and the rest happens on screen.
Type "aadhar card loan 40000 online apply" into a search bar, and what you're really after is a personal loan you can grab fast, Aadhaar handling the digital verification instead of you hunting down paperwork. This is for anyone in India, salaried or self-employed, trying to figure out how borrowing against your Aadhaar actually works, why it's quicker, and whether you'd qualify for something as modest as ₹40,000. Real process, real eligibility, and what "without documents" is genuinely code for.
It's a personal loan, plain and simple, just one where your Aadhaar number and an OTP do the job physical ID documents used to.
RBI's never licensed anything called an "Aadhaar loan." What's actually going on is banks and NBFCs lean on Aadhaar e-KYC, a UIDAI and RBI regulated process, to check who you are electronically. Kotak Mahindra Bank breaks this down well on its own site: your Aadhaar number functions like a key, unlocking your verified details straight from UIDAI's database and skipping whatever delay a manual check would've added. People just started calling this an "Aadhaar card loan" out of habit, even though underneath it's a regular personal loan with a shortcut built into the front door.
Enter your Aadhaar number wherever the lender's asking, verify through OTP, and finish the form from there.
Roughly what this looks like in practice:
Nothing here needs you standing in a queue, which is really the whole point, Aadhaar e-KYC does away with in-person document drops entirely. And if you've already got an ICICI Bank account, you can just pull up your Insta Personal Loan eligibility through iMobile or Internet Banking without hunting down another single form.
Physical paperwork, yes, you skip that. Your income and credit history, though, still get looked at before anyone hands over money.
"Without documents" specifically means you're not scanning or mailing anything for identity or address proof, that part's handled electronically through Aadhaar. What it doesn't mean is the bank waives checking whether you'll actually repay. SBI's Pre-Approved Personal Loan leans on the same idea for existing customers, sending instant offers built off credit history and however long you've been banking there, not a fresh stack of forms. Even for something small like ₹40,000, most banks are still pulling your CIBIL score and checking your monthly income before they say yes.
Pretty much the same box a bigger loan would ask you to tick, age, income, and how steady your job actually is.
ICICI Bank's own eligibility page lists this out:
SBI plays this a bit differently, corporate employees need a credit score of 670 or better, while defence and government staff get in with a lower income threshold. Since ₹40,000 barely registers as a big ask in loan terms, some NBFCs and digital lenders loosen the income requirement further, though that's very much a lender by lender thing, nothing standardised about it.
Minutes versus hours, that's basically the gap. Aadhaar e-KYC clears you almost instantly. Physical documents mean someone actually has to sit and check them.
*T&C Apply
Several hours to a few days
Kavita's 26, works in customer service in Jaipur, brings home ₹31,000 a month, and needs ₹40,000 to handle a medical bill. She opens ICICI Bank's iMobile app, types in her Aadhaar number, and within seconds an OTP shows up on her phone. Once that clears, the app fills in her name, address, and date of birth on its own, straight from UIDAI, nothing typed manually. She uploads her latest salary slip, and since her income clears ICICI Bank's ₹30,000 requirement, her ₹40,000 gets approved and lands in her account before the day's out, not one physical paper anywhere in the process.
Strip away the branding and an Aadhaar card loan is just a personal loan with faster identity checks, courtesy of Aadhaar based e-KYC, while the bank still runs its usual income and eligibility checks underneath. For something as small as ₹40,000, that usually means approval within the day if you're going through ICICI or SBI and you clear their salary and credit bar. One thing worth double checking before you start, make sure your Aadhaar's actually linked to a phone number you can access, since the OTP step falls apart without it.
Getting a ₹40,000 Aadhaar card loan online really comes down to letting e-KYC speed through identity checks while your actual income and credit history decide the rest. Keep your Aadhaar tied to a working number, hit whichever bank's salary threshold you're aiming for, ICICI or SBI, and the whole thing, application straight through to money in hand, can wrap up before the day's even over.












