Check AI Loan Optimisation Plans to Reduce Your EMI

Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Ananya Shrivastava is a Content Writer specialising in finance-focused news, blogs, and long-form articles on Indian markets, RBI policy, personal finance, and lending. She has authored over 450 blogs and 250 news pieces, combining technical knowledge with rigorous research to simplify complex financial concepts into clear, engaging content. With a marketing-driven lens and sharp editorial judgment, she consistently achieves top Google rankings while ensuring every claim is backed by verified data.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
An Aadhaar card loan isn't something different. It is a personal loan that you get just by submitting some details and an Aadhaar card. Here, the Aadhaar card plays the role of a KYC document. For an Aadhar loan, you need a credit score, income proof, and PAN card for instant loan approval.
Running short of money and wondering whether your Aadhaar card is enough for a loan? It can help, but only with one part of the process. Lenders use Aadhaar to confirm your name and address. That alone will not get the loan sanctioned, though. Depending on the loan type and lender, you may need to provide PAN, income documents and other information for credit assessment.
Key Takeaways
You can use your Aadhaar card as proof of identity and address when applying for a loan in India, subject to the lender's KYC requirements. Banks and NBFCs accept Aadhaar for KYC on personal loans, gold loans and small app-based loans. KYC confirms your name, photo and address before any loan is paid out.
Aadhaar alone will not get your loan approved. It does not show your income or repayment history. Lenders might also ask for your PAN, income proof such as salary slips or bank statements, and check your credit report before they sanction the loan. Apply only with lenders regulated by the RBI, since fake lenders often promise quick loans on Aadhaar alone.
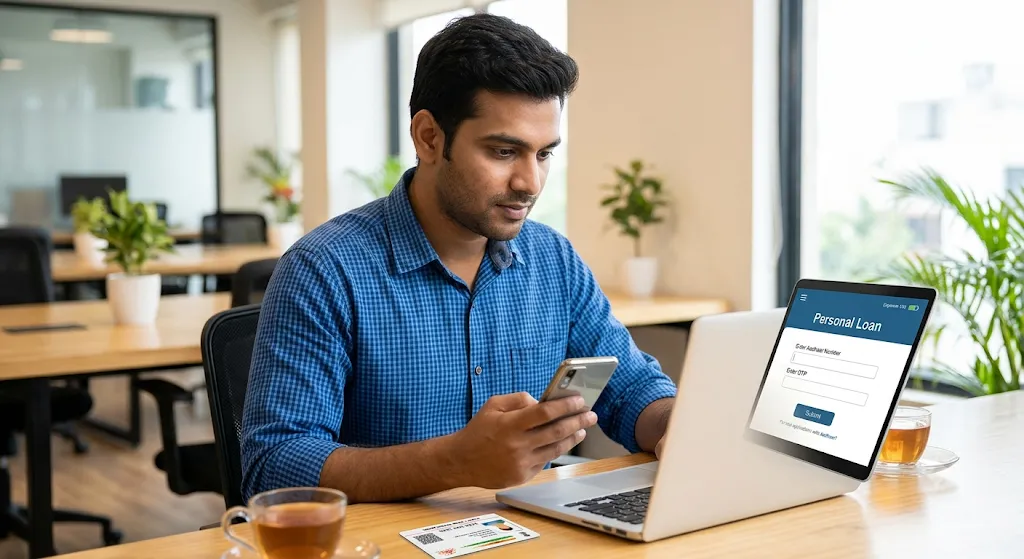
In India, you can apply for a personal loan online using your Aadhaar card as your KYC document. Most banks and NBFCs now accept online applications. The lender sends an OTP to the phone number on your Aadhaar to confirm it is you.
Follow these steps to apply for a personal loan online with Aadhaar KYC:
Once the lender approves your personal loan application and sanctions the amount, it usually credits the funds directly to your bank account.
You may use Aadhaar as an identity document for KYC when applying for eligible retail loans, subject to the lender's requirements. Your choice comes down to how much you need and whether you have something to pledge.
You do not give any security for a personal loan. Because of that, the lender studies your salary and credit score closely.
You leave your gold jewellery with the lender and borrow against it. Since the lender holds the gold, a weaker credit score may not stop you.
Some banks and NBFCs offer small loans in their apps with Aadhaar e-KYC. Some lenders may process app-based loan applications within a few hours, depending on their verification and approval procedures. Before you accept, find out the lender’s full name and every fee it charges.
The rate offered to you can be higher or lower than these starting figures.
Lenders check your identity and your repayment ability to confirm you are who you say you are and that you can repay the loan on time. Aadhaar answers only the first.
Here is a quick view of a normal loan file:
So Aadhaar verifies your identity and address. The approval of your loan application depends on your income papers and credit report.
Quick-loan seekers are a common target for scams. Run through these checks first:
None of this takes long, and it can spare you a lot of trouble.
Aadhaar shortens the KYC step. Your income, credit history and the lender’s own rules decide the rest. Make sure your Aadhaar has your current number and your PAN and income papers are in one place. Then weigh two or three offers by APR and pick the EMI you can pay without stretching.
In most cases, no. Aadhaar only confirms your identity and address. Lenders also ask for your PAN and income proof to check whether you can repay the loan.
Lenders may use your PAN as an identifier when retrieving your credit report and verifying your financial and tax-related information. Aadhaar only verifies who you are and where you live, so PAN helps the lender check your repayment history and income details.
Yes, many lenders accept a masked Aadhaar for KYC because it shows only the last four digits of your number. Some lenders may still ask for e-KYC or offline verification, so confirm with your lender before you submit it.
Some lenders do lend to first-time borrowers. They lean more on your income proof and bank statements.
E-KYC finishes in minutes, but the lender’s income and credit checks take longer. Some app loans get approved the same day.
Yes, Aadhaar works as KYC for an education loan. Many lenders also want a parent as a co-borrower.
It is fine with an RBI-regulated lender’s own app. Be careful with any app that wants money upfront or reads your contacts and photos.
It is possible if they also get your OTP. Look at your credit report every few months and lock your biometrics.
Yes, the lender’s check usually appears as an enquiry. Many enquiries in a short time may lower your score.
A Virtual ID is a stand-in number linked to your Aadhaar, so you do not have to reveal the real one. Many lenders accept it for e-KYC.
Start your journey today
Apply Now*T&C apply