By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
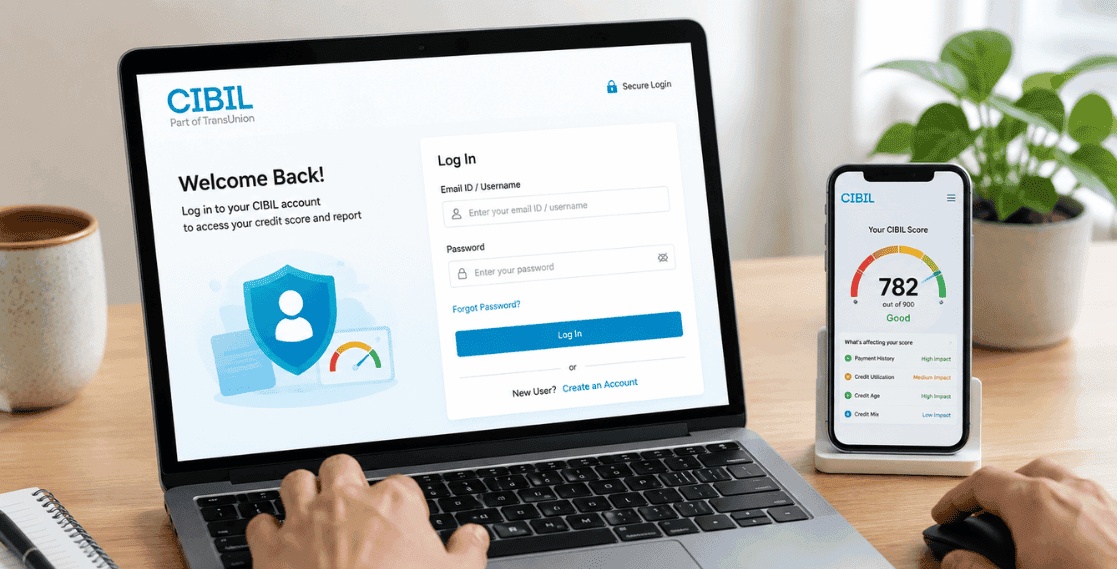
Head to myscore.cibil.com and enter your username and password, or just punch in your registered mobile number for an OTP instead. No account yet? You can set up a free CIBIL Score account right on CIBIL's own site.
Checking your credit health means logging in to your CIBIL Score account at some point, whether that's before applying for a loan or just a habit you're building. This one's for anyone in India who wants to register, log in, and actually use their account without getting stuck somewhere along the way. We'll cover setting up the account, logging in, what to do if you forget your details, and how all of this ties back to your actual credit report.
It's your personal login on TransUnion CIBIL's platform, and it's what gives you access to your score, your full report, and ongoing monitoring.
Once you're registered, this becomes your go-to spot for tracking how your credit stands over time. Per CIBIL's own site, the score itself runs from 300 to 900, closer to 900 meaning stronger creditworthiness. And it's not just a number sitting there either, your account also opens up your detailed Credit Information Report, listing your loans, cards, repayment history, and anything else a lender would see if they pulled your file.
Head to CIBIL's enrollment page and fill in your personal details, PAN included, so they can verify who you actually are.
Here's roughly how that goes:
Once you're through this, logging back in through myscore.cibil.com whenever you need your score or report is just a couple of clicks away.
Head to the login page, punch in your username and password, or skip straight to OTP using your registered mobile number.
Here's what that generally looks like:
First time logging in after registering? Going the mobile number and OTP route usually beats trying to remember a username you just created five minutes ago.
Your PAN details, a working email, and a mobile number you can actually access- that's really all it takes.
Here's the full list:
Unlike opening a bank account, there's no physically submitting or uploading paperwork here. CIBIL verifies you electronically using your PAN and the details you type in.
Forgot your username or password? You can recover it from the login page, though the exact steps depend on which authentication options are set up for your account. This may involve OTP verification on your registered mobile number, email confirmation, or other identity checks, so the recovery process can vary by user.
The login page usually has separate options for a lost username versus a forgotten password. Since your account's tied to that mobile number and email, recovery generally means an OTP verification followed by resetting whatever you've lost. Changed your mobile number entirely since registering? Expect a slightly longer verification process, since CIBIL needs to be sure it's actually you before handing over account access.
A free CIBIL account gives you one score and report per calendar year, directly from the official portal. Paid subscription plans, available in 1, 6, or 12-month tenures, unlock multiple checks during that period, plus features like score alerts, a score simulator, and dispute tracking depending on the plan.
*T&C Apply
Just checking your score once in a while before a loan application? Free covers that fine. Actively trying to build your score or want to catch changes as they happen? Paid gives you a lot more visibility.
Once you're in, head to the report or score summary section on your dashboard, that's where your full Credit Information Report lives.
You'll find your personal details, every credit account you hold, repayment history for each, and any enquiries lenders have made against your name. Per CIBIL's own site, checking this regularly helps you catch mistakes early and see exactly what a lender sees before they decide on your loan or card application. Spot something wrong? CIBIL's platform lets you raise a dispute right from inside your account, no separate calls or emails needed.
Nope, checking your own score doesn't touch it at all; it's what's called a soft inquiry.
CIBIL's own site actually addresses this directly, reassuring users that checking your own score won't drag it down. That's a different story from what happens when a lender pulls your report while you're applying for something; that's a hard inquiry, and enough of those close together can nudge your score a bit. But logging into your own account, weekly, monthly, whenever, carries zero risk like that.
Meera's 29, works in marketing in Bengaluru, and wanted to check where she stood credit-wise before applying for a home loan. She signed up for a free CIBIL account, PAN, date of birth, email, the usual, verified her mobile with an OTP, and logged in. Her score came up at 768, solidly in the range lenders like to see. She also spotted something off, an old credit card she'd closed years back was still showing a ₹1,200 balance, clearly a reporting error. She flagged it right there through the dispute option in her account, no phone call, no written letter, and it got sorted out.
Logging in to your CIBIL Score account is genuinely simple once you're registered- username and password, or the quicker mobile and OTP route- either works. Since checking your own score never hurts it, there's really no reason to hold off logging in regularly and keeping tabs on things. Stick with the free yearly option or move up to a paid plan for closer monitoring; either way, keeping your login details handy just makes life easier when you actually need them.
Setting up and logging in to your CIBIL Score account really only takes a few minutes, and it's one of the easiest ways to keep an eye on your credit health before any big financial decision. Since checking your own score costs you nothing, score-wise, there's genuine value in logging in every so often to review your report and catch anything off early. Whether you're gearing up for a loan or just building better habits, having your CIBIL account details ready makes the whole thing a lot less of a hassle.












