By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
Disclaimer: The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Vidhi Chauhan
Vidhi Chauhan is a copywriter and content writer with extensive experience creating high-quality, SEO-driven content across multiple industries, with a strong focus on fintech. She has written extensively on GST, banking, personal loans, business loans, credit cards, income tax, insurance, and other financial topics, helping Indian readers understand complex concepts through clear, accurate, and engaging content.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
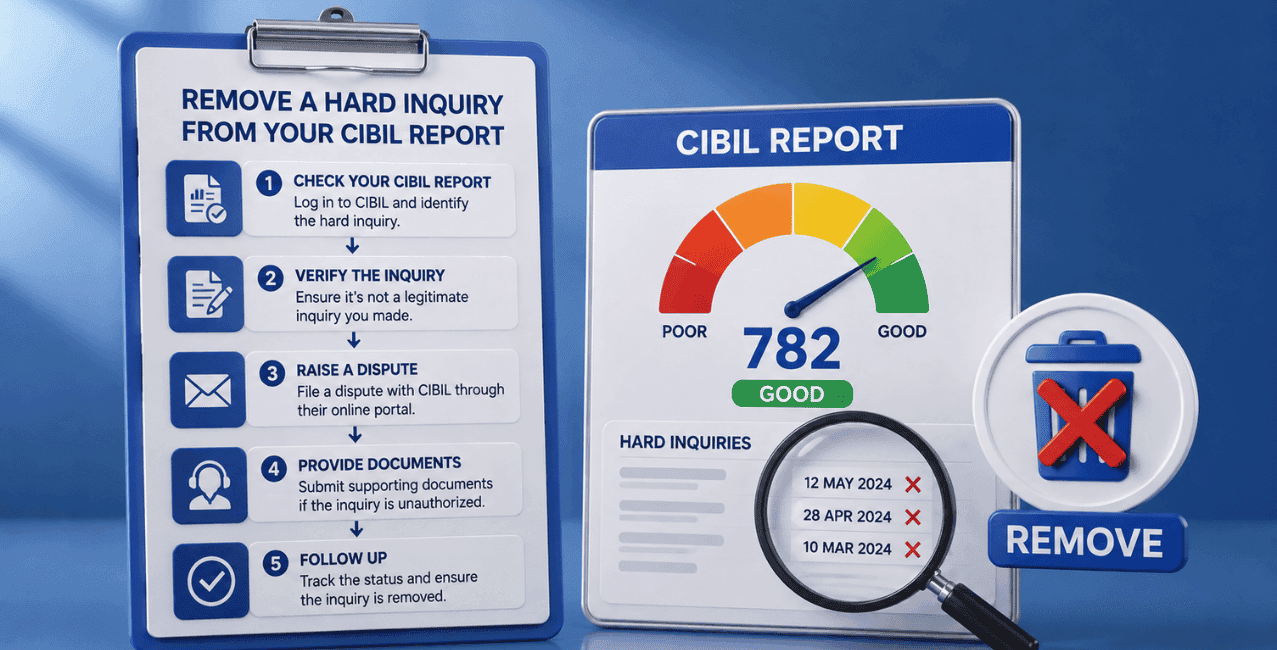
The removal of a hard inquiry is possible when it is wrong, unauthorised, a duplicate, or associated with an application that was never made by you. Genuine hard inquiries resulting from proper credit applications stay on your credit report. The presence of a mysterious inquiry does not necessarily imply anything fishy; the inquiry might have resulted from a third-party marketplace, a Buy Now Pay Later program, or a lender collaborating with another financial entity. Yet, it should be investigated. LoansJagat assists you in comprehending credit processes and making the right borrowing choices. This blog sheds light on how you can recognize a wrong hard inquiry and contest it.
CIBIL needs confirmation from lenders before altering the credit inquiry information.
Hard inquiries are noted whenever the bank or lending agency checks your credit report in connection with a credit application process. It normally takes place whenever you apply for personal loans, home loans, car loans, or a credit card and authorise the lender to check your credit history.
It should be noted that hard inquiry is not the same as soft inquiry. Soft inquiries happen when you request to see your credit report or when you receive an offer for a credit card from some lending company.
A hard inquiry will be added when:
In such situations, each individual lender may register his or her own inquiry. This results in multiple hard inquiries being added to your credit report.
Recent multiple hard inquiries are a sign that you are applying for credit often and may raise red flags with credit agencies that consider you.
In case you come across an inquiry that was not initiated by you, then you can challenge that inquiry with the relevant credit reporting agency or lender. Hard inquiry letters are used for such purposes.
Typically, you can't have a hard inquiry removed from your credit report just because you want it removed. This is due to the fact that the inquiry has been made legally because you applied for credit and the creditor obtained access to your credit report with your consent. In this case, the hard inquiry will stay on your credit report for the period during which it should be reported.
It might be possible for you to remove or correct the inquiry if it was reported incorrectly. Some of the most common cases are the following:
Unrecognised application: the inquiry is associated with the loan/credit card application you didn't make.
You can take the following actions in case of an inaccurate inquiry:
The process of filing a dispute varies between credit bureaus, and you will need to check the particular bureau's dispute process before doing anything else.
Yes, an unauthorised hard inquiry can be rectified or deleted once confirmed by the lender as it was recorded inaccurately. However, based on the guidelines of TransUnion CIBIL, it should be noted that the credit bureau will not be able to make any changes to your CIBIL report independently until confirmation from the respective bank or financial institution is received.
In case you see any unknown credit inquiries, it does not automatically mean that there was any fraud. The inquiry may be related to a loan/credit card taken from a third-party marketplace, a Buy Now Pay Later service, or a lender who works in collaboration with some other institution.
*T&C Apply
Analyse your CIBIL Report: Look at the Enquiries portion and identify the entries that are strange to you.
In case the lending institution does not have any proof of your application for the credit, CIBIL suggests requesting the lender to inform CIBIL to remove the inquiry from your report.
A hard inquiry can be removed if it is erroneous, unauthorised, duplicative, or related to an application that you have never applied for. Valid inquiries normally stay on your credit report. The process involves checking your report, contacting the creditor, disputing the issue, and ensuring the problem gets sorted out.
This is not always true, because CIBIL Score depends on various things like the repayment record, credit usage, credit age, etc.
It may vary based on the credit bureau and the rules governing it. You should consult the latest guidelines of the bureau to find out how long the inquiry stays on your credit report.
This is not possible because your inquiry is not the same as the one done by the lender.
Yes, because the inquiry is typically linked to the examination of the application rather than the approval of the application.
No, cancellation of the application will not necessarily negate the inquiry as long as the inquiry was made in good faith during the examination. The possibility of getting anything done will depend on the circumstances surrounding the inquiry.
It all depends on whether the lender conducts a credit inquiry before making the offer to the applicant.
This is possible if the loan application is made on a platform that links the borrower to different lenders. Hence, it will be important to know which institutions can have access to your credit information before making the application.
In most cases, avoiding credit in itself is not the best solution. It would be more appropriate to make comparisons of the available options before applying for credit based on the lender's requirements.
While having several inquiries recently may affect your credit application behavior perception by the future lender, lenders usually take into account the overall picture of your credit profile.
First, go through the dispute resolution process and the explanation given by the lender or the bureau. If you think that the information is incorrect despite the resolution of your dispute, you may use the grievance process available at that institution.












