By continuing, you agree to LoansJagat's Credit Report Terms of Use, Terms and Conditions, Privacy Policy, and authorize contact via Call, SMS, Email, or WhatsApp
The information published on LoansJagat is intended for general informational and educational purposes only and should not be considered financial, legal, or investment advice. Interest rates, loan terms, statistics, and other data may change over time and may vary by lender or source. Please verify the latest information and consult a qualified financial advisor or the respective Bank/NBFC before making any financial decisions.
Subscribe Now
About the author
Diwaker Sharma
Diwaker Sharma is a finance content specialist with expertise in banking, personal finance, credit cards, loans, fintech, and financial news. An MBA in Finance with prior experience in the banking sector, he combines industry knowledge with SEO and content strategy to produce insightful, research-backed articles. Passionate about making finance accessible, he transforms complex financial concepts into clear, engaging content that empowers readers to make smarter financial decisions with confidence.
Related Blog Post
Simplify All Your Loans Into One Affordable EMI

Customers Served

Debt Consolidated

1200+ Reviews

Locations in India
Club all Loans & Credit Card Bills into Single EMI

Quick Apply Loan
Consolidate your debts into one easy EMI.

Takes less than 2 minutes. No paperwork.

10 Lakhs+
Trusted Customers

2000 Cr+
Loans Disbursed

4.7/5
Google Reviews

50+
Banks & NBFCs Offers
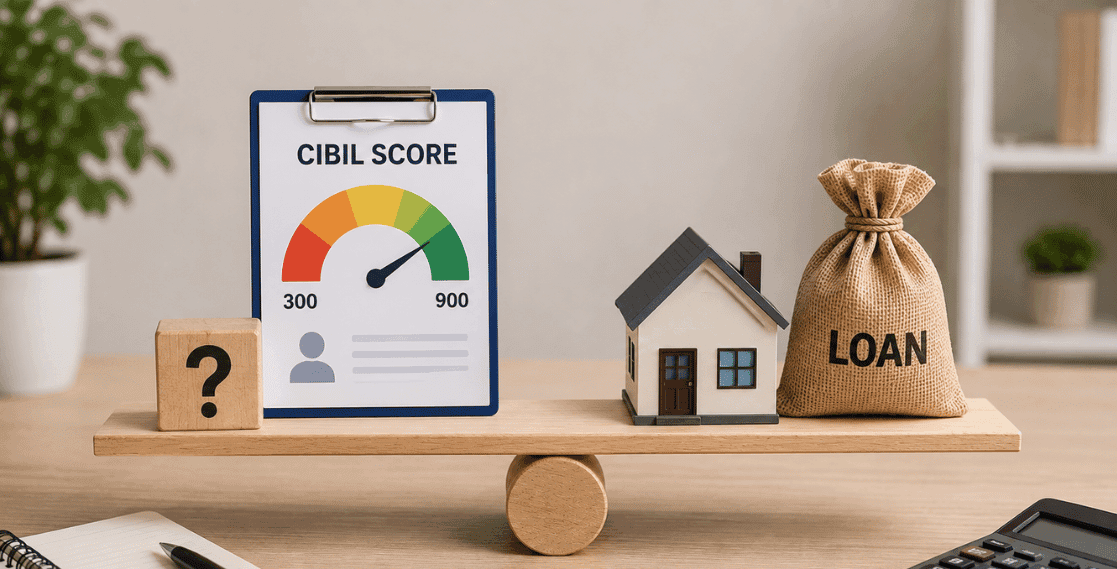
If you have never borrowed before, you don't actually have a CIBIL score, there's no repayment history for it to be built on, so your report just shows “NH” or “NA” instead of a number. RBI's Master Direction from January 6, 2025 makes clear that lenders can't turn you down purely because you're missing that history.
Applying for your first loan, education loan, personal loan, maybe your first credit card, and the same question always comes up: what is required CIBIL score for a loan when you've genuinely never borrowed a rupee before? This one's for students, fresh graduates, anyone stepping into formal credit for the first time in India. We'll cover what a missing score actually means, whether it stops you from getting approved, what documents required for CIBIL score assessment actually look like in place of a number, and how to build something from nothing.
The simple answer is you don't have one. The bureau needs actual repayment history to calculate a score, and without that, your report just reads “NH” or “NA.”
TransUnion CIBIL works out a 3-digit number, somewhere from 300 to 900, based entirely on how someone's handled loans and credit cards in the past. Never taken either? There's nothing for the bureau to go on. And this isn't some black mark against your name either, it's just a neutral status that says you're new to the system, nothing more.
There isn't one, actually, not a fixed minimum anyway. RBI hasn't set one, which means it's really down to whatever policy each individual lender follows internally.
Minister of State for Finance Pankaj Chaudhary told the Lok Sabha on August 25, 2025, that RBI has never prescribed a minimum score for loan approval. He pointed straight to RBI's Master Direction from January 6, 2025, which says first-time borrowers shouldn't get rejected just because they've got no credit history. In real terms, your credit report is just one piece of the puzzle a lender looks at, not a locked gate.
NH means No History, you've simply never used credit before. NA usually means Not Applicable. Either way, it's about missing data, not bad behaviour.
Here's what usually causes each one:
Neither status counts against you the way an actual low score would. It's just the bureau saying, we don't have enough to work with here, which, honestly, describes every single first-time borrower out there.
Since there's no CIBIL score to check yet, standard lenders lean on income and repayment capacity documents instead, not utility bills or UPI history, which belong to a separate, newer category of assessment.
For standard loan underwriting, here's what usually gets asked for:
It's worth being clear on 1 distinction here. TransUnion CIBIL's traditional scoring model evaluates only formal credit history, things like credit cards and past loans, and does not factor in utility bills or digital payment activity. Utility bills and UPI transaction history aren't standard substitutes within normal bank underwriting either, most banks and NBFCs still centre their decision on income, employment stability, bank statements, and overall repayment capacity, exactly the documents listed above.
Where utility bills and digital payment footprints do come into play is with a separate, growing category, alternative credit scoring, mostly used by fintech lenders and some NBFCs specifically to assess thin-file or first-time borrowers who fall outside traditional credit bureau coverage. RBL Bank's own blog on this shift confirms that fintechs are partnering with banks to combine traditional and alternative data for a fuller view of a borrower, under the RBI's regulatory sandbox framework, though this isn't yet how mainstream CIBIL score assessment or standard bank underwriting works. What exactly gets asked for still shifts by lender and loan type, so confirming directly with your chosen bank or NBFC beats assuming 1 process applies everywhere.
Yes. RBI's directive means lenders are supposed to evaluate first-timers using other financial signals instead of just filtering out anyone without a score.
That said, not every lender handles this identically. Even with no mandatory minimum score in place, banks are still expected to do their homework, checking whatever repayment history does exist, watching for restructured or settled accounts, confirming nothing's been written off. If your slate's genuinely clean though, that due diligence mostly just shifts toward your income and paperwork instead.
Start small, stay consistent, and repay on time, that's really the whole formula for building something trackable.
Here's a route that actually works:
Expect this to take several months of steady activity before an actual number shows up on your report.
Ananya's 24, fresh out of college, living in Pune, and applying for her first personal loan, ₹1,50,000, to fund a professional certification course. Never taken a loan before, never held a card, so her report just showed "NH." Instead of turning her down flat, the lender asked for her last 3 salary slips, 6 months of bank statements, and her Form 16. With a steady ₹42,000 monthly income and a healthy bank balance behind her, she got approved at a standard rate, her documents did the talking, not a missing score.
NH is about missing data. A low score is about an actual track record of trouble, missed payments, defaults, that kind of thing. Lenders treat these completely differently.
*T&C Apply
Usually it just comes down to genuinely not having any credit activity, nothing to do with any mistake on your part.
Typical situations:
Every single one of these is about incomplete information, not proof you've done something wrong, and that's exactly the distinction RBI's current guidance expects lenders to keep in mind.
If you're a first-time borrower without a CIBIL score, there's genuinely no need to panic, RBI's own directions make it clear that missing credit history alone can't be used to reject your application. What actually counts right now is having your documents required for CIBIL score assessment ready, salary slips, bank statements, ITRs if they apply, since these become what the lender actually leans on. Start small, whether that's a secured card or a modest loan, stay consistent with repayments, and that's genuinely the fastest way to turn NH into an actual, working score.
No CIBIL score as a first-time borrower doesn't shut the door on getting a loan, RBI's own rules require lenders to look past a missing score entirely. Keep your income documents, bank statements, and whatever financial records you've got ready to go, since these are what actually fill that gap for now. From there, start small, stay consistent, and that NH eventually turns into a real, working score.